Conway, SC Real Estate News 

Century 21 McAlpine Blog

The Agents and Staff at Century 21 McAlpine love our area and one another! We hope to share some of our daily activities with you and see how we might better serve our community!


Sept. 29, 2026

How Recent Buyer Agent Commission Changes Affect Grand Strand Buyers

You're buying a home on the Grand Strand and you're hearing that the rules around who pays for the buyer's agent changed. Here's the honest picture. The industry-wide changes that took effect in 2024 reshaped how buyer agent commissions get discussed, disclosed, and paid. For buyers shopping Myrtle Beach real estate or anywhere else on the strand, the practical impact is more nuanced than most media coverage suggests. Let me walk you through what actually changed and what it means for your specific purchase.

What Actually Changed

The National Association of Realtors settlement and subsequent industry practice changes did a few specific things.

  • Removed the requirement to advertise buyer agent commissions in the MLS. Sellers can still offer to pay buyer agent commission, but they no longer have to include it in the MLS listing.
  • Required buyer agents to have signed written agreements with buyers before touring homes. The agreement must specify how the buyer's agent gets paid.
  • Made compensation more directly negotiable. Buyers, sellers, and agents can structure compensation more flexibly than the old default model allowed.

What didn't change: sellers can still pay buyer agent commissions, and in many transactions they still do. The mechanism is just different than it used to be.
How Recent Buyer Agent Commission Changes Affect Grand Strand Buyers

What This Means for Your Practical Buying Experience

Here's what actually changes when you're shopping.

You'll sign an agreement with your buyer's agent before touring. This agreement specifies what your agent will do for you and how they get paid. Read it carefully. Ask questions. Understand what services you're getting and what the compensation structure is.

You may see fewer buyer agent commissions listed on MLS listings. Some sellers still advertise them; others don't. When it's not advertised, your agent will need to ask the listing agent directly what compensation is being offered.

You'll have more conversations about compensation upfront. Buyer-agent relationships now start with clearer discussions about how the agent gets paid, which is generally healthy but requires more upfront alignment.

Who Actually Pays for Your Buyer's Agent Now

The compensation structure now takes a few different forms.

Seller pays through the closing statement. Still very common. The seller offers to pay buyer agent commission, the buyer's agent receives it at closing, and the buyer doesn't directly write a check.

Buyer pays through negotiated arrangements. The buyer's agent agreement specifies what the buyer will pay if the seller doesn't cover it. This might be a percentage, a flat fee, or a minimum amount with adjustments based on what the seller offers.

Split arrangement. Some transactions involve the seller covering part and the buyer covering the difference between the seller's offer and the agreed-upon buyer agent compensation.

The specifics get negotiated as part of the offer. Understanding this before you start shopping helps you write stronger offers.

How This Affects Offer Strategy

The compensation flexibility now affects how competitive offers get structured.

Buyers with cash flexibility can offer to cover their own agent's compensation as part of a stronger offer. The seller pockets more of the purchase price and often views the offer more favorably.

Buyers with tighter budgets may need to request seller-paid buyer agent commission as part of their offer terms. Sellers can accept or counter based on other offer strengths.

Financing implications matter too. Some loan programs allow certain buyer costs to be financed. Others limit how compensation can be structured. Ask your lender specifically about your loan program.

Whether you're looking at inventory in North Myrtle Beach real estate or newer subdivisions like Wild Wing Plantation, the strategic conversation with your agent should include compensation structure alongside price and terms.

What Buyers Should Verify Before Signing With an Agent

The written buyer-agent agreement matters more than most buyers realize.

  • Compensation amount or percentage. Understand exactly what you agree to pay if the seller doesn't cover it.
  • Duration and exclusivity. Some agreements bind you to work only with that agent for a specific period.
  • Geographic and property-type scope. What areas and property types does the agreement cover?
  • Services included. What will the agent actually do for you beyond opening doors?
  • Termination provisions. How can you end the agreement if the relationship isn't working?
  • Protection clauses. Are you obligated to work with the agent on properties you've already toured with them?

Don't rush this signing. A weak buyer-agent agreement can cost you more than a bad offer on a specific property.

The Grand Strand-Specific Realities

A few dynamics that affect Grand Strand buyers specifically.

Out-of-state relocation buyers often need more agent services — video tours, remote coordination, local market intelligence, referrals to lenders, inspectors, and contractors. Higher service level often justifies clearer compensation structures.

Investor buyers shopping for vacation rentals or long-term rentals often have specific due diligence needs that experienced agents charge for accordingly.

Luxury and specialty property buyers work with agents who bring specific market expertise that supports higher compensation structures.

First-time buyers benefit from agents with more hand-holding, education, and process navigation — services that need to be compensated somehow.

Match the agent's expertise and services to your actual needs, then align on compensation accordingly.

What Nobody Tells Buyers About These Changes

Two patterns worth flagging.

The changes generally favor sophisticated buyers who understand what they're agreeing to. Buyers who read the agreements carefully, negotiate services and compensation deliberately, and structure offers strategically often come out ahead. Buyers who rush through the paperwork without understanding it may end up with agreements that cost more than necessary.

Great buyer agents are still worth their fee. The compensation changes didn't reduce the value good agents deliver — market knowledge, negotiation expertise, due diligence guidance, and network relationships all still matter. The changes just made the value exchange more explicit. If you find an agent whose expertise justifies the compensation, the arrangement should still work well for you.

Two Things I Tell Every Grand Strand Buyer Navigating These Changes

First, interview a few agents before signing an exclusive agreement. The relationship you're entering matters. Understand each agent's expertise, communication style, and compensation structure before committing. Interviewing multiple options doesn't obligate you to pick anyone — but it does give you the context to make a good decision.

Second, discuss the compensation strategy as part of your offer strategy. Whether you request seller-paid commission, cover it yourself, or negotiate a split arrangement changes how competitive your offer looks. Talk this through with your agent explicitly for each property you consider making an offer on. For competitive markets like the newer inventory in Conway real estate, offer structure matters more than ever.

Key Takeaways

The NAR settlement changed how buyer agent commissions get discussed, disclosed, and paid, but on the Grand Strand sellers still cover them in most transactions. Buyers now sign written agreements with an agent before touring, and MLS listings may or may not advertise buyer agent commissions, so your agent may need to ask sellers directly. Compensation shows up in multiple forms now — seller-paid, buyer-paid, or a split — and offer strategy has to include structure alongside price and terms. Read the buyer-agent agreement carefully before you sign it, and interview agents who understand both the settlement and the local market.

Frequently Asked Questions

Do I have to sign a buyer-agent agreement to see homes?

Under current rules, yes — agents are required to have signed written agreements before showing homes. You can sign a short-term or limited-scope agreement to tour a specific home if you're not ready to commit to a long-term exclusive arrangement.

Can I negotiate the buyer agent commission?

Yes. Compensation is negotiable between you and your buyer's agent. Discuss it upfront. Some agents have standard rates; others adjust based on services provided, transaction complexity, or specific market conditions.

What happens if the seller offers less commission than my agent's agreement specifies?

Depends on your specific buyer-agent agreement. Some agreements require you to cover the difference. Others let you negotiate with the seller to increase their offer, walk away from the property, or restructure the deal. Read your agreement carefully.

Can I fire my buyer's agent if the relationship isn't working?

Yes, but the specific process depends on your agreement. Some agreements allow termination with written notice. Others have specific conditions or time requirements. Understand these terms before signing.

Do these changes affect the total price I pay for a home?

Indirectly. In practice, home prices reflect a lot of factors including how commissions are structured. Some analysts argue the changes will eventually reduce total transaction costs; others argue buyers may end up paying commission directly rather than seeing it embedded in the price. The specific impact varies by market and transaction.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Sept. 28, 2026

How Conway, SC Is Becoming the City of Halloween

Something's happening in Conway every October, and if you haven't experienced it yet, you're missing one of the most distinctive small-town celebrations in the entire Southeast. Downtown Conway transforms into what locals have started calling the City of Halloween — and it's not marketing hype. It's the real thing. The historic architecture along Main Street and Third Avenue, the oak canopy dripping Spanish moss, the Waccamaw River running dark and slow past the downtown Conway Riverwalk, and a community that shows up for each other in a way most modern towns have forgotten how to. Let me walk you through what actually happens here in October and why it's worth experiencing yourself.

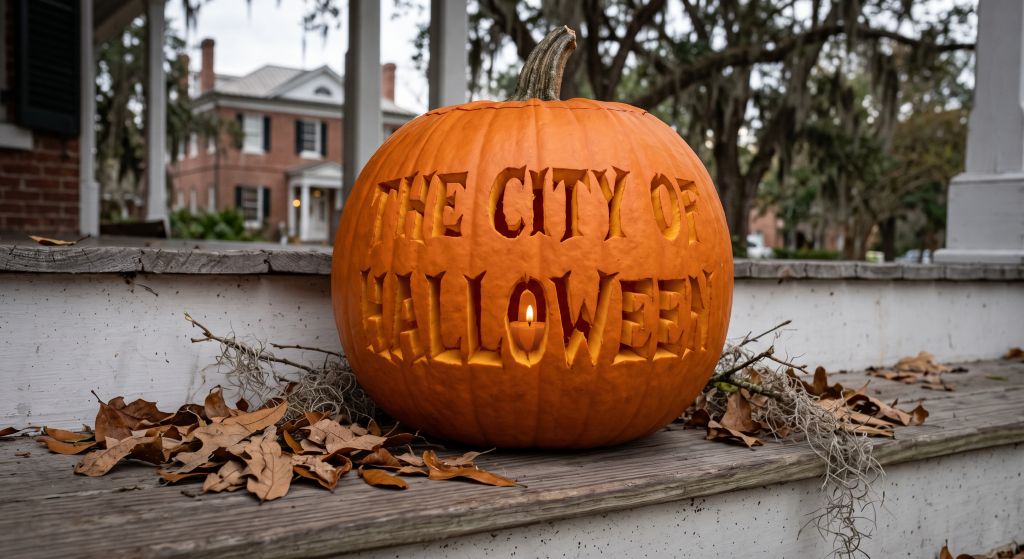
Conway SC City of Halloween

What Makes Conway the Perfect Halloween Town

Some towns dress up for Halloween. Conway already looks the part.

The historic district's Victorian and Queen Anne homes have wraparound porches, turret rooflines, iron fencing, and details that predate the twentieth century. These aren't renovated to look old. They actually are old. Some of these houses have been standing since the 1880s.

The trees do the rest. Ancient live oaks arch over Kingston Street, Main Street, and the residential blocks around downtown. Spanish moss hangs from the branches. In October, when the light angle shifts and the air finally cools off, that combination of historic homes and oak canopy takes on a mood you can't fake.

Then there's the river. The Waccamaw isn't a bright blue postcard river. It's a blackwater river — dark, still, tannin-stained, lined with cypress trees whose knees break the water surface. In fog, at dawn, on a moody October evening, it's genuinely atmospheric. Some visitors say it looks like something out of a Southern gothic novel. That's because it does.

Put Victorian architecture, ancient live oaks with Spanish moss, and a blackwater river in the same small downtown, and you get a town that photographs like a movie set for a Halloween film — except nobody had to build the set.

The Historic District in October

The historic district is where the whole thing comes together.

Individual homeowners here take Halloween seriously. Not with plastic skeletons from the drugstore. With real effort. Elaborate porch scenes. Full-yard installations. Homes that already look like they belong in an old ghost story become fully committed Halloween destinations.

Walk down Main Street or the residential blocks around Kingston and Third Avenue on an October evening and you'll see what committed neighborhood decoration actually looks like. One porch has an entire graveyard set up under the eaves. Another has smoke machines going. Another has installations that clearly took weekends to build.

Kids notice. That's part of why it works. Families push strollers under the oaks. Older kids ride bikes from one house to the next. Adults do their own version of the walk in the evenings, phones out, photographing what neighbors created.

The walkability makes it all possible. The historic district is genuinely designed for walking. Real sidewalks. Streetlights that don't overpower. Blocks laid out on a human scale. You can spend an entire evening walking a few square blocks and see more decorated homes than you'd see in a whole subdivision of newer construction.

Trick-or-Treat Night

Halloween night itself is when the identity really shows.

Families drive in from all over Horry County. Parents who live in newer subdivisions further out bring their kids to the historic district specifically because the experience is better than the standard suburban version. The streets fill up. Porches light up. Every house that's decorated is also handing out candy, often with the homeowners in costume themselves.

The mix of kids you see tells you a lot about the town. Toddlers in strollers doing their first Halloween. Elementary-age kids running from house to house. Middle schoolers pretending they're too cool but clearly having fun. Teenagers helping the smaller kids. Parents catching up with each other on the sidewalks. Grandparents on porches handing out candy and complimenting costumes.

Local restaurants stay open later and adjust their menus for the evening. Coffee shops turn into meetup spots for parents taking a break. The whole thing is genuinely a community event rather than just a marketing angle.

The Riverwalk Atmosphere

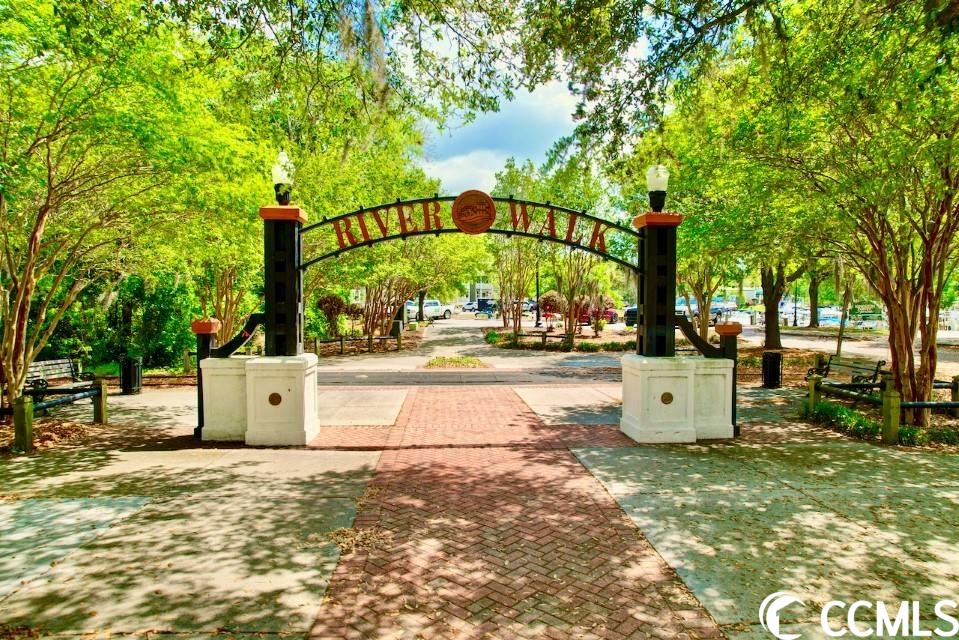
Conway SC RiverwalkThe Waccamaw Riverwalk brings another dimension to the season.
Evening walks along the river in October — with the cypress reflections in the dark water, the changing color of the trees, and the low light angle — create the specific mood that pumpkin patches and hay rides only approximate. The Riverwalk isn't decorated for Halloween the way individual homes are. It doesn't need to be. The natural atmosphere does the work.

Kayakers on the Waccamaw during golden hour in October take photos that would look staged if they weren't real. The river becomes an active part of the town's Halloween identity rather than just a backdrop.

Locals know that the Riverwalk after dark in October is one of the most distinctive experiences the Grand Strand offers. Not scary. Not gimmicky. Just genuinely atmospheric in a way manufactured entertainment can't match.

The Community Events That Anchor the Season

Beyond individual home decorations, Conway has built an ecosystem of programming that runs through October.

Downtown merchants coordinate seasonal window displays that turn the retail streets into a walking tour. Storefronts along Third Avenue and Main compete good-naturedly for the most creative displays. Coffee shops adjust their menus. Restaurants offer seasonal specials. Some of the best pumpkin-spice everything on the Grand Strand shows up in downtown Conway from mid-September through early November.

Community groups organize costume events, family-friendly gatherings, ghost walks, and specific programming for kids. Local churches sometimes host trunk-or-treat events for families who want a controlled environment. The Chamber of Commerce and local business alliance coordinate promotional programming that leverages the natural draw.

Coastal Carolina University adds another layer. CCU students, faculty, and their families participate in the community activities in ways that connect the university more visibly to the town. Home football weekends in October combine with Halloween activity to create some of the busiest and most vibrant weekends of the entire Conway year.

The Neighborhoods That Go All In

Different Conway neighborhoods approach October with different intensities, and locals know the map.

The historic downtown district is unmistakably the epicenter. If you want to experience Conway Halloween at its most concentrated, this is where you go. Kingston Street, Main Street, Third Avenue, and the blocks around them are consistently the most decorated and most walked.

Established residential neighborhoods a few blocks from downtown often develop their own reputations for specific streets that go especially hard. Word travels among Conway parents about which blocks are worth walking with kids on Halloween night. Some streets have such committed decoration that they draw traffic from all over town.

Newer subdivisions further from downtown participate but with a different character. More family-focused. Kid-centered. Trick-or-treat oriented. The historic district's atmospheric appeal is complemented by suburban Halloween that works especially well for families with younger kids.

Even golf and amenity communities develop their own seasonal culture — not as visibly Halloween as the historic district, but with community events and neighborhood decorations that support the broader October vibe.

The Ghost Stories Nobody Quite Knows the Origin Of

Every historic Southern town has stories. Conway is no exception.

The Kingston area has houses with reputations. Some are genuinely well-documented historic homes with real stories about the people who lived and died in them. Others have accumulated local folklore over the decades that may or may not have any factual basis. Either way, on an October evening walking under the oaks past homes that predate anyone currently alive, the stories feel plausible.

The Waccamaw River itself has generations of stories attached to it. Local storytellers, historical societies, and various ghost tour operators keep the folklore alive. Whether you take any of it seriously or not, the storytelling tradition is part of what gives the season depth.

Cemeteries in and around downtown Conway hold graves dating back generations. Some of the older ones sit under Spanish moss in a way that's genuinely striking. Local historians offer educational programming that touches on the history without turning it into commercial spectacle.

How the Weather Cooperates

Grand Strand October weather is nearly perfect for a Halloween celebration.

Days stay warm enough that outdoor activity is comfortable — usually mid-70s to low-80s through most of the month. Evenings cool off enough that you actually want a light jacket and hot cider makes sense. Humidity drops from summer highs to something manageable. Rain is less frequent than in summer. The trees begin their color change — later than New England but visible enough to matter.

By late October, the atmospheric quality is exactly what Halloween is supposed to feel like. Cool but not cold. Slightly moist air. Long shadows. Early sunsets. The kind of light and temperature that makes walking around outside at night feel more meaningful than it does in summer heat or winter chill.

What Nobody Tells Visitors About Conway in October

A few things that first-time October visitors consistently note.

The community engagement is real. This isn't tourist theater. Locals participate because they want to, not because a marketing committee organized it. That authenticity is what makes the whole thing feel different from purpose-built Halloween destinations.

The pace is slower than you'd expect from a well-known event town. Conway hasn't been commercialized into a Halloween tourist trap. You can still get a table at a restaurant. You can still park downtown. The town handles the season with grace rather than chaos.

The whole family works. Grandparents on porches. Parents pushing strollers. Kids of every age. Dogs in costume. This isn't a season for one specific demographic — it's a community event that includes everyone.

The best experiences aren't necessarily the biggest events. Some of the most memorable October moments in Conway are simple ones. Walking under the oaks on an unhurried evening. Stopping at a coffee shop and finding an unexpected seasonal drink. Catching sunset over the Waccamaw. Talking to a neighbor on a decorated porch about how they built their installation.

How to Actually Experience Conway's Halloween Season

If you're planning a visit, a few practical suggestions.

Come at least twice if you can. One evening walk through the historic district after dark. One daytime visit for downtown coffee, exploring the Riverwalk, and seeing the town in daylight. The two experiences complement each other.

Come during the week if you have flexibility. Weekend evenings are more crowded but also more energetic. Weekday evenings are quieter and let you appreciate the atmosphere without the crowd energy.

Bring a camera or make sure your phone has storage. You'll take pictures whether you plan to or not. The lighting and mood produce photos that people who weren't there always ask about.

Wear comfortable shoes. The best way to experience downtown Conway in October is on foot. Sidewalks. Streets. Riverwalk. You'll cover more ground than you expect.

Stop and talk to people. The community engagement is what makes this town different. Compliment somebody's porch decoration. Ask a shop owner what their favorite October moment has been. Chat with the person handing out candy on Halloween night. That's how you experience Conway rather than just visit it.

Why It Matters That Conway Does This

American small towns have been quietly losing what made them special for decades. Chain stores replaced local businesses. Screens replaced front porches. Mobility fragmented multi-generational neighborhoods. Community events got outsourced to municipal calendars nobody reads.

Conway has held on to more than most. The Halloween season is one visible expression of the underlying community fabric — but the fabric exists year-round. Neighbors know neighbors. People show up for each other. The historic district feels like a real neighborhood rather than a preserved museum.

When you experience Conway in October, you're seeing what small-town America is supposed to feel like when a community actively participates rather than passively consuming what someone else provides. That's rare now. It's worth appreciating when you find it.


Key Takeaways

Conway's October transformation into the City of Halloween isn't marketing — it's a real community celebration built on the town's naturally Halloween-ready character. Historic Victorian architecture in the downtown district, ancient live oaks draped with Spanish moss, and the atmospheric blackwater Waccamaw River combine to create a physical setting that photographs and feels distinctly Halloween without any effort. Individual homeowners in the historic district take Halloween seriously, with elaborate porch scenes and full-yard installations that turn walking neighborhoods into destinations. Trick-or-treat night draws families from across Horry County to walk the historic district. Downtown merchants, restaurants, community groups, and CCU all contribute to a broader seasonal ecosystem. Different Conway neighborhoods approach the season with different intensities, but the historic district remains the epicenter. October weather cooperates in ways that make outdoor evening walking exactly what Halloween is supposed to feel like. What makes Conway's version different is the authentic community engagement — locals participate because they want to, not because marketing committees organized it. If you haven't experienced Conway in October, consider making the trip. Come at least twice, come during the week if you can, wear comfortable shoes, and take the time to talk to the people who make the season what it is. This is small-town America doing what small-town America is supposed to do, and it's worth seeing while it's happening.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in Lifestyle
Sept. 28, 2026

How to Time Your Home Sale With Buying Your Next One

You need to sell your current home and buy the next one. Simple in theory. Genuinely stressful in practice. Get the timing wrong and you're either homeless for a stretch or carrying two mortgages while your first home sits. Whether your next home is somewhere in Longs real estate, in a more rural pocket, or in a different city entirely, the sequencing you choose has real financial and emotional consequences. Here's how to actually think through the timing.

The Three Sequencing Options

You have three main approaches. Each carries different risks and benefits.

Sell first, then buy. You list your current home, close on the sale, and either move into temporary housing or rent while you shop for the next one. Financially safest option — you know exactly what proceeds you have to work with. Emotionally harder because of the intermediate move.

Buy first, then sell. You close on the new home before selling the current one. You bridge with savings, a bridge loan, or a HELOC on the current home. Emotionally easier because you avoid the intermediate move. Financially riskier because you're carrying two properties until the first sells.

Simultaneous close. You try to close on both properties on the same day or within days of each other. Coordinated smoothly, this eliminates the double-carry problem and the intermediate move. In practice, aligning two independent transactions to the same day is harder than it sounds.

When Sell-First Makes Sense

Sell-first is usually the right choice when:

You need the proceeds from your current home to fund the down payment on the next. This is by far the most common scenario for most sellers.

The market is soft or shifting and holding two homes for months would be financially painful.

You have flexibility on where you land — temporary housing options exist that would work.

Your current home might take longer than average to sell and you can't carry two properties through that uncertainty.

You'd prefer to shop your next home with cash certainty rather than pending-sale contingencies.

When Buy-First Makes Sense

Buy-first is usually the right choice when:

You have significant savings or equity to bridge the gap without financial stress.

You've identified a specific next home that won't wait for your current one to sell.

The market is hot and finding your next home is harder than selling your current one.

Your family situation (kids in school, work commitments, elderly parents) makes an intermediate move genuinely disruptive.

You've done the math on carrying costs and know you can afford several months of double-carry if needed.

How to Time Your Home Sale With Buying Your Next OneThe Contingency Approaches

Some buyers try to solve the timing problem through contract contingencies. A home-sale contingency in your purchase offer says you'll only close on the new home if your current one sells first.

Reality check. In competitive markets, sellers rarely accept home-sale contingencies. Your offer gets skipped in favor of contingency-free alternatives. In slower markets, home-sale contingencies work better but the timing is still uncertain — the sellers can accept your offer but often add a kick-out clause that lets them accept a better offer if you don't close by a specific date.

Home-sale contingencies work in specific market conditions but shouldn't be your primary strategy for aligning transactions.

Bridge Financing Options

If buy-first is your path, understand the financing options.

Bridge loans. Short-term loans (typically 6-12 months) that let you use your current home's equity to fund the new purchase. Interest rates are typically higher than standard mortgages. You pay them off when your current home sells.

HELOC on current home. If you have equity, a home equity line of credit accessed before you list can fund your next home's down payment. Cheaper than bridge loans but requires the HELOC to be in place before listing.

Recasting or refinancing after your current home sells. Some buyers close on the next home with a larger loan or higher down payment, then recast or refinance once the current home sells and proceeds arrive.

Cash. If you have enough saved, buying with cash and refinancing later once the current home sells sometimes provides the most flexibility.

Talk to a lender who does construction and bridge lending — they typically handle these scenarios better than standard residential lenders.

The Timeline Reality Nobody Fully Appreciates

Coordinating two transactions is hard because each has its own timeline.

Your sale timeline: prep for listing (2-4 weeks), on market until under contract (variable, from days to months), inspection and due diligence (2-3 weeks), financing period (30-45 days), closing.

Your purchase timeline: shopping for the right home (variable), offer negotiation (days to weeks), inspection and due diligence (2-3 weeks), financing period (30-45 days), closing.

Even if both transactions run smoothly, coordinating them within days of each other requires either luck or explicit contract terms that build in flexibility. Sellers who assume alignment will happen naturally often watch it not happen.

The Emotional Cost of Different Approaches

Financial math isn't the only factor. Emotional and family costs matter too.

Sell-first with an intermediate move means packing and unpacking twice. Coordinating temporary housing. Living out of boxes for weeks or months. Real disruption for families with kids in school.

Buy-first with double-carry means financial stress for however long it takes to sell. Watching your first home sit on market. Making mortgage payments on a property you no longer live in.

Simultaneous close attempts often fail and revert to one of the other approaches, but under time pressure that adds emotional cost.

Understand which cost you can better absorb — financial stress or logistical disruption. That answer often decides the right approach.

Where Your Next Home Matters

Different destination markets change the timing math.

If your next home is in a competitive market like Carolina Forest real estate, home-sale contingencies rarely work and buy-first with bridge financing may be necessary.

If your next home is in a slower market like Aynor real estate or Loris real estate, home-sale contingencies work better and sellers are often more flexible on timing.

If your next home is in a new construction community with a build timeline, you often have natural flexibility to sell your current home while the new home is under construction.

If you're moving out of state entirely, the coordination becomes harder because you can't easily commute between properties during the transition.

Two Things I Tell Every Seller Timing a Sale With a Purchase

First, get pre-approved for the buy-first path before you list. Even if you plan to sell first, having the bridge financing option pre-approved gives you flexibility if the right next home appears mid-sale. Many sellers discover the perfect next home while their current home is under contract, and the ones who prepared in advance can act while the ones who didn't watch the opportunity pass.

Second, discuss the timing plan with your listing agent before signing the listing agreement. A great agent helps coordinate closings, negotiate flexible contract terms, and manage the logistical challenges. An agent who just wants the listing without the coordination expertise creates problems later. Ask specifically how they've handled sell-and-buy scenarios and whether they'll actively help align your transactions.

Key Takeaways

Timing your home sale with buying your next one comes down to choosing between sell-first, buy-first, or simultaneous close — each carrying different financial and emotional trade-offs. Sell-first is financially safest and usually the right choice when you need proceeds for the down payment or the market is soft. Buy-first works when you have bridge capital, need to secure a specific next home, or family logistics make an intermediate move genuinely disruptive. Simultaneous close sounds appealing but is harder to execute than it looks. Home-sale contingencies work in specific market conditions but rarely in competitive markets. Bridge loans, HELOCs, cash, and recasting are the main financing paths for buy-first sellers. Timeline coordination requires either luck or explicit contract terms with flexibility built in. The emotional cost of different approaches — logistical disruption versus financial stress — often decides the right path as much as the math does. Your next home's market conditions matter too — competitive markets favor buy-first with financing, slower markets accommodate home-sale contingencies. The sellers who navigate this best get pre-approved for buy-first before listing, discuss the timing plan with their agent explicitly, and match the approach to their specific financial and emotional situation.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 25, 2026

Waccamaw River Neighborhoods Worth a Closer Look

The Waccamaw River threads through the back of Conway and shapes a specific slice of the local housing market. Buyers who want water proximity but not coastal-tourist intensity often end up walking properties along or near the river. Here's what most buyers miss. The Waccamaw corridor isn't one uniform market — it's a series of distinct neighborhoods, each with its own character, its own flood profile, and its own trade-offs. Whether you're chasing true river frontage in Conway riverfront homes or a quieter river-adjacent option, here's the honest map.  

Waccamaw River Neighborhoods Worth a Closer Look

What the Waccamaw Actually Delivers as a Housing Feature

Understand what you're actually getting when you buy near this river. The Waccamaw is a blackwater river — dark, slow-moving, tannin-stained, lined with cypress trees. It supports kayaking, small-boat cruising, fishing, and paddleboarding, but it's not a working navigable channel like the Intracoastal. Water levels rise and fall meaningfully with rainfall.

Living near the Waccamaw means quiet water, wildlife views, and a specific aesthetic that most coastal SC housing doesn't offer. It also means dealing with flood zones, insurance layers, and the specific maintenance realities of homes near freshwater.

Cat Tail Bay for Waccamaw-Adjacent Character

Cat Tail Bay offers a distinctive natural setting that leverages the surrounding Waccamaw ecosystem. Water features, wildlife presence, tree cover, and lot depth combine to create a residential experience that feels genuinely rural despite being close to Conway proper.

Who fits: buyers who value natural setting over standard subdivision feel, retirees who enjoy the water and wildlife, families with kids who'll actually use the outdoors.

Beach Gardens for Established Residential Feel

Beach Gardens sits in a settled Conway pocket with real neighborhood identity. Mature landscaping, established neighbor relationships, and the kind of community feel that pure new subdivisions can't manufacture yet. Not directly on the river for most homes, but part of the Waccamaw-adjacent lifestyle that draws buyers to this side of Conway.

Pottery Landing for Distinctive Character

Pottery Landing gets less marketing attention than some of the more prominent Conway pockets, but the character of the homes and lots stands out from typical suburban builder inventory. Deeper lots, more architectural variety, and a location that feels connected to the river system without necessarily being oceanfront.

Conway Plantation for Established Community

Conway Plantation represents another Waccamaw-corridor option that combines established community feel with proximity to the river system. Buyers who want the neighborhood identity of a mature development alongside the natural setting of the Waccamaw area often land here.

The Direct Riverfront Category

Not every Waccamaw home is directly on the water. True riverfront properties — homes with actual frontage on the Waccamaw or its tributaries — form their own category with premium pricing and specific due diligence needs.

What to verify on true riverfront:

  • Elevation certificate and flood zone status (most true riverfront sits in AE zones)
  • Dock permits and whether an existing dock conveys
  • Water access practicality — some frontage supports boats, some only kayaks
  • Erosion patterns along the bank over time
  • Flood insurance costs specifically for the property
  • Historic flooding at the address, particularly from major events like Hurricane Florence

The Conway riverfront homes inventory captures most of the true-frontage options. Buyers should tour multiple frontage types before committing to a specific parcel.

Historic Downtown Conway's River Connection

Downtown Conway sits along the Waccamaw and the historic district's Riverwalk connects the neighborhood directly to the water. This isn't riverfront ownership in the traditional sense — most historic district homes don't have direct water frontage — but daily walks, community events, and the general lifestyle here are shaped by the river's presence.

Retirees, remote workers, and families who value walkable urban-adjacent living without leaving the river's influence often prefer historic Conway to specific waterfront communities.

Insurance and Flood Zone Realities Across the Corridor

Waccamaw-area insurance varies significantly by exact address.

True riverfront in AE or A flood zones requires flood insurance and typically carries higher premiums. Elevation certificates matter significantly.

Waccamaw-adjacent homes a block or two off the water often sit in Zone X with standard insurance. The dividing lines can be surprising — verify by exact address.

Historic downtown Conway homes have varied flood zone designations depending on specific street elevation.

Local flood history matters. The 2015 flood and Hurricane Florence in 2018 affected different pockets differently. Ask about specific historic impact on the property.

The Lifestyle Fit Question

Waccamaw-area living suits specific buyer types.

Nature-oriented buyers who value wildlife, quiet water, and tree cover over resort intensity.

Retirees who want river views, walkable community engagement (particularly in the historic district), and a slower daily rhythm.

Remote workers with home offices who benefit from a genuinely peaceful setting.

Families with kids who'll use the outdoors — kayaking, fishing, exploring — as part of daily life.

Boaters with smaller boats designed for river cruising rather than ocean use.

Buyers who need daily beach access, tourist-corridor retail depth, or resort-style amenities usually don't find their fit here. That's not a criticism of the corridor — it's just a different housing product than coastal-strip alternatives.

What Waccamaw Buyers Underestimate

Two patterns.

Mosquitoes and bugs during peak summer. Freshwater environments support more insect life than the salt-air coast. This shapes outdoor use patterns in ways buyers who visit only in spring or fall don't fully appreciate. Screened porches, insect control, and yard design matter more here than in coastal neighborhoods.

Winter water levels versus summer water levels. The Waccamaw's flow varies significantly with rainfall. Buyers touring during dry periods may not appreciate what the same property looks like when the river runs high. Ask about historic water levels at the property before committing.

Two Things I Tell Every Buyer Considering the Waccamaw Corridor

First, visit the specific property in different seasons if you can. The Waccamaw looks and feels different in April versus August versus November. Buyers who see only one season sometimes discover surprises later. If you can only make one trip, prioritize a visit in late summer when the water is often high, the bugs are active, and the humidity is real. That's the version of the corridor you'll live with for months every year.

Second, verify the specific address's flood zone and elevation before falling in love with the home. The corridor has meaningful variation in flood risk within short distances. A home that looks similar to a neighbor's property can have completely different insurance implications based on FEMA zone assignment and finished floor elevation.

Key Takeaways

  • The Waccamaw River corridor is a series of distinct neighborhoods with different character, flood profiles, and lifestyle fits
  • Cat Tail Bay delivers natural setting with wildlife and water features integrated into the residential experience
  • Beach Gardens offers established residential feel with proximity to the Waccamaw-adjacent lifestyle
  • Pottery Landing provides distinctive character and deeper lots than typical suburban inventory
  • Conway Plantation combines mature community identity with river-corridor location
  • True riverfront homes require specific due diligence on elevation, dock permits, water access, erosion, insurance, and flood history
  • Historic downtown Conway offers Waccamaw lifestyle without traditional waterfront ownership
  • Insurance and flood zone status vary significantly by exact address across the corridor
  • The corridor works well for nature-oriented buyers, retirees, remote workers, active families, and river-boat owners
  • Verify seasonal water levels, mosquito realities, and flood zone by exact address before committing

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle
Sept. 24, 2026

What to Know About Buying a Foreclosure on the Grand Strand

You're shopping for value on the Grand Strand and someone told you foreclosures might be where the real deals are. Here's the honest picture. Foreclosures can deliver real value — but only for buyers who understand what they're actually getting into. Every year I watch a few buyers walk into Grand Strand foreclosures expecting Zillow-style discounts and walking out surprised by the complexity. Let me walk you through what a foreclosure purchase actually involves and whether it's the right path for you.

The Three Foreclosure Types You'll See

Not all foreclosures are the same. The specific stage of the process changes what you're buying.

Pre-foreclosure short sales. The current owner is behind on payments and the lender has agreed to accept less than the full loan balance. The owner still owns the home, but the sale requires lender approval. Timeline is slow — often three to six months from offer to closing — and the deal can fall apart at any stage.

Auction properties. Sold at courthouse steps or online auction to the highest bidder, typically for cash, often with no inspection contingency and sometimes without interior access. Highest risk, highest potential reward, and generally the domain of experienced investors rather than first-time foreclosure buyers.

REO (real estate owned) properties. The lender took the home back after auction and now owns it. Listed with a real estate agent, sold with a purchase contract, financeable through normal channels. Most manageable of the three foreclosure types for typical buyers.

Most buyers who ask about foreclosures actually want REO properties. That's usually the right answer for anyone new to the process.

What to Know About Buying a Foreclosure on the Grand Strand

What Foreclosure Buyers Actually Get

The discount versus market value varies significantly by property.

Some REO properties sell 10-20 percent below comparable market inventory because the lender wants to move the asset quickly and buyers know the home has been vacant.

Others sell close to market because the lender is patient, has multiple offers, and the property is in good condition.

Auction properties can occasionally sell far below market — 30-50 percent discounts happen — but the risk is proportionally higher and most auction wins go to experienced local investors.

The "great deal" foreclosure that shows up on national websites usually isn't real for retail buyers. The actual deals require patience, cash flexibility, and willingness to accept property condition issues.

The Condition Reality

Foreclosure properties are typically vacant for months. Sometimes years. That has consequences.

HVAC systems that haven't run consistently often need service or replacement. Air stagnates, humidity builds up, condenser coils corrode, refrigerant lines can fail.

Plumbing may have leaks that weren't caught while the home sat empty. Water damage, mold, and pest issues develop when nobody notices.

Landscaping deteriorates. Overgrown trees, dead plants, drainage issues that develop from lack of maintenance.

Interior issues from vacancy — musty smells, damaged flooring from moisture, pest infestations, sometimes damage from squatters or vandalism.

Systems damage from neglect — hot water heaters that failed while the home sat, roofs that developed leaks, HVAC units that seized.

Buyers who write foreclosure offers assuming the home is "mostly fine" usually find otherwise during inspection.

The Financing Considerations

Foreclosure financing works differently depending on the type.

REO properties can typically be financed through conventional, FHA, VA, or USDA loans if the home meets the loan program's condition requirements. FHA has specific property condition standards that many foreclosures fail. VA loans often work but the property must pass VA appraisal. Conventional loans have the most flexibility on condition.

Auction purchases usually require cash. Some auctions allow financing, but the tight closing timelines (often 30 days) make traditional lending challenging.

Short sales work with standard financing but the timeline is unpredictable.

Buyers who need financing should focus on REO inventory with reasonable condition.

Where Foreclosure Inventory Sits

Grand Strand foreclosure inventory is not evenly distributed.

Older condos in aging beach-block buildings sometimes have concentrations of financially-stressed owners. Special assessments, insurance climbs, and aging demographics can trigger foreclosure clusters.

Some inland subdivisions built at the top of the last cycle occasionally show foreclosure inventory when specific developments face economic pressure.

Rural properties with well and septic complications sometimes end up in foreclosure after owners face expensive system replacements they can't afford.

Vacation rental units that stopped producing after regulation changes or building special assessments sometimes cycle into distressed status.

The foreclosures inventory page is worth watching if you're serious about this segment, alongside broader inventory in Conway real estate to understand relative pricing.

What Foreclosure Buyers Should Verify

Beyond normal due diligence, foreclosure buyers should specifically confirm.

Title status. Foreclosures sometimes have title complications — outstanding liens, contested ownership, HOA arrears. A thorough title search is non-negotiable.

HOA arrears if applicable. Some foreclosures come with unpaid HOA dues that transfer to the new owner. Verify before committing.

Property tax status. Delinquent property taxes need to be resolved before or at closing.

Physical condition through inspection, even when the seller sells "as-is." As-is doesn't mean you can't investigate — it means the seller won't negotiate repairs.

Utility status. Some vacant homes have had utilities disconnected for extended periods. Reconnection and testing costs matter.

Insurance eligibility. Some foreclosed coastal homes have coverage complications. Get a real quote before committing.

The Opportunity Cost Question

Foreclosure buying takes time, patience, and specific expertise. Compare that against alternative buying paths.

Standard resale inventory in bands like Conway homes under $300,000 or Myrtle Beach homes between $250,000 and $500,000 often offers similar entry prices with far less complexity and better condition.

New construction with builder incentives sometimes delivers effective discounts through rate buydowns and closing credits that foreclosure buyers can't access.

The foreclosure path makes the most sense for investors with cash, buyers with real renovation ability, or buyers targeting very specific value opportunities. For most typical buyers, standard inventory is usually the better path.

Two Things I Tell Every Foreclosure Buyer

First, work with an agent who has specific foreclosure experience. Foreclosure transactions have specific paperwork, timelines, and complications that general residential agents may not handle well. The agent's experience with the specific bank or asset manager also matters — some lenders are easier to work with than others.

Second, budget for the surprises. Foreclosure buyers who plan for a 20 percent discount often end up spending that entire discount on unforeseen repairs. The buyers who do well plan for at least 15-25 percent of purchase price in post-closing renovations and system replacements. If the numbers still work with that assumption, the deal probably makes sense. If they don't, the "great deal" isn't actually great.

Key Takeaways

Foreclosure buying on the Grand Strand can deliver real value but requires understanding what you're actually getting into. The three foreclosure types — pre-foreclosure short sales, auction properties, and REO — carry different timelines, risks, and financing implications, with REO being the most accessible for typical buyers. The discount versus market varies significantly by property, and the great-deal narrative doesn't reflect the retail buyer experience. Property condition from extended vacancy is the biggest single risk — HVAC issues, plumbing problems, pest infestations, and system neglect are common. Financing works for REO properties meeting loan program condition standards but is harder for auction purchases. Foreclosure inventory concentrates in specific segments — aging condos with special assessment pressure, over-built subdivisions from the last cycle, rural properties with system issues, and vacation rentals affected by regulation changes. Buyers should verify title status, HOA arrears, tax status, physical condition, utility status, and insurance eligibility beyond normal due diligence. For most typical buyers, standard resale or new construction with builder incentives delivers similar entry prices with far less complexity than the foreclosure path. Foreclosures make the most sense for investors, buyers with renovation ability, or buyers targeting specific value opportunities.

Frequently Asked Questions

Can I get an inspection on a foreclosure property?

Almost always yes on REO properties. Auction properties typically don't allow inspection before bidding. Short sales usually allow inspection but the timeline is longer. Never buy without inspection unless you have specific expertise in evaluating property condition without one.

How much can I actually save buying a foreclosure?

Realistic REO discounts on the Grand Strand run 5-20 percent below market for comparable properties in good condition. The wider discounts you'll see in headlines usually reflect properties with major condition issues that offset the price discount.

Do I need cash to buy a foreclosure?

Not for REO properties, which can be financed through conventional, FHA, VA, or USDA loans if the property meets condition requirements. Auction purchases typically require cash. Short sales work with standard financing.

What's the biggest mistake foreclosure buyers make?

Underestimating post-closing repair costs. Buyers who focus on the purchase-price discount without accounting for condition issues often spend the discount and more on renovations. Budget realistically for repairs before committing.

How long does a foreclosure purchase take from offer to closing?

REO purchases typically close in 30-60 days depending on the lender and financing type. Short sales often take 3-6 months due to lender approval processes. Auction purchases close in 30 days or less, usually with cash.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 23, 2026

Comparing North Myrtle Beach Condo Buildings for Investment or Retirement

You're shopping condos on the north end of the Grand Strand and quickly realizing that "North Myrtle Beach condo" covers wildly different products at wildly different price points. Here's how to actually compare them. Whether you're buying to retire, to rent out, or as a second home you'll use part of the year, the differences between buildings matter far more than the marketing suggests. Complexes like Coquina Harbour Condos feel completely different than direct oceanfront resort towers even though they're a short drive apart.

The Four Condo Categories You'll Encounter

North Myrtle Beach condo inventory splits into a few distinct buckets.

  • Direct oceanfront resort condos. High-rise buildings on Ocean Boulevard with hotel-like amenities, front desk service, rental infrastructure, and premium pricing. Vacation-rental focused.
  • Ocean-block low-rise condos. Smaller buildings a block or two from the ocean, mix of rental and full-time ownership, more residential feel than the towers.
  • Marina and Intracoastal Waterway condos. Water-facing but not oceanfront, boat access, working-harbor character.
  • Inland golf and amenity community condos. Communities like Barefoot Resort with amenity access at lower entry prices, further from the actual sand.

Each category serves a different buyer. Sort which one fits before comparing specific buildings.

Comparing North Myrtle Beach Condo Buildings for Investment or Retirement

Direct Oceanfront Resort Condos

These are the buildings most out-of-state buyers picture when they imagine "Myrtle Beach condo." Hotel-style operations, elevators, pools, lobby services, rental programs. Prices depend heavily on view (direct oceanfront versus side view versus city view), floor, and building age.

Who fits: buyers who want vacation-rental income, buyers who'll use the property a few weeks a year and rent the rest, and buyers who value hands-off management.

What to verify: HOA reserve health (older resort buildings often carry special assessment risk), rental program economics (on-site programs typically take 40-60 percent commission), master insurance coverage versus your HO-6 responsibility, and any pending capital projects.

Ocean-Block Low-Rise Condos

Smaller buildings one to three blocks from the ocean have a distinctly different feel. Less resort intensity, more residential character, mix of full-time and part-time owners. Many are in neighborhoods like Cherry Grove or the Ocean Drive corridor.

Who fits: buyers who want beach proximity without hotel-style building operations, buyers who plan to live there part-time or full-time, retirees who value walkability over amenity intensity.

What to verify: rental rules if you'll rent occasionally, parking arrangements (limited in some pockets), flood zone status, and building age since many of these are older stock.

Marina and Intracoastal Waterway Condos

The character shifts significantly when you move to marina-community condos. Working harbor feel, actual boat access, less tourist intensity, different buyer demographics. Coquina Harbour delivers the working-harbor version. Cypress Bay Condos offers a more affordable entry into the marina lifestyle. Gardens at Cypress Bay Condos serves a specific quieter niche within the same general area.

Who fits: boaters, retirees who want water access without oceanfront pricing, buyers who value the working-harbor character.

What to verify: dock and slip arrangements (some convey with the unit, some are separate), water depth at low tide if you own a boat, HOA rules on rental if applicable, and specific building maintenance history for marina-adjacent construction that faces salt and water exposure.

Inland Amenity Community Condos

Complexes in Barefoot Resort and similar inland amenity-community developments offer resort-scale amenities at price points below beach-block alternatives. Golf, pools, community facilities, sometimes gated entry.

Who fits: buyers who value amenity depth over daily beach proximity, snowbirds who use the amenities more than the ocean, buyers who want gated community feel.

What to verify: which amenities are actually included in the HOA versus fee-based, community financial health, and the realistic use pattern for you (some amenities that look great in the brochure get used weekly by residents; others sit).

What Matters More Than Location

Location is what first-time condo buyers focus on. Experienced condo buyers focus on the building itself.

  • Reserve funding percentage. Well-funded reserves mean special assessments are less likely.
  • Meeting minutes from the last two years. Reveal what the community is actually dealing with day to day.
  • Rental restrictions. Can you rent short-term, long-term, or not at all? Matters even if you don't plan to rent.
  • Owner-occupancy ratio. Affects both community feel and conventional financing eligibility.
  • Master insurance coverage details. What's covered by the building policy versus your unit policy.
  • Assessment history over the last 5-10 years. Patterns predict future assessments.

Buyers who evaluate the building itself consistently outperform buyers who fell for the unit's finishes without checking the fundamentals.

Financial Realities Investors Should Consider

Investor buyers need to layer additional analysis.

Property tax at 6 percent non-primary residence rate versus 4 percent primary. On a $400,000 unit this difference alone runs into thousands per year.

Rental program commission versus independent management. On-site programs take 40-60 percent of gross for hands-off operation. Independent management runs 20-30 percent but requires more owner involvement.

Insurance layered coverage. Coastal wind and hail plus flood if applicable adds meaningfully to monthly carrying costs.

Realistic rental income versus marketing claims. Get actual rental history for the specific unit, not building-wide averages.

Special assessment probability given reserve position and building age. Investors who don't account for this often see returns evaporate mid-hold.

What Retiree Buyers Should Consider Differently

Retirees have a different set of priorities.

Age-in-place features. Elevator access, unit layout, and building accessibility all matter over 20 years of ownership.

HOA financial predictability. Fixed incomes don't easily absorb surprise special assessments.

Community demographic mix. Some buildings skew heavily retiree; others are mostly vacation renters. Match to how you want to live.

Actual daily-life amenities within reach. Grocery, healthcare, restaurants, community activities.

For broader Little River-area inventory context, browse Little River real estate alongside the specific building comparisons.

Two Things I Tell Every NMB Condo Buyer

First, tour multiple building categories before committing to one. Direct oceanfront feels different than ocean-block low-rise, which feels different than a marina condo, which feels different than an inland amenity community. Buyers who commit to one category without seeing others sometimes wish they'd known other options existed.

Second, read the HOA documents like you mean it. Reserve study, last two years of meeting minutes, master insurance policy, rental rules, and assessment history. The buildings where these documents raise concerns are the buildings where ownership becomes painful. Better to find out during the inspection period than in year three.

Key Takeaways

  • NMB condo inventory splits into direct oceanfront resort, ocean-block low-rise, marina/ICW, and inland amenity community categories — each serves different buyers
  • Direct oceanfront resort condos work for vacation-rental focus and hands-off management, with special assessment risk to verify
  • Ocean-block low-rise offers residential feel with beach proximity, better fit for full-time or serious part-time owners
  • Marina and ICW condos (Coquina Harbour, Cypress Bay, Gardens at Cypress Bay) serve boaters and buyers wanting water without oceanfront pricing
  • Inland amenity community condos deliver resort-scale amenity access at lower entry prices, further from the sand
  • The building itself matters more than the unit finishes — verify reserves, meeting minutes, rental rules, owner-occupancy ratio, master insurance, and assessment history
  • Investors should layer property tax at 6 percent, rental program economics, layered insurance, actual unit rental history, and assessment probability
  • Retirees should prioritize age-in-place features, HOA financial predictability, demographic mix, and daily-life amenities
  • Tour multiple building categories before committing and read HOA documents seriously

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 22, 2026

How to Choose the Right Listing Agent in South Carolina

You're getting ready to sell and now three agents want to sit down with you. Each one has a listing pitch. Each one has a suggested price. Each one has reasons you should pick them. Here's the honest reality. The listing agent you choose has more impact on your net proceeds than almost any other decision in the selling process, and the "wrong" agent doesn't announce themselves — they usually seem fine until the deal goes sideways. Whether you're listing something in the mid-tier band or a home priced within Conway homes over $1,000,000, the framework for picking the right agent is the same.

The Wrong Reasons Sellers Pick Agents

Most sellers pick their listing agent for reasons that don't correlate with a successful sale. The three most common bad reasons.

Highest suggested list price. Some agents inflate the price to win the listing, planning to push for cuts later. Sellers who fall for this end up disappointed when the market disagrees.

Lowest commission. Agents willing to cut their commission usually cut services too. The savings on paper often costs you more in actual sale price than you save on commission.

Personal relationship. Friends and family are often the wrong choice. They may be great agents. They may not be. Test them the same way you'd test any other option before committing.

The Right Reasons to Pick an Agent

Look for these instead.

Track record in your specific market segment. An agent who sells oceanfront condos every week understands that market. An agent who mostly does inland resale might not. Match the agent to your specific home type and price band.

Marketing capability that actually reaches buyers. Photography quality, video, online distribution, professional staging relationships, and buyer network all matter. Ask to see recent listings and evaluate the presentation quality.

Communication style that matches yours. Some agents overcommunicate. Some undercommunicate. Neither is universally wrong, but the mismatch between your preferences and their style causes real friction during the transaction.

Negotiation experience with the kind of buyers who'll show up. If your home appeals to out-of-state relocators, your agent should have real experience handling remote buyers. If your home is investor-oriented, they should know how investor buyers actually behave.

Team infrastructure. Some solo agents deliver exceptional service. Others get overloaded when things get busy. Team-based operations offer coverage but sometimes at the cost of personal attention. Understand which you're actually getting.

Questions That Reveal an Agent's Real Approach

Ask these in your listing consultation.

Walk me through your last three transactions. Not just successes — the ones that were hard. How did you handle the inspection response? The appraisal issue? The financing problem? Real answers reveal real experience.

Show me your CMA. Not the price recommendation. The actual comparable sold homes you used. If they can't justify the number with specific comparables, the number is suspect.

What's your specific marketing plan for my home? Not the generic marketing brochure — the specific plan for this property. Photography, video, launch strategy, open house schedule, buyer targeting, price reduction contingency if the initial approach doesn't work.

How do you handle multiple offers? What's your process for structuring highest-and-best? How do you evaluate offer quality beyond just price? Their answer tells you how negotiation will go.

What's your average days on market for homes in my price band and neighborhood? The honest answer separates agents who close deals from agents who accumulate stale listings.

How often will I hear from you and how? Not vague reassurances — specific commitments about communication frequency and channel.

The Red Flags to Watch For

Some patterns should make you keep looking.

Pressure to sign the listing agreement immediately. Good agents want you to make an informed decision. Pressure tactics usually mean the agent is worried about losing you to a better option.

Guaranteed sale price or guaranteed timeline claims. The market determines these, not the agent. Anyone promising specific outcomes is either naive or dishonest.

Weak online presence for their own listings. If their current listings have bad photos or thin descriptions, yours will too.

Discomfort with hard questions. If they get defensive when you ask about their track record, communication style, or negotiation approach, imagine how they'll handle buyer pushback.

Reluctance to explain their commission structure. You should know exactly what you're paying for and what services you're receiving.

 How to Choose the Right Listing Agent in South Carolina

The Coastal SC Considerations

The Grand Strand has some specific dynamics that raise the bar on agent selection.

Coastal insurance knowledge. Your agent should understand the layered SC insurance system — homeowner's, wind and hail, flood — and how it affects buyer decisions and negotiation. Agents who don't understand this often lose deals during buyer due diligence.

Out-of-state buyer experience. A meaningful share of Grand Strand buyers come from the Northeast, Midwest, and increasingly Florida. Handling remote buyers, virtual tours, and long-distance negotiation requires specific experience.

Vacation rental market understanding if your home has income potential. Agents who don't understand STR economics undersell homes that could command investor premiums.

Segment specialization. A luxury home in Conway homes between $500,000 and $1,000,000 requires different marketing than an entry-level condo in Myrtle Beach real estate. Match the agent's actual segment expertise to your specific home.

The Team Versus Solo Question

Team-based operations offer specific advantages — coverage during vacations, specialized roles (buyer's agents, transaction coordinators, marketing specialists), and often more consistent marketing quality. The trade-off is that you may work with several team members rather than one primary contact.

Solo agents offer direct communication and personal accountability. The trade-off is single-point-of-failure risk and sometimes slower response during busy periods.

Neither is universally better. Match the structure to your preferences and your specific transaction complexity.

What Sellers Get Wrong at This Stage

Two patterns.

Interviewing only one agent. Sellers who commit to the first agent they meet lose the ability to compare approaches, marketing plans, and communication styles. Interview at least two, ideally three.

Not checking references. Ask each agent for three recent seller clients you can call. Talk to them. Ask about the experience honestly. Some of the most useful information about an agent comes from clients who've been through the full process.

Two Things I Tell Every Seller Choosing an Agent

First, hire the agent who understands your market segment specifically. Grand Strand generalists exist. So do specialists in oceanfront condos, golf communities like Conway Country Club, historic homes, or investor-focused properties. The specialist consistently outperforms the generalist for their specific segment.

Second, trust your instincts about communication and trust. You'll spend 30-90 days working closely with this agent through emotionally charged decisions. If something feels off during the interview, it'll feel worse during negotiations. Pick someone you'd genuinely want representing you in a hard moment.

Key Takeaways

The right listing agent affects your net proceeds more than almost any other decision in the selling process. Avoid the common wrong reasons — highest suggested list price, lowest commission, personal relationship without vetting. Pick based on track record in your specific segment, marketing capability, communication style match, negotiation experience with your likely buyer type, and appropriate team infrastructure. Ask specific questions about recent hard transactions, CMA methodology, marketing plans, multiple-offer handling, days-on-market averages, and communication commitments. Watch for red flags including pressure tactics, guaranteed outcomes, weak online presence, defensiveness about questions, or reluctance to explain commission structure. Coastal SC has specific considerations — insurance knowledge, out-of-state buyer experience, vacation rental expertise, and segment specialization. Interview at least two agents, check references from recent clients, and trust your instincts about communication and trust. The best agent isn't always the one with the biggest reputation or the highest suggested price — it's the one whose experience, marketing, and communication match what your specific home and your specific transaction actually need.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 21, 2026

The Best Grand Strand Retirement Pockets Under Half a Million

You're retiring in the next couple of years and looking at the Grand Strand seriously. The budget is real — under half a million — and you want to know where that actually gets you a good retirement home versus where you'll be squeezed into something you don't love. Here's the honest answer. The Grand Strand has multiple pockets that deliver quality retirement living under $500,000, and the trade-offs between them are meaningful. Whether you're looking at the value-tier band shown in Conway homes between $250,000 and $500,000 or exploring inland alternatives, here's the actual map of where retirees land well at this budget.

What Retirees Actually Get for Under $500k

Understand what your budget covers in this market. At under $500k on the Grand Strand, retirees typically choose between:

  • A newer or updated single-family home in an inland community with real amenities
  • An established resale single-family in a mature coastal-adjacent neighborhood
  • A newer condo in a resort or marina community with strong amenity access
  • An older beach-block condo or cottage in specific tourist-oriented pockets
  • A newer subdivision home with modest square footage in a growing area

The right choice depends on how you actually want to spend retirement — how much you value beach proximity, community amenities, size, age of construction, and future maintenance load.

Conway for Downtown Character and Value

Conway consistently delivers the best combination of value, character, and community for retiree buyers under $500k. Historic downtown offers walkable neighborhood retirement with real character. Newer subdivisions like Wild Wing Plantation, Carsens Ferry, and Astoria Park offer amenity communities at prices that stretch. The trade-off is 15-20 minutes to the beach, but retirees who don't need daily sand access often find the trade completely worth it.

Longs for Amenity Retirement Communities

Longs has become one of the strongest retirement pockets on the Grand Strand under $500k. Amenity-heavy communities like Heritage Park, The Park at Long Bay, and Colonial Charters combine active retirement social structure with price points that keep retirement math workable. Highway 31 puts you 15-20 minutes from North Myrtle Beach when you want the ocean. Insurance is friendlier than beach-block properties.

For broader inventory context, browse Longs real estate to see the specific communities and how they price against each other.

Little River for Waterfront-Adjacent Retirement

Little River sits at the top of the strand near the North Carolina line, and under-$500k retirement inventory here concentrates in the marina-community condos. Carolina Yacht Landing Condos and similar buildings deliver retirement lifestyles centered on the water at prices below what oceanfront alternatives require. If your retirement dream involves keeping a boat and being near the water year-round, this pocket is worth serious attention.

Loris for Rural Retirement Value

Not every retiree wants coastal proximity as the primary feature. Loris real estate offers rural retirement at prices that make the retirement math work with meaningful room to spare. Real acreage, real small-town character, and daily costs that run friendlier than any coastal option. The trade is a longer drive to specialty services, but retirees who value quiet and space consistently thrive here.

Pawleys Island Area for Coastal Character

Retirees with under $500k who want the more established, character-focused coastal lifestyle should look at Pawleys Island real estate. The area south of Murrells Inlet has a different feel than the resort strip — quieter, more residential, more established. Inventory at this price point is tighter than in Conway or Longs, but specific homes and condos do come available and reward patient buyers.

North Myrtle Beach for Occasional Beach-Adjacent Options

Under $500k in North Myrtle Beach doesn't get you an oceanfront home, but it can get you a condo with amenity access in an inland community or an older cottage in one of the residential pockets. Retirees who want the specific North Myrtle Beach lifestyle — golf cart culture, walkable Main Street, small-city feel — sometimes prioritize this even though the budget is stretched.

 The Best Grand Strand Retirement Pockets Under Half a Million

What Retirees Should Verify Anyway

Standard due diligence at any price point.

  • Age-in-place features. First-floor primary suite. Wide doorways. Low-threshold showers. Minimal steps. Even at 62, these matter for future ownership.
  • Total monthly carrying cost. Not just the mortgage. Property tax at the 4 percent primary residence rate, insurance, HOA, and reserves for maintenance and replacements.
  • Healthcare access. Primary care and specialists are best-served in Conway or Myrtle Beach corridors. Time your realistic drives to healthcare before committing.
  • HOA financial health if applicable. Special assessments hit retirees on fixed incomes hardest. Read reserve studies carefully.
  • Insurance quotes for the specific property. Coastal insurance runs meaningfully higher than inland; make sure the numbers work for your retirement budget.
  • Flood zone status. Some retiree-friendly beach-adjacent properties sit in AE zones with real insurance implications.

The Lifestyle Fit Question

Different retirement pockets suit different retirement lifestyles.

Active social retirement with amenity access and other retirees nearby: Longs amenity communities or Conway's Wild Wing Plantation.

Quieter retirement with real community feel and character: historic Conway, Loris, or Pawleys Island area.

Boating-centered retirement: Little River marina communities.

Beach-adjacent lifestyle for retirees who love the sand: North Myrtle Beach inland corridor.

Rural retirement with space and privacy: Loris, Aynor, or deeper rural pockets.

Match honestly. Retirees who buy the wrong lifestyle for their actual daily rhythm end up moving again within a few years. Retirees who match well stay 20+ years happily.

What Under-$500k Retirees Underestimate

Two patterns worth flagging.

The maintenance load on older properties. Under $500k in coastal SC sometimes means an older home with the maintenance calendar that comes with it. Roof, HVAC, systems age matters. Budget realistically for capital replacements over a 20-year retirement.

The insurance climb. Coastal SC insurance has been rising and shows no strong signs of reversing. Retirees on fixed incomes need to plan for premium increases over their ownership period, not just the current year's quote.

Two Things I Tell Every Retiree Buying Under $500k

First, don't stretch to the top of the budget on the home purchase. Leave buffer for the reality of retirement — healthcare surprises, family visits, travel you'll actually want to do, unexpected maintenance. Retirees who spend at 90-95 percent of budget on the home consistently regret it. Retirees who target 75-85 percent enjoy retirement more.

Second, prioritize the ability to age in place from the first purchase. Even if you plan to move again in 10 years, the ability to stay if plans change is worth real value. First-floor primary suite. Walk-in shower. Wide doorways. These features protect your future options.

Key Takeaways

  • Under $500k on the Grand Strand delivers real retirement options, with meaningful trade-offs between pockets
  • Conway offers the best value-and-character combination — historic downtown, Wild Wing Plantation, or newer subdivisions
  • Longs concentrates amenity retirement communities — Heritage Park, Long Bay area, Colonial Charters
  • Little River marina condos deliver waterfront retirement at friendlier prices than oceanfront alternatives
  • Loris offers rural retirement value with real acreage and small-town character
  • Pawleys Island area serves retirees who want established coastal character over resort intensity
  • North Myrtle Beach under $500k means condos or older cottages, not oceanfront single-family
  • Age-in-place features, total monthly carrying cost, healthcare access, HOA health, and insurance quotes matter more at retirement than they seem
  • Don't stretch to the top of the budget and prioritize age-in-place from the first purchase

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle
Sept. 18, 2026

How Snowbirds Should Prepare a Grand Strand Home for the Off-Season

You spend fall through spring on the Grand Strand and then head north for summer. Or your primary home is up north and you use your Grand Strand place from November through March. Either way, your home sits empty for months at a time — and how you prepare it before you leave determines whether you come back to a well-kept property or a mess of preventable problems. Whether your place sits in a marina community up in Little River or an inland Conway condo, the off-season prep pattern is the same. Here's what actually works.

Why Off-Season Prep Matters More on the Coast

Grand Strand summers are hard on unattended homes. High humidity, salt air, sudden thunderstorms, hurricane season from June through November, and the general wear of an empty coastal property all compound. A home that would sit quietly through summer in Pennsylvania will develop mold, HVAC issues, pest problems, or storm damage on the coast if left unprepared.

The prep isn't dramatic. It just has to be systematic.

The HVAC Setting Decision

The most important single decision is how you handle the HVAC while you're gone. Two approaches work.

Leave the system running with the thermostat set to 78-82 degrees. This keeps humidity down without running the compressor constantly. Most snowbirds who leave the system on for humidity control come back to homes without musty smells or mold issues.

Turn the system fully off. Some owners prefer this to save utility costs and reduce wear on the unit. It works only if humidity is otherwise controlled — usually through a dedicated dehumidifier — and only in specific home types. For most coastal homes, this is not the safer choice.

Have HVAC serviced before you leave. Fresh filter, coil cleaning, refrigerant check. A system starting the summer clean handles unattended operation better than one carrying accumulated grime.

The Water Shutoff and Plumbing Steps

Water damage from a burst pipe or slow leak is the single most expensive off-season disaster.

Shut off the main water supply before you leave. This is the single highest-impact step. If the water is off, a broken supply line can't flood the house.

Drain the toilet tanks and add a small amount of RV antifreeze if the home might see very cold weather. Rare on the coast but happens occasionally.

Consider adding a smart leak detector if you don't shut off the main. Systems like Moen Flo or Streamlabs alert you to leaks and can auto-shut off remotely. A few hundred dollars for real peace of mind.

Empty the ice maker and unplug it. Ice makers left running with no one to use the ice can create leak conditions over months.

The Refrigerator Question

Empty the refrigerator completely. Perishables, condiments, anything that could spoil. Leaving food inside for months creates smell and mold issues that persist even after you clean.

Some owners leave the fridge running with baking soda inside. Others turn it off entirely with the doors propped open. The unplug-and-prop-open approach saves energy and prevents mold if you're gone for 4+ months. The keep-it-running approach makes returning easier because you don't have to wait for the fridge to cool down before restocking.

Match your choice to how long you'll be gone and what you'll want when you return.

The Pest and Wildlife Prep

Empty homes attract pests. A few specific steps.

  • Deep clean before leaving. Crumbs, spills, and food residues invite ants, cockroaches, and rodents.
  • Empty and take out all trash and recycling. Don't leave anything organic behind.
  • Schedule pest control treatment before you leave and again shortly before you return. Coastal SC pest activity runs high in summer.
  • Check exterior openings for gaps that pests or wildlife could use to enter. Vents, chimney caps, screens, garage door seals. Seal what needs sealing.

How Snowbirds Should Prepare a Grand Strand Home for the Off-Season

The Storm Preparation

Peak hurricane season runs August through October. Snowbirds gone during those months should prepare their home before leaving.

Trim trees and shrubs near the house. Limbs that could hit the roof or windows in high wind should be cut back.

Confirm hurricane shutters or impact-rated windows are functional. Test the mechanisms. Replace any missing fasteners.

Bring in outdoor furniture, planters, and anything else that could become a projectile in high winds.

Confirm insurance is current. Homes in AE flood zones or coastal areas need active Conway property insurance-style layered coverage — homeowner's, wind and hail, and flood if applicable. A lapse during peak storm season would be devastating.

Establish a local emergency contact who can check on the home after a storm and coordinate any needed cleanup or emergency repairs.

The Property Management Question

Some snowbirds hire a property manager to check the home periodically during the off-season. Others rely on neighbors or friends. What works best depends on the specific home and community.

For condos in managed buildings like some up in North Myrtle Beach or in complexes in Cherry Grove, on-site management often covers basic checks as part of HOA services. Verify what's included versus what you need to arrange separately.

For single-family homes and condos without on-site management, a paid property manager typically runs $100-$300 per month for periodic visual checks, mail collection, and coordination if issues arise.

Neighbors and friends can work but often lack the systematic approach that catches small problems before they become big ones. Match the arrangement to your risk tolerance and the property's specific vulnerabilities.

The Documentation and Emergency Prep

Before you leave, make sure specific information is accessible to whoever might need it.

Emergency contacts — HVAC company, plumber, roofer, insurance agent, closest neighbor or property manager.

Utility account numbers for anyone who might need to authorize emergency service.

Insurance policy details and claim contact information.

Key location — spare key with a trusted local, or coded lockbox in a safe location.

Confirm your mail is either being forwarded or picked up periodically. Piled-up mail signals an empty house to anyone paying attention.

The Return Checklist

When you come back, work through the systems in order.

-Turn the water main back on slowly. Check for leaks at every fixture as pressure builds. Small problems caught immediately are much cheaper than problems discovered after they've caused damage.

-Check the HVAC. Run it for a couple of hours before you settle in. Any strange sounds or smells indicate service is needed.

-Look at the exterior thoroughly. Signs of storm damage, pest activity, or drainage issues that developed while you were gone.

-Restock the refrigerator, review the pantry for anything expired, and do a light deep clean to reset the home to daily-use condition.

For broader lock-and-leave-friendly inventory if you're considering the snowbird lifestyle but haven't bought yet, Conway condos for sale often work well for exactly this ownership pattern.

Two Things I Tell Every Snowbird About Off-Season Prep

First, build a written checklist for your specific home. Every property has its own quirks — a specific window that leaks, a garage door that sticks, a sump pump that needs attention. A written checklist you follow every time you leave prevents forgotten steps and eliminates the "did I do that" anxiety after you've left.

Second, invest in remote monitoring where it makes sense. Smart thermostats, leak detectors, security cameras, and door sensors let you see how the home is doing from wherever you are. The peace of mind alone is worth the small investment, and catching problems early has real financial value.

Key Takeaways

Grand Strand snowbird home prep follows a systematic pattern that prevents most off-season disasters. HVAC set for humidity control at 78-82 degrees is the single biggest decision affecting how the home does while you're gone. Shutting off the water main and empty the refrigerator eliminate the two most common water and pest problems. Storm preparation before peak hurricane season protects against Atlantic weather events. Property management arrangements for periodic checks catch developing issues before they become emergencies. Insurance must remain current through the entire off-season. Documentation of emergency contacts and key locations helps trusted locals help you if something happens. Written checklists specific to your home eliminate forgotten steps and remote monitoring technology extends your visibility from wherever you are. Snowbirds who prep systematically consistently return to homes in good condition. Snowbirds who wing it often find surprises that cost real money and disrupt the return. The prep isn't complicated, but it has to be done every time you leave.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 17, 2026

What to Know Before Buying Land to Build Near Conway

You've decided you want to build rather than buy an existing home, and now you're shopping land near Conway. Here's the honest reality. Buying land to build is one of the most rewarding real estate paths in this market and one of the most likely to go wrong if you don't know what to look for. Whether you're looking at pure land inventory in Longs land for sale or considering acreage further inland toward Aynor and Loris, the specific due diligence you do before writing an offer determines whether the build works out or turns into a years-long headache.

The Question to Answer Before You Look at Lots

Before you fall in love with a specific parcel, answer this. What are you actually going to build? Custom home. Modular. Manufactured. Small dwelling with future expansion. The answer changes which lots make sense and which don't. A lot that supports a custom stick-built home may not accommodate a manufactured home under community rules. A lot with tight tree cover may need meaningful clearing for the home footprint you have in mind.

Buyers who shop land without a clear vision for what goes on it often buy the wrong parcel.

The Utilities Question That Determines Feasibility

Utility access is the single biggest variable on rural Horry County land.

  • Power. How far to the nearest power line? A few hundred feet is manageable. A quarter mile can cost $20,000 to $40,000 to run service.
  • Water. Well or connection to municipal water? Most rural Conway-area land requires a well. Well drilling costs $8,000 to $25,000 depending on depth and quality.
  • Septic. Perc test results determine what kind of system will work. Soil that percs well supports a conventional gravity system for around $8,000 to $15,000. Poor-percing soil requires an aerobic system at $15,000 to $25,000, or may not be buildable at all.
  • Internet. Fiber has expanded but coverage on rural addresses varies. If you'll work from home, verify by exact address before committing.
  • Natural gas. Rarely available on rural Horry County parcels. Plan for electric or propane.

The Zoning and Building Rules That Shape the Project

Different jurisdictions handle building differently.

Horry County unincorporated areas have specific setback, height, and lot coverage rules that vary by zoning classification. Some parcels allow accessory dwellings, workshops, or livestock. Others don't.

Municipal areas within Conway proper have city building codes plus stricter design guidelines in some neighborhoods.

Communities within HOA-governed subdivisions add architectural review, minimum square footage requirements, exterior material rules, and sometimes builder approval requirements. If you're buying inside an HOA-governed community with a lot for future build, read the covenants carefully — some restrict the build significantly.

Rural communities like those around Aynor and Loris generally have more flexible building rules than tight subdivisions closer to Conway proper.

The Perc Test That Makes or Breaks the Deal

The single most important pre-purchase test on any Horry County land is the percolation test. It tells you whether the soil supports a septic system and what kind. Without a passing perc, you can't build a home on the parcel unless municipal sewer is available.

What buyers should know:

  • Perc tests are done by SCDHEC or a licensed contractor
  • Results can vary by season — wet-season tests are more conservative
  • Some parcels have historic perc results on file; others require new testing
  • If the perc fails or comes back marginal, negotiate a contingency into your purchase contract or walk away

Never buy land intended for a home build without a satisfactory perc test in hand.

The Flood Zone and Drainage Reality

Rural Horry County has real flood zone exposure in specific pockets, particularly parcels near the Waccamaw River, tributaries, and low-lying areas.

Check the FEMA flood zone designation before committing. AE or A zones affect insurance, financing, and building elevation requirements. Some low-lying land is technically buildable but requires elevated construction that adds meaningful cost.

Beyond the FEMA map, walk the land after heavy rain if you can. Standing water, boggy areas, or obvious drainage issues tell you things the map doesn't. A parcel that holds water for days after a storm is a warning sign, regardless of the flood zone label.

What to Know Before Buying Land to Build Near Conway

The Access and Road Considerations

How do you get to the parcel and who maintains that access?

Paved public road access is the easiest. County maintains the road, you drive on it, no additional issues.

Private dirt or gravel road access. Sometimes shared among several parcels. Ask about maintenance responsibility, historic condition, and whether the road can accommodate the construction equipment you'll need during the build.

Easement access across another owner's property. Complicated. Read the easement carefully. Understand what rights you actually have and what the neighbor's rights are.

Landlocked parcels with no legal access. Rare but real. Verify the deed shows clear legal access before committing.

The Timeline and Financing Reality

Buying land to build takes longer than most buyers expect.

  • Land purchase: 30-60 days depending on financing
  • Site prep and design: 3-6 months
  • Permitting through Horry County: 1-3 months typically
  • Construction: 6-12 months for a typical custom home, longer for larger or complex builds
  • Total timeline from land offer to move-in: often 12-24 months

Construction financing works differently than a standard mortgage. Land loans often require larger down payments (20-30 percent) and shorter terms. Construction-to-permanent loans combine the build financing with the eventual mortgage. Talk to a lender experienced in construction lending early in your process.

Where Buildable Land Actually Sits

Different corridors offer different profiles.

Rural roads off Highway 905 northeast of Conway. Larger parcels, real privacy, longer drives to services. Lots range from a couple of acres up to 20+.

Highway 501 west corridor toward Aynor. Mix of residential land and larger parcels, generally easier utilities than deeper rural options.

Communities like Bucksville Oaks and other established Conway subdivisions occasionally have larger lots suitable for custom builds, though inventory is limited.

For pure land inventory across the broader region, Conway homes with acreage includes some improved and unimproved options that give buyers a starting comparison.

Two Things I Tell Every Buyer Considering Land to Build

First, don't skip the perc test contingency. Even if the seller has an old perc test on file, get an updated one if there's any doubt. Building without a valid perc puts you in a worst-case scenario where you own land you can't build on. Never buy without this specific due diligence.

Second, plan for the timeline to double. Whatever schedule you have in your head — permitting will take longer, weather will delay construction, materials will lag, and things will surprise you. Buyers who plan for the timeline to be smooth end up frustrated. Buyers who build in real buffer sleep better through the process.

Key Takeaways

  • Know what you're going to build before you shop land — the answer changes which parcels work
  • Utility access (power, water, septic, internet) is the biggest variable on rural Horry County land
  • Zoning, building codes, and HOA covenants vary widely by parcel — read the specific rules for your target lot
  • The perc test is non-negotiable due diligence before committing to any parcel for a home build
  • FEMA flood zone status and real drainage behavior both matter — check the map and walk the land after rain
  • Verify road access, maintenance responsibility, and legal ingress/egress before writing an offer
  • Total timeline from land offer to move-in commonly runs 12-24 months; construction financing works differently than a standard mortgage
  • Buildable land exists on rural corridors off Highway 905 and 501 west, plus occasional larger lots inside established Conway subdivisions
  • Plan for the timeline to double and never buy without a valid perc test in hand

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.