Conway, SC Real Estate News 

Century 21 McAlpine Blog

The Agents and Staff at Century 21 McAlpine love our area and one another! We hope to share some of our daily activities with you and see how we might better serve our community!


Sept. 16, 2026

The Pre-Listing Checklist Every SC Seller Should Complete

You've decided to sell and you want to do it right. The gap between a home that sells in the first two weeks at asking price and one that sits for months usually comes down to what the seller did — or didn't do — in the 30 to 60 days before listing. Here's the systematic pre-listing checklist I walk every serious seller through. Whether your home fits the mid-tier band or you're competing in Conway luxury homes at the top end, the steps that matter are the same — the intensity just scales up.
The Pre-Listing Checklist Every SC Seller Should Complete

Step One: Get a Real Market Analysis

Before you touch a paintbrush, understand where your home actually sits in the market. Ask your agent for a real CMA — specific comparable sold properties in the last 90 days, active competing inventory, and where your home realistically prices given its condition and features. This number drives every other decision from here forward.

Sellers who skip this step and start prepping based on aspirational pricing usually over-invest in the wrong things. Sellers who anchor their prep to real market data spend money where it actually returns.

Step Two: Complete the Systems Check

Buyers pay attention to systems. Do these before the buyer's inspector finds them.

Have your HVAC serviced by a licensed contractor. Get the receipt. If the unit is 12+ years old on the coast, discuss with your agent whether preemptive replacement makes sense at your price point.

Roof condition check. Roof age and condition affect insurance and buyer confidence. If your roof is nearing end of life, a roofing contractor's evaluation gives you options — repair specific issues, replace preemptively, or price to acknowledge the buyer will replace.

Water heater age check. Anything over 10 years often triggers buyer requests. Sometimes replacement makes sense. Sometimes it doesn't.

Plumbing walk-through. Fix leaking faucets, running toilets, and any visible drainage issues. These show up on inspections and become negotiation points if not addressed.

Electrical panel identification. If you have a Federal Pacific or Zinsco panel, this is a major insurance-and-inspection issue and often needs to be addressed before listing.

Step Three: Address the Coastal Realities

Grand Strand homes carry specific issues buyers look for closely.

Wind mitigation inspection. Get one before listing if your home is coastal. Document any credit-eligible features. This information supports the buyer's insurance quotes and can differentiate your listing.

Salt-air maintenance items. Rinse HVAC condensers, replace corroded exterior hardware, clean gutters. These aren't dramatic but they signal a well-cared-for home.

Flood zone documentation if applicable. Have your elevation certificate ready. Buyers in AE or A zones will want to see it during due diligence.

The Conway property insurance layered coverage reality applies at all price points, and sellers who understand it help their buyers navigate the layered SC coastal insurance system faster.

Step Four: The Cosmetic Refresh That Actually Returns

A few specific cosmetic investments return consistently.

Interior paint in neutral current colors. Highest ROI project on almost every listing.

Deep clean and declutter. Remove 30-50 percent of personal items. Rent a storage unit for a few months if needed.

Refresh worn carpet or refinish existing hardwood. LVP in main areas often outperforms both for coastal humidity.

Kitchen refresh. Paint cabinets, update hardware, replace dated counters with quartz if the neighborhood ceiling supports it, refresh sink and faucet.

Primary bathroom refresh. New vanity, mirror, lighting, and paint. Cost-effective. Real impact.

Front door and curb appeal. Fresh paint on the door, updated hardware, refreshed landscape mulch, replaced dead plants. Small budget. Big first impression.

Step Five: The Outdoor Living Investment

Given the Grand Strand's nine-month outdoor season, outdoor space earns disproportionate attention from buyers.

Pressure wash the exterior. Siding, driveway, walkways, decks. Instant improvement.

Screened porch refresh. New screens if needed. Clean ceiling fans. Update lighting. Fresh paint on the ceiling and any painted surfaces.

Deck and patio refresh. Refinish or replace worn boards. Add outdoor furniture staging if the space is empty.

Yard cleanup. Trim overgrown shrubs. Edge beds. Address any drainage issues visible from the road.

For homes on courses, the outdoor investment also protects the view. Buyers of Conway golf course homes notice the outdoor space as much as the interior.

Step Six: The Professional Marketing Setup

The single highest-ROI investment most sellers make.

Professional real estate photography. A couple hundred dollars for a good package. Pays back many times.

Drone photography if your home benefits from an aerial view — waterfront, wooded lot, pool property, or a home in a specialty pocket like Conway riverfront homes where aerial context matters.

Video walkthrough or Matterport tour. Especially important if you're targeting out-of-state buyers who can't tour easily.

Photo order strategy. The first three photos determine whether buyers keep scrolling. Discuss this with your agent explicitly.

Step Seven: The Documentation Package

Prepare paperwork that supports the buyer's due diligence.

Complete seller's property disclosure form.

Recent utility bills to demonstrate energy costs.

HOA documents if applicable — bylaws, current dues, meeting minutes, reserve study.

Recent repair or replacement receipts (HVAC, roof, water heater, appliances).

Elevation certificate if in a flood zone.

Wind mitigation inspection report if completed.

Any warranty documents on installed systems or appliances.

Buyers who receive this package feel confident. Buyers left to piece together information themselves grow suspicious.

Step Eight: The Staging Decision

Vacant homes photograph cold and feel smaller than they are. Occupied homes photograph best when 30-50 percent of personal items are removed.

Owner-occupied staging typically means decluttering, refreshing bedding and towels, adding plants and current-style throw pillows, and creating photograph-worthy vignettes in key rooms.

Professional staging for vacant homes typically runs a few thousand dollars per month for a professionally furnished home. On homes priced above $500,000 or in bands like Conway homes between $500,000 and $1,000,000, this investment usually pays back several times over in faster days-on-market and stronger offer prices.

Step Nine: The Timing Coordination

Line up the listing date with the market conditions and your personal timeline.

Complete all major work 2-4 weeks before listing. Fresh but not so recent that dust and finishing marks are visible.

Schedule photography once staging and cleanup are complete. Photograph in good light — early morning or late afternoon typically works best.

Coordinate your listing launch with the first weekend when open houses can run and buyer attention is available.

Have your net sheet finalized so you know your realistic bottom line before offers arrive.

What Sellers Skip and Regret

Two patterns worth flagging.

Systems documentation. Sellers who can't produce HVAC service records, roof age, or water heater install date lose credibility during inspection. Get organized before listing.

The final walkthrough by a neutral eye. Have your agent walk through with fresh eyes right before photography. Small items you've stopped noticing — a scuffed wall, a burned-out bulb, a piece of clutter you've grown blind to — often show up in the photos and hurt the listing. A second set of eyes catches them.

Two Things I Tell Every SC Seller About Pre-Listing Prep

First, invest in preparation like you're preparing for a first date, not a job interview. Buyers respond emotionally in the first minute. The way your home presents in those first moments — photos, curb appeal, walk-in impression — determines whether they emotionally invest in touring it. Sellers who prep like they're auditioning fail. Sellers who prep like they're making a first impression succeed.

Second, don't try to hide problems. Every issue you know about becomes something the buyer's inspector will find. Sellers who disclose upfront and address what makes sense before listing avoid negotiation collapse during the inspection period. Sellers who try to conceal problems usually watch deals fall apart 20 days in when the truth emerges.

Key Takeaways

The systematic pre-listing checklist for Grand Strand sellers has nine components that reliably return their investment: real market analysis first, systems check and coastal reality items, cosmetic refresh focused on high-ROI investments, outdoor living investment, professional marketing setup, documentation package, staging decisions, timing coordination, and a neutral-eye final walkthrough. Interior paint, deep clean, professional photography, and curb appeal deliver the strongest returns at almost every price point. Wind mitigation documentation, elevation certificates, and organized HOA and repair records give buyers confidence and speed up their due diligence. Sellers at higher price bands justify heavier investment in staging and professional presentation; sellers at lower bands focus on cleanliness, systems, and honest disclosure. The sellers who consistently sell fastest and closest to asking price are the ones who prepared like they were making a first impression, addressed known issues before listing, and gave buyers a complete documentation package rather than making them work for the information. Preparation isn't optional — it's what separates listings that sell from listings that sit.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Sept. 15, 2026

How to Handle Repair Requests After the Inspection Without Losing the Deal

Your buyer's inspection came back and their agent just sent over a repair request that's longer than you expected. Now you're staring at a list, wondering what to fix, what to credit, what to push back on, and how to keep the deal alive without giving up more than you should. Here's the honest truth. Repair negotiation is where a lot of otherwise-solid deals fall apart, and it's almost always because the seller reacts emotionally instead of strategically. If you're in the current Conway $250,000 to $500,000 band where buyer expectations run high, this is the exact moment discipline pays off.

Why Buyers Send Repair Requests

Understand the buyer's position first. Most inspection responses aren't attempts to nickel-and-dime you. They're the buyer using inspection findings to either reduce their risk or reduce their cost — sometimes both. Some are legitimate concerns about safety, systems, or major structural items. Some are cosmetic asks that shouldn't survive a negotiation. Some are stalking horses for a bigger price reduction the buyer really wants.

Your job is to sort which is which and respond appropriately.

Categorize Every Item Before Responding

Break the request into three buckets.

  • Legitimate structural or safety issues — real problems that would fail a re-inspection or a future buyer's inspection. These usually need to be addressed.
  • System age or condition items — HVAC nearing end of life, roof with limited years remaining, water heater older than expected. These are negotiation points, not automatic yeses.
  • Cosmetic or maintenance items — worn caulk, dated fixtures, minor drywall dings, aesthetic preferences. These should almost never be seller-funded fixes.

Sellers who accept everything are giving up money. Sellers who reject everything usually blow up the deal. Sellers who categorize carefully hold the deal together and only pay for what actually matters.

The Three Response Options You Actually Have

For each item you decide to address, you have three ways to do it.

Complete the repair yourself before closing. Best when the item is simple, the repair is bounded, and you have time. Handle it, get the receipt, close cleanly. The buyer gets what they wanted, you know it's done.

Give a credit at closing. Best when the repair is complex, contested, or something the buyer would rather do themselves after taking ownership. The buyer takes the money, you don't have to coordinate contractors, and everyone moves toward closing faster.

Adjust the sale price down. Effectively the same as a credit but appears differently on paper. Some buyers prefer this because it lowers their financed amount. Some sellers prefer this because it reduces the appearance of concession.

The Coastal SC Wrinkles That Matter

A few items come up specifically on Grand Strand inspections that don't hit inland markets the same way.

Wind mitigation findings that could affect the buyer's insurance premium. If the inspection flags items that keep the buyer from qualifying for wind mitigation credits, expect a bigger negotiation. The buyer isn't just asking about the physical repair — they're asking about the insurance cost impact.

Salt-air corrosion on HVAC condensers, outdoor fixtures, and metal hardware. Common inland-inspector overreactions. Sometimes these are cosmetic wear that's normal for coastal ownership. Push back if the inspector wrote them up like they'd write them up in Charlotte.

CL-100 wood-destroying organism findings. If your CL-100 shows old damage or active conditions, the treatment and repair conversation is separate from the general inspection response. Handle it directly with the pest control company.

Flood zone-related items. If the buyer is in a coastal flood zone and the inspection flags anything related to elevation, drainage, or moisture, expect real attention. Buyers understand these issues affect ownership more than typical inspection findings.

For broader context on how competing listings are presenting at your price band, browse Conway just-listed homes to see how sellers are handling similar conditions on active inventory.

How to Handle Repair Requests After the Inspection Without Losing the Deal

The Language That Works

The specific wording of your response matters. A few patterns I use.

Acknowledge legitimate items. "We appreciate the buyer flagging the water heater. We'll replace it with a new unit and provide the receipt at closing."

Reframe borderline items. "The HVAC is functional and has been serviced regularly. We're happy to provide a credit of X toward the buyer's post-closing update if they'd prefer to make changes."

Decline cosmetic items firmly. "The paint touch-ups and caulking items are typical wear on a home of this age and aren't part of what we can address in this transaction."

Don't apologize. Don't overexplain. Confident responses close deals. Apologetic responses invite more requests.

When to Walk Away From the Deal

Rare, but real. If the buyer's inspection response includes major items you know are unreasonable, if they're using the response to renegotiate the price aggressively, or if the total ask exceeds what makes sense given the market, sometimes the right move is to decline and let the buyer terminate.

What matters here is understanding your position. If your home is well-priced and buyer demand is real, another offer is likely close behind. If your home has been on for months and this is your first serious offer, holding the deal together may be worth more than winning the negotiation.

The Conway property insurance reality also matters here. If insurance-related repairs get pushed hard by the buyer, understand that any future buyer will face the same insurance requirements. Addressing legitimate insurance items now may just be moving the same expense to the next transaction.

What Nobody Tells Sellers About Repair Negotiations

Two things.

Buyer's remorse hits during the inspection period more often than people realize. Sometimes what looks like a repair request is really the buyer looking for a reason to walk away. Recognizing this changes how you respond. If the buyer wants out, giving in on every request won't save the deal — it'll just cost you money before they leave anyway.

Repair receipts and warranties carry value at your next sale. Anything you fix and document becomes part of the home's story. Well-organized repair records help future buyers feel confident and can prevent similar inspection findings on your next transaction if you buy again in the area.

Two Things I Tell Every Seller Facing a Repair Request

First, don't respond within 24 hours. Take a beat. Read the response carefully. Categorize the items. Talk to your agent about what's reasonable, what's not, and what the buyer likely really cares about. Sellers who respond emotionally in the first hours usually give up more than they should. Sellers who respond thoughtfully in a day or two hold the deal together on better terms.

Second, remember your goal is to close the deal, not to win the negotiation. Trading pride for principle costs sellers real money in this exact moment. If a $1,500 credit keeps a $400,000 deal alive, that math is easy. Take the credit conversation seriously and get to closing.

Key Takeaways

  • Repair requests come from real buyer risk-reduction, not attempts to nickel-and-dime — but not every item deserves a yes
  • Categorize items into legitimate structural/safety, system age/condition, and cosmetic/maintenance before responding
  • Your three response options are complete the repair, provide a credit at closing, or adjust the sale price down
  • Coastal SC wrinkles include wind mitigation impacts, salt-air corrosion overreactions, CL-100 findings, and flood zone-related items
  • Firm but not defensive language holds the deal together — acknowledge legitimate items, reframe borderline ones, decline cosmetic asks confidently
  • Sometimes walking away from an unreasonable request is the right move, especially with strong market demand for your home
  • Buyer's remorse during inspection is more common than sellers realize — recognize it before giving up too much
  • Repair receipts carry value at your next sale; document everything you complete
  • Wait 24 hours before responding and remember your goal is to close the deal, not to win the negotiation

Frequently Asked Questions

Can I refuse to make any repairs after the inspection?

Yes. You can decline every request. The buyer then has to decide whether to accept the home as-is, negotiate further, or terminate the contract during their inspection contingency. Whether refusal is smart depends on your market position, the specific items requested, and your assessment of how likely the buyer is to walk.

What's the difference between a repair credit and a price reduction?

Practically, they're similar — both reduce what the seller ultimately receives. A credit at closing appears as a settlement adjustment. A price reduction changes the actual contract sale price. Some buyers prefer price reductions because it lowers their financed amount and future property tax basis. Some sellers prefer credits because they don't affect the visible sale comparable.

Do I have to provide a licensed contractor for repairs I complete?

Depends on the specific repair and any lender or contract requirements. Structural, electrical, plumbing, and HVAC work typically requires licensed contractors. Cosmetic and general handyman work usually doesn't. Ask your closing attorney about anything unclear.

Should I get my own repair estimate before responding to the buyer's request?

Often yes, particularly for items where the buyer's inspector recommended repairs without a specific cost. A real estimate from your preferred contractor gives you leverage in the negotiation and prevents overpaying based on inflated buyer expectations.

What happens if we can't agree on repairs?

The buyer can terminate the contract during their inspection contingency period and typically receives their earnest money back. If the contingency has expired and they walk anyway, earnest money may become a negotiation point. Your closing attorney can walk you through the specific contract terms.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 14, 2026

How to Handle Multiple Offers on Your Coastal SC Home

Your listing hit the market last week and now you've got three offers on your kitchen counter. Here's the thing. Multiple-offer situations feel like a win, and they usually are — but only if you handle them well. Sellers who get emotional or greedy at this stage regularly leave money on the table or blow the deal entirely. Whether you're in a hot pocket showing up in Conway just-listed homes or working through offers on a higher-price-band property, the strategy that works is more about discipline than luck.

Why Multiple Offers Happen

Multiple offers don't happen by accident. When a listing draws several offers quickly, it's because a few things came together — the price was right for the market, the presentation caught buyer attention on the phone scroll, the property is genuinely appealing to more than one buyer type, and the launch timing hit an active buyer pool.

Sellers who land multiple offers should understand this. You did something right. The offers you're looking at reflect the current market's real read on your home. That's information you can use.

What Most Sellers Get Wrong at This Stage

Here's what nobody tells sellers. The highest offer isn't automatically the best offer. And the temptation to just pick the biggest number is often exactly the wrong move.

What you're actually looking for is the offer most likely to close, at the best combination of price, terms, and certainty. That's a different question than "which number is highest."

The offers you receive vary on many dimensions beyond price. Financing type. Down payment. Contingency structure. Timing. Inspection terms. Concessions requested. Buyer flexibility. Buyer motivation. All of these matter. Sellers who focus only on the top-line price sometimes accept the offer most likely to fall apart.

How to Evaluate What's Actually on the Table

A few things to look at seriously.

Financing strength. A cash offer at slightly below the top price is often stronger than a financed offer at the top. Verify the cash. If financed, look at the pre-approval quality — is it a full commitment letter or a soft pre-qualification?

Down payment. Larger down payments mean the deal is less exposed to appraisal issues. A financed offer with 30 percent down handles a low appraisal better than one with 5 percent down.

Contingencies. Inspection contingency, financing contingency, appraisal contingency, home-sale contingency. Each one is a potential deal-killer. Fewer contingencies means more certainty.

Timing. Some buyers can close in 21 days. Some need 60. What's the seller's timeline? What matches?

Concessions. Some offers request seller-paid closing costs, home warranties, or repair credits. These reduce your net.

Buyer motivation. Relocation buyers with move dates are usually more motivated. Investors sometimes walk when better deals appear. Ask your agent what they know about each buyer.

Escalation clauses. Some offers include automatic escalation up to a cap. These can drive final price higher than the initial number suggests.

How to Respond Strategically

You have three main options when you receive multiple offers.

Accept the strongest offer as-is. If one offer clearly wins on the balance of price, terms, and certainty, take it. Move to closing. Don't overthink it.

Counter one specific offer. If the strongest offer is close but not quite there on a specific term, counter that one. This preserves the relationship and gets you the terms you want without introducing new uncertainty.

Call for highest and best. Ask all buyers to submit their strongest offer by a specific deadline. This can generate meaningful improvements from motivated buyers who realize they're in competition. It also risks losing offers from buyers who won't play the highest-and-best game.

The right response depends on your specific situation. Sellers with time pressure often accept quickly. Sellers with more time can push for highest and best.

What "Highest and Best" Actually Looks Like

When you call for highest and best, structure it carefully.

Specific deadline. All improved offers due by a specific date and time.

Clear communication that all buyers are being asked, so buyers don't feel targeted or manipulated.

A commitment that you'll make your decision by a specific date after the deadline.

Instructions about what buyers should focus on improving — sometimes it's price, sometimes it's terms, sometimes it's timeline.

Buyers respond to structure. When the process feels professional, they submit stronger offers. When it feels chaotic, some walk away.

How to Handle Multiple Offers on Your Coastal SC Home    The Coastal SC Wrinkles

Coastal properties have some specific dynamics worth flagging.

Insurance can make or break a deal at the higher price points. Buyers who don't understand the layered coastal SC insurance system sometimes walk away when the real quote arrives. The Conway property insurance reference helps buyers understand what they're getting into and reduces the risk of a walk-away.

Flood zone status affects buyer confidence. Sellers with AE-zone homes should be prepared to answer flood-related questions from any serious buyer.

Wind mitigation credits matter. A well-built coastal home with documented wind mitigation features supports stronger financing outcomes.

For sellers in the higher-price bands, understanding how competing inventory in Conway homes between $500,000 and $1,000,000 is pricing helps calibrate what "highest and best" should look like.

Waterfront and Specialty Property Dynamics

Multiple-offer situations play out differently on specialty properties. Conway riverfront homes often draw a specific buyer pool with real commitment. When these buyers write offers, they typically mean it. Sellers of unique properties should factor buyer conviction into their evaluation, not just top-line numbers.

What Nobody Tells Sellers About Multiple Offers

Two patterns I watch consistently.

Buyers who lose competitive offers rarely come back later. If you push a highest-and-best process and buyers feel manipulated, they move on. The pool of active buyers isn't infinite, and losing potential offers has real cost.

The offer you accept has to actually close. A stronger-looking offer that falls apart 30 days in can cost you more than accepting a slightly lower offer that closes cleanly. Days-on-market grows every day the property sits. Stale listings sell for less.

Two Things I Tell Every Seller Handling Multiple Offers

First, remove emotion from the decision. This isn't personal. It's a business transaction and the buyers are people trying to make good decisions with their money. Sellers who take the process personally often make worse decisions than sellers who evaluate the offers analytically.

Second, trust your agent's read on the buyers. Your listing agent has been talking to the buyer agents. They know things about each buyer's motivation, financial position, and reliability that don't show up on the offer sheet. That knowledge matters. Use it.

Key Takeaways

Multiple offers on your coastal SC home are the result of a well-executed listing, not luck. The highest offer isn't automatically the best offer — the offer most likely to close cleanly at the best combination of price, terms, and certainty is what you're actually looking for. Financing strength, down payment size, contingency structure, timing, concessions, and buyer motivation all factor into evaluation alongside the top-line price. You have three main response options — accept the strongest offer, counter a specific offer, or call for highest and best. Coastal wrinkles like layered insurance, flood zone questions, and wind mitigation credits shape which offers are most likely to survive. Sellers who remove emotion from the decision, evaluate the full picture rather than just the price, and trust their agent's read on the buyers consistently walk away with better outcomes than sellers who chase the biggest number. Multiple offers are a real win. The way you handle them determines whether that win translates to your closing statement.

Frequently Asked Questions

Do I have to disclose to buyers that I have multiple offers?

You're not required to disclose specific offer details, but you can — and often should — inform all interested buyers that you're in a multiple-offer situation. Transparency about the process encourages stronger offers and reduces the sense that anyone was manipulated.

Can I accept more than one backup offer?

South Carolina purchase contracts typically allow for backup offers that become primary if the accepted offer falls through. Having a strong backup gives you leverage during the primary contract's inspection and financing periods and reduces the pain if the primary buyer walks.

Is it legal to counter multiple offers at once?

Countering multiple offers simultaneously is legal but complicated — you can create a situation where multiple buyers accept your counter and you're technically bound to multiple contracts. Most experienced agents recommend against this in favor of highest-and-best or countering one offer at a time.

What if the top offer's buyer refuses to remove contingencies?

You can decline that offer and move to the next-strongest. Contingencies are negotiation points, and buyers who won't budge on unusual contingencies often reveal themselves as high-risk closers. Better to know that upfront than 30 days into escrow.

How long should I give buyers to submit highest-and-best offers?

Typically 24-72 hours from when the request goes out. Shorter windows work when buyers are already fully engaged. Longer windows help when out-of-state buyers need coordination time. Your agent's read on the buyer pool should drive the specific timing.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 11, 2026

What to Do When Your Home Isn't Getting Showings

Your home has been listed for three weeks and the showing calendar is empty. The initial buzz died. Nobody's asking questions. Nobody's writing offers. Your agent keeps telling you to be patient, but you know something's wrong. Here's the truth. When showings dry up, it's the market telling you specific information about your listing. You can either listen and adjust, or wait months watching the situation get worse. Whether you're competing in the entry band of Conway homes $0-$250,000 or the top end, the diagnostic process is the same. Let me walk you through what's actually happening and what to do about it.

What Silence From Buyers Actually Means

When buyers aren't scheduling showings, they're not being lazy. They're actively skipping your listing during the phone-scroll elimination round. That means something about the online presentation isn't grabbing them. The lead photo, the price, the address, or the description isn't clearing the bar to earn a click.

Buyers who don't click never see your home. If they never see it, they never tour it. If they never tour it, they never write an offer.

The problem isn't that your home is bad. The problem is that buyers aren't getting far enough to even evaluate whether it's bad.

The Three Things That Kill Showings

From watching hundreds of stale listings, three specific issues cause almost all of them.

Price. This is the biggest one. If your price is above what buyers see as fair value for the specific property, they filter it out or skip it during the scroll. Price is the primary control lever, and it's the first thing to reevaluate when showings dry up.

Photos. Weak lead photos, dark interiors, cluttered rooms, or phone-camera quality kill the scroll. Buyers form opinions in seconds. If the photos don't earn a click, nothing else matters.

Positioning. Sometimes the home is priced right and photographed well but positioned wrong — wrong category, wrong feature emphasis, wrong buyer pool targeted. Buyers who would love the home aren't finding it because it's showing up in the wrong searches.

The Diagnostic Question to Ask

Ask your agent this specifically. How many buyer inquiries has the listing generated? How many click-throughs? How many saves on the major platforms? These numbers tell you exactly where the funnel is breaking.

Lots of views but no showings: the listing draws attention but doesn't survive the deeper look. Usually a photo or price problem.

Few views: the listing isn't reaching enough buyers. Usually a category, description, or targeting problem.

Views and saves but no showings: buyers are considering but eliminating. Usually a specific concern — price, condition disclosure, or something in the photos that raises red flags.

What to Do When Your Home Isn't Getting Showings

What Actually Fixes a Stale Listing

Different problems require different fixes.

For price problems, the answer is a real price adjustment. Not a token cut. A meaningful adjustment that moves you into the correct search band. If your home is priced at the top of the $325,000-$350,000 band and getting no showings, dropping to $324,900 puts you at the top of $300,000-$325,000 and captures a different buyer pool. Small drops rarely trigger new buyer interest. Meaningful drops do.

For photo problems, hire a real photographer and reshoot. The cost is a rounding error against your sale price. Have your agent think about lead photo order strategically. The first three photos determine whether buyers stay or scroll.

For positioning problems, rewrite the description with different feature emphasis. Update the categories where the home appears. Make sure the listing is landing in the search results where the right buyers actually look. If your home has features that matter to a specific buyer pool — luxury finish, waterfront, golf course frontage, gated community — verify those features are prominent in the listing. Homes that would compete for a spot on Conway homes over $1,000,000 shouldn't be positioned identically to entry-level inventory.

The Refresh Strategy That Works

At about 21 days without showings, a full listing refresh often restarts the momentum.

New lead photo. New photo order. Refreshed description. Updated open house calendar. If a price adjustment is warranted, do it as part of the refresh so the change lands as a unified update rather than a series of small drops.

The refresh pushes the listing back into search algorithms as new-looking activity. Buyers who saw the listing on day one and passed will see the refreshed version and often give it a second look. Small changes rarely trigger this. Substantive refreshes do.

What Nobody Tells Sellers About Stale Listings

Two hard truths.

Stale listings sell for less. Every day on market extends the discount buyers expect. Homes that would have sold at full asking price during the first two weeks routinely sell at 5-10 percent below asking after 90 days. The longer the wait, the bigger the eventual discount.

Days on market compound negatively. Buyers see the DOM number and assume something's wrong. That assumption becomes a self-fulfilling prophecy — buyers don't tour because DOM is high, DOM keeps growing because nobody tours. Breaking that cycle requires decisive action, not more patience.

For broader context on how your listing compares to active inventory, browse Conway real estate at your price point and Conway just-listed homes to see what fresh competition looks like.

What Sellers Get Wrong at This Stage

The most common mistake I see. Sellers who blame the market when the market is telling them clear feedback about their specific listing. If comparable homes are selling and yours isn't, the issue isn't the market — it's something about your listing. Accepting that feedback quickly is what separates sellers who recover from sellers who watch their listing die on the vine.

The second common mistake. Waiting too long between adjustments. Sellers who reduce price 2 percent at 30 days, 2 percent at 60 days, and 2 percent at 90 days often end up worse off than sellers who made one decisive 6 percent cut at 30 days. Buyers watch the pattern. A stair-step of small cuts signals desperation and encourages lowball offers. One decisive move suggests seller commitment to actually closing.

The Alternative Nobody Wants to Discuss

Sometimes the right move is to pull the listing entirely, address the underlying issues, and relist as a fresh property later. This resets the days-on-market counter and gives you a genuine second launch.

The trade is time and expense. But for homes with fundamental positioning problems or condition issues that need addressing, a full reset can produce better outcomes than months of gradual price cuts on a stale listing. For lower-priced inventory competing in bands like Conway homes under $300,000, where turnover is faster, the reset strategy can work particularly well.

Two Things I Tell Every Seller Whose Listing Isn't Getting Showings

First, act within the first 30 days. Every week beyond that first month costs you options. Sellers who diagnose the problem quickly and adjust decisively usually recover. Sellers who wait for the market to change often watch their situation get worse for months before finally accepting the feedback and cutting price further than they would have needed to earlier.

Second, trust the diagnostic data over your emotional attachment to the home. Your feelings about your home's value are real. The market's feedback is also real. When they disagree, the market wins. Sellers who accept that reality quickly close the deal. Sellers who argue with the market usually lose.

Key Takeaways

When your home isn't getting showings, the market is telling you specific information about your listing that you can either use or ignore. The three factors that kill showings are price, photos, and positioning — and diagnostic data on views, saves, and inquiries points you to which one applies. Fixes are specific to the diagnosis: meaningful price adjustments that move you into a different search band, professional photography with strategic photo order, or repositioning that surfaces your home to the right buyer pool. A full listing refresh at about 21 days often restarts momentum by pushing the listing back into algorithms as new-looking activity. Stale listings sell for less as days on market compound negatively, and buyers use high DOM as a signal to expect discounts. Sometimes pulling the listing entirely and relisting fresh after addressing underlying issues produces better outcomes than watching gradual price cuts erode value. The sellers who consistently recover from slow starts act within the first 30 days, adjust decisively rather than in small steps, and trust the diagnostic data over emotional attachment to a specific number. Silence from buyers isn't a wait-and-see situation. It's a real signal that requires real action.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 10, 2026

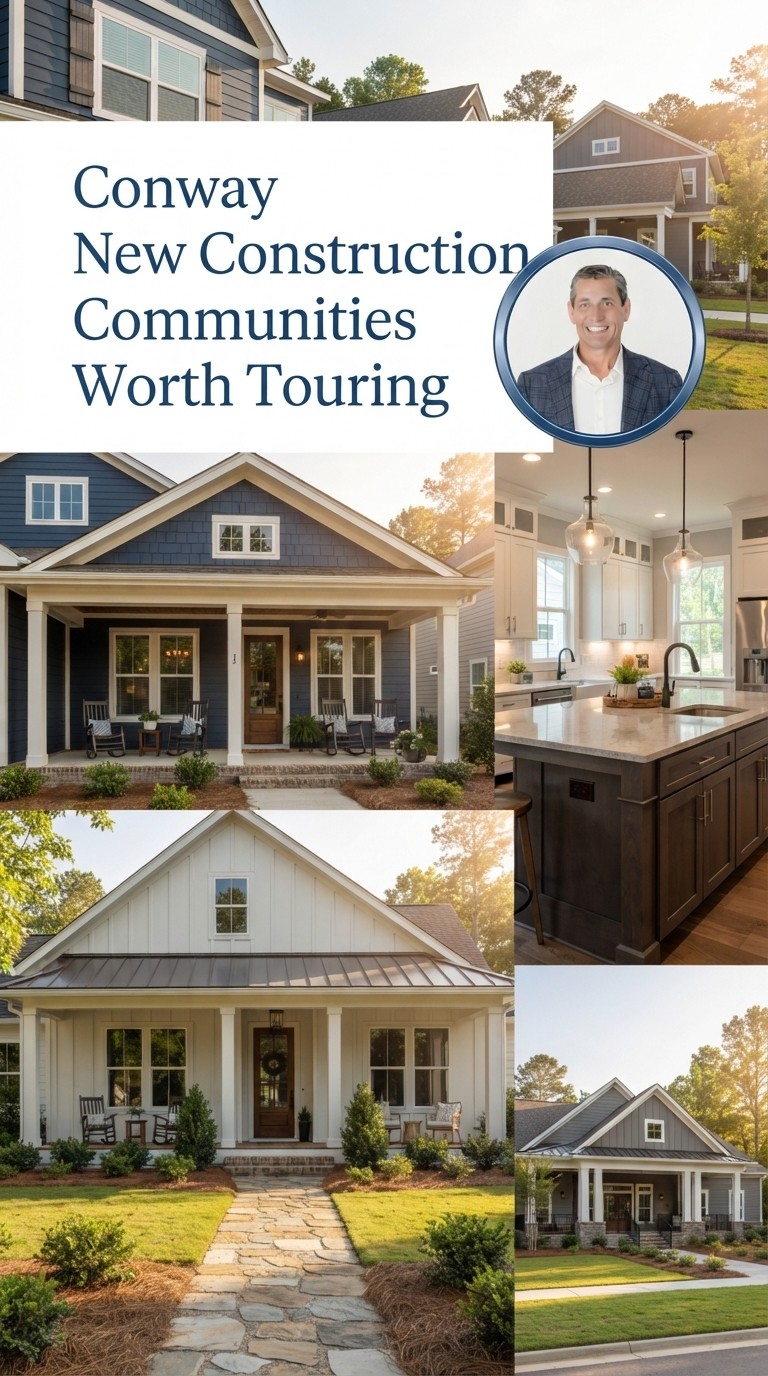
Conway New Construction Communities Worth Touring

You've decided you want a new-construction home in the Conway area and now you need to know which specific communities are actually worth touring. Here's the honest picture. Conway new construction inventory has expanded meaningfully over the last several years, but not every builder community delivers what buyers want. Some pockets are getting quality construction with layouts that fit modern life. Others are pumping out cookie-cutter product that already feels dated. Let me walk you through the specific Conway new construction communities that consistently show up in my closings — and why each one fits a specific buyer.

What Actually Makes New Construction Worth Buying

Before diving into specific communities, here's what separates the good from the mediocre. Layouts that support modern family life — real home offices, first-floor primary suites, walk-in pantries, thoughtful storage. Energy-efficient builds with modern HVAC, insulation, and windows. Wind mitigation features that translate into real insurance discounts. Builder warranties that actually cover what they promise. Community amenities that residents genuinely use, not decorative pools that sit empty. And prices that don't require every possible incentive stacked to make the math work.

Sedgefield for Value-Focused New Construction

Sedgefield delivers new construction at price points that keep the mortgage math workable for a broad range of buyers. What buyers respond to here: newer product without stretching the budget past what makes sense. Layouts that fit typical family use. Community feel that comes from having enough neighbors of similar life stage that friendships develop naturally.

Chestnut Ridge for Modern Community Feel

Chestnut Ridge attracts buyers who want the current wave of new construction — updated exteriors, contemporary floor plans, and community amenities that reflect what modern families actually use. Move-up families and out-of-state relocators land here often. The specific appeal: the community reads as newer and more current than some of the older builder subdivisions in the area.

Aquila Estates for Newer Construction Near CCU

Aquila Estates delivers newer construction with location advantages that pure exurb communities don't offer. Reasonable proximity to CCU, to Conway's downtown, and to the Highway 501 retail corridor. For buyers who prioritize a shorter drive to daily-life services alongside the benefits of new construction, this is one of the more balanced options.

Dudley Farms for Newer Homes with Space

Dudley Farms occupies a specific niche — newer construction on lots with more depth than typical builder subdivisions offer. If you want new construction without the tight-lot feel that comes with dense builder communities, this is worth a look. Modern layouts, updated finishes, and the kind of lot that leaves room to add a fence, a shed, or landscaping over time.

Pottery Landing for Character-Focused Newer Construction

Pottery Landing sits in a distinctive Conway pocket that doesn't feel like typical suburban builder inventory. Homes with more character than the standard national-builder template, on lots with real depth. If you want new construction that doesn't scream new construction, this is where buyers with an eye for something different tend to land.

Pecan Grove for Newer Options with Established Feel

Pecan Grove combines newer inventory with the established community feel that pure new subdivisions can't offer yet. Mature trees where the community has grown around them. Neighbor networks that already exist. For buyers who want the benefits of newer construction without waiting five years for the community to develop its identity, this is a smart choice.

Conway New Construction Communities Worth Touring

Which Communities Fit Which Buyer

A quick map of who typically lands where.

First-time buyers who want new construction at reachable price points often start at Sedgefield or Aquila Estates. Both deliver newer inventory without the price ceiling of some of the higher-end options.

Move-up buyers with equity from a starter home usually tour Chestnut Ridge, Dudley Farms, and Pottery Landing, comparing across the modern-versus-character spectrum.

Out-of-state relocators from the Northeast and Midwest often prioritize Chestnut Ridge, Aquila Estates, and communities that match the suburban aesthetic they're familiar with.

Retirees who want new construction with real community feel gravitate toward Pecan Grove and Dudley Farms for the established atmosphere alongside newer builds.

For inventory across the mid-tier price range where much of this new construction sits, browse Conway homes between $250,000 and $500,000 to see the current active market.

What New Construction Buyers Should Verify

Standard new-construction due diligence with a few Conway-specific twists.

Builder warranty details. What's covered, for how long, and what the claim process actually looks like. Not all warranties are equal.

Design center pricing and what's actually included in the base home versus what's an upgrade. National builders typically list a base price that assumes minimal upgrades. Realistic total spend is usually meaningfully higher.

Lot premiums. Corner lots, pond views, and cul-de-sac positions typically carry premiums. Some of those premiums hold value on resale. Others don't.

School attendance zone by exact address. Community names sometimes span multiple school zones.

Wind mitigation features and the specific insurance discounts they translate into. A well-built new home often qualifies for meaningful wind and hail credits.

HOA structure, dues, and any pending or forthcoming amenities. Communities still being built out sometimes charge for amenities that aren't yet operational.

What New Construction Buyers Underestimate

Two patterns worth flagging.

Post-closing setup costs. New construction typically comes with no blinds, minimal landscaping, no fence, and often no gutters. Budget several thousand dollars in the first few months for making the house live the way you actually want it to.

Warranty follow-through. Cosmetic issues get addressed quickly. Settling cracks, drainage adjustments, and HVAC tuning can drag out. Document everything in writing during the initial walkthrough and stay organized with follow-up requests.

Two Things I Tell Every New Construction Buyer

First, tour multiple communities in the same visit if you can. National builders present each community as unique, but the underlying construction quality, warranty structure, and long-term value hold up differently across them. Buyers who compare directly consistently make better decisions than buyers who fall for the first community they tour.

Second, negotiate incentives, not price. Builders protect the base price to preserve comparable sales in the community. What they'll actually give up is rate buydowns, closing cost credits, upgrade packages, and design center allowances. Ask specifically for these rather than trying to negotiate the base price down.

Key Takeaways

  • Conway new construction inventory has expanded meaningfully but quality varies significantly by community
  • Sedgefield delivers value-focused new construction at reachable price points for first-time and budget-conscious buyers
  • Chestnut Ridge attracts buyers wanting current-generation community feel with modern floor plans and amenities
  • Aquila Estates combines newer construction with location advantages near CCU and Conway's downtown
  • Dudley Farms offers newer homes on deeper lots for buyers who want space alongside modern construction
  • Pottery Landing delivers newer construction with more character than standard national-builder inventory
  • Pecan Grove combines newer inventory with established community feel and mature trees
  • Verify builder warranty, realistic total spend with upgrades, lot premiums, school zones, wind mitigation credits, and HOA structure before signing
  • Budget several thousand dollars for post-closing setup — blinds, landscaping, fence, gutters
  • Tour multiple communities in the same visit and negotiate incentives rather than base price

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 9, 2026

Where to Find Homes with Real Acreage Near Conway, SC

You want a home in the Conway area with actual acreage — not a "large lot" that's really a quarter acre, but real land. A yard your dog can run in. Room for a garden that actually feeds you. Space for a workshop, a chicken coop, or an RV pad. Here's the good news. Conway has more acreage inventory than most buyers realize once you know where to look. Communities like Dudley Farms and dedicated searches like Conway homes with acreage pull inventory that doesn't show up in standard MLS results.

What "Acreage" Really Means in Conway

Definitions matter here. In the Conway market, "acreage" typically means anything over one acre. Below that, you're still in the residential lot category — a nicer yard, but not really land. Once you cross one to two acres, the property starts behaving like acreage. You have room for the outbuilding, the garden, the tree line for privacy. Above five acres, you're firmly in rural residential territory with all the freedom that entails.

What buyers should understand: acreage in Conway isn't concentrated in one specific pocket. It's spread across the outer ring of the city and into the surrounding county. Different corridors serve different buyer priorities.

The Highway 905 Corridor

The Highway 905 corridor northeast of Conway is where a lot of the acreage inventory lives. Homes here range from older farmhouses on 5-10 acres to newer builds on 2-3 acre lots. The trade is a longer drive to daily-life services in exchange for genuine land at prices that don't work closer to town. Buyers who want the country feel without giving up reasonable Conway proximity often land here.

Dudley Farms and the Farm-Community Feel

Dudley Farms delivers a specific type of Conway acreage lifestyle. Homes on real lots in a community where the name isn't just marketing — there's genuine farm character to the surrounding area. Buyers who want acreage but also want the neighborhood feel that comes from a defined community, rather than an isolated country road, often prefer this kind of setup.

Buckeye Forest for Wooded Privacy

Buckeye Forest attracts buyers who want the specific combination of tree canopy and lot depth. If your vision of acreage includes actual woods on your property — not just a big open lawn — communities with real tree cover deliver a different daily experience than cleared subdivisions do. Older neighborhoods with mature trees rarely get replaced by newer construction because the character can't be re-created quickly.

Cat Tail Bay for a Different Setting

Cat Tail Bay offers a distinctive natural setting that changes what acreage feels like. Water features, wildlife presence, and lots that leverage the surrounding landscape make this pocket feel different from typical inland acreage. For buyers whose acreage priorities include being able to actually enjoy the natural setting, not just own the square footage, this is worth touring.

The Rural Roads Off Highway 501 West

Between Conway and Aynor along Highway 501 and the back roads that connect to it, acreage inventory shows up regularly. Older homes on real land, occasional custom builds, and pure land parcels for buyers planning to build. This corridor works well for buyers who prioritize proximity to Conway proper over pure remoteness — you're 15-20 minutes from Conway's amenities on most of these addresses.

Where to Find Homes with Real Acreage Near Conway, SC

What Acreage Buyers Should Verify

Rural due diligence is different from subdivision due diligence.

Well water testing during the inspection period. Most acreage properties in Conway run on well water. Iron content, sulfur, hardness, and bacterial testing all matter. The results shape both your water treatment budget and your understanding of ongoing costs.

Septic system inspection and permits on file with SCDHEC. Tank size, drain field condition, and soil percolation determine whether the system works long-term. A septic-specific inspection is separate from the standard home inspection.

Well and septic separation distances if you're on both. State code requires minimum separation, and older properties sometimes have grandfathered configurations that could become issues if you need to replace systems.

Internet quality by exact address. Fiber has expanded in Conway but coverage on rural addresses varies street by street. For remote workers, this is a make-or-break check.

Flood zone status. Some low-lying acreage near the Waccamaw River or its tributaries sits in AE or A flood zones with real insurance implications.

Insurance quotes for the specific property. Wind and hail coverage applies inland too, and premiums can vary meaningfully based on structure type and outbuildings. The Conway property insurance reference helps buyers understand how the layered coastal SC insurance system applies to Conway addresses.

Zoning and building restrictions. What can you build? Can you have chickens? Livestock? An accessory dwelling for family? Rural zoning is often more permissive than subdivision covenants, but the specific rules vary by parcel.

The Ongoing Costs Acreage Buyers Underestimate

Two categories worth planning for.

Maintenance workload. More land means more mowing, more tree management, more perimeter care, more drainage attention after storms. If you're moving from a subdivision quarter-acre, the shift is real. Buyers who love the outdoor work thrive. Buyers who assumed the land would take care of itself often struggle.

System capital costs. Well pump replacement, pressure tank replacement, septic pumping and eventual system components, and outbuilding maintenance all add up over years of ownership. Budget for these realistically. On a 20-year ownership window, well and septic capital costs commonly run into five figures.

Two Things I Tell Every Conway Acreage Buyer

First, walk the property line to line. Not just the driveway and the house. Actually walk the corners of the lot. The trees, the slope, the drainage patterns, the neighbors' property behavior right up against your boundary. Buyers who walk their land make much better decisions than buyers who evaluate from photos.

Second, visit after a heavy rain if you possibly can. Rural drainage varies dramatically from lot to lot, and the property that looks great in dry weather can hold standing water for days after a real storm. Understanding your land's water behavior before you close saves years of frustration.

Key Takeaways

Conway has more acreage inventory than most buyers realize when they start their search. The Highway 905 corridor, Dudley Farms, Buckeye Forest, Cat Tail Bay, and the rural roads off Highway 501 west toward Aynor all serve different acreage priorities. Buyers who want farm-community feel land differently than buyers who want wooded privacy or buyers who prioritize proximity to Conway's amenities. Standard acreage due diligence — well water testing, septic inspection, internet quality by address, flood zone status, insurance quotes, and zoning verification — matters far more than it does on subdivision properties, because the systems and rules that shape ownership are different. Maintenance workload and long-term system capital costs are the two ownership categories acreage buyers most often underestimate. Walking the property line to line and visiting after a heavy rain are the two decisions that consistently lead to good long-term acreage ownership. Conway acreage delivers real quality of life for buyers who match the pace, prepare for the workload, and pick the specific pocket that fits how they actually want to live on the land.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 8, 2026

Should I Sell As-Is or Make Repairs Before Listing?

You're getting ready to sell and looking at your home with fresh eyes. The kitchen is dated. The roof has a few more years but not many. The paint is tired. Now you're wondering: do I invest in repairs and updates before listing, or sell it as-is and let the next owner deal with it? Here's the honest answer. It depends on your specific home, your price band, and your timeline. Sellers who ask this question in a vacuum often make the wrong call. Let me walk you through the framework I use — comparing your specific home to inventory like Conway homes under $300,000 or higher-tier bands, depending on where you sit.

What "As-Is" Actually Means

Before deciding, understand the terminology. Selling as-is doesn't mean you skip disclosures or repairs the buyer might want. It means you're listing with a clear signal that you don't intend to negotiate repairs during the inspection period. Buyers can still walk away based on inspection findings. They can still request repairs. You just don't have to say yes.

As-is listings typically sell at a discount to fully-updated comparables. The discount reflects the buyer's assumption that they'll need to invest in updates after closing. The question is whether the discount you'd accept is larger or smaller than the investment you'd make.

The Framework I Use with Sellers

A few questions I walk every seller through before deciding.

  • What's the current condition of your home versus competing inventory at your price point?
  • What specific items are dated or worn?
  • What's the realistic cost of updating each item?
  • What's the realistic return on each update in terms of sale price?
  • What's your timeline? Can you afford to delay listing to complete work?
  • What's your risk tolerance for money spent on preparation that doesn't return?
  • What buyer pool is realistic for your home — investors, first-timers with limited cash, or updated-home shoppers?

When As-Is Makes Sense

Selling as-is often works when specific conditions apply.

  • You need to close quickly and can't afford weeks or months of preparation work
  • You don't have the cash to invest in updates upfront
  • The home has fundamental structural or system issues that would consume any investment without meaningful return
  • Your target buyer pool includes investors and buyers who want to renovate to their own taste
  • You've inherited or received the property and don't have the emotional attachment to invest
  • The location and land value dominate the home value, so buyers are essentially buying the lot

Investor-friendly homes and lower-price-band properties often sell as-is successfully because the buyer pool for those homes includes people specifically looking for projects.

Should I Sell As-Is or Make Repairs Before Listing?When Repairs and Updates Make Sense

The math flips when different conditions apply.

  • Your home sits in a price band where buyers expect updated finishes as baseline
  • Comparable competing inventory has been updated recently
  • You have time and cash to complete work before listing
  • Specific dated items (paint, flooring, kitchen finishes) can be addressed cost-effectively with high return
  • Your target buyer pool includes families, retirees, or relocators who want to move in without a project
  • The home is in a desirable neighborhood where the discount from as-is would exceed the update investment

For homes in the Conway $250,000 to $500,000 band, buyer expectations for finished condition are typically higher than at lower price points. As-is at this level often means accepting a meaningful discount.

The Specific Updates That Usually Pay Back

If you decide to invest in updates, some deliver consistent returns.

  • Interior paint refresh in neutral colors. Highest ROI project on almost every listing.
  • Deep cleaning and decluttering. Costs a few hundred dollars, returns thousands.
  • Landscape refresh and curb appeal work. First impressions matter more than sellers think.
  • Kitchen refresh (paint cabinets, update hardware, quartz counters, new sink and faucet). Cost-effective versus full remodel with solid return.
  • Primary bathroom refresh (new vanity, mirror, lighting, fresh paint). Modest cost, real impact.
  • Replace worn or dated carpet with LVP in main living areas.
  • Address any obvious deferred maintenance — running toilets, leaking faucets, dead outlets, missing caulk.

The Updates That Rarely Pay Back

Some investments consistently underperform.

  • Full kitchen or bathroom remodels beyond what a refresh accomplishes
  • Room additions
  • Elaborate landscape overhauls with expensive plantings
  • Pool installation purely for sale
  • Trendy fixture or color choices that date quickly
  • High-end appliance packages beyond what the neighborhood expects

Sellers who spend on these often watch the investment fail to return.

How Price Band Changes the Answer

Where your home sits in the market changes the calculation.

At lower price points, cosmetic condition matters less because the buyer pool includes investors and first-time buyers who expect projects.

At mid-tier price points, updated cosmetic condition matters more because move-up families and relocators expect to move in without immediate project work.

At higher price points including Conway luxury homes, condition, finishes, and presentation matter enormously. Selling luxury as-is usually means leaving significant money on the table unless the property has other overwhelming appeal.

Specialty properties like golf-community homes at Conway golf course homes or lakefront properties sometimes attract buyers who value the location so heavily that condition matters less. Talk to your agent about your specific pool.

The Middle-Ground Approach That Often Works

Not every seller has to choose between all-in updates or full as-is. A middle-ground approach often delivers the best returns.

  • Do the high-ROI cosmetic work — paint, cleaning, landscape, curb appeal
  • Skip the big-ticket investments that rarely return their cost
  • Price the home to acknowledge the remaining dated items
  • Provide clear disclosure about what has and hasn't been addressed

This approach captures the cost-effective upside of cosmetic work without the risk of over-investing in projects that don't return.

What Sellers Underestimate About This Decision

Two patterns worth flagging.

The emotional attachment to your improvements. Sellers who invest in updates often overvalue what they spent, expecting the market to reward every dollar. The market doesn't always agree. Some updates return 150 percent of cost. Others return 60 percent. Know the difference before spending.

The time cost of delayed listing. Every month you spend preparing is a month you're not on market. If prices are shifting, if seasonality matters, or if you have a specific deadline, the delay itself has a cost. Sometimes selling as-is now beats selling updated later.

Two Things I Tell Every Seller Deciding Between As-Is and Updates

First, get an experienced agent's honest walk-through before making decisions. A pre-listing consultation identifies which specific issues will affect your sale price and which won't. That conversation typically saves sellers thousands in avoided over-investment and pointed spending toward the changes that actually return.

Second, be honest about your capacity — financial and emotional. If you can't afford to do the work well, doing it poorly often makes the situation worse. Half-finished projects are worse than clear as-is presentations. If you're going to update, commit to doing it well. If you can't, price accordingly and go to market as-is.

Key Takeaways

  • Selling as-is doesn't skip disclosures — it signals you won't negotiate inspection repairs
  • As-is listings typically sell at a discount reflecting the buyer's post-closing investment expectation
  • As-is works when you need speed, lack cash for updates, target investor buyers, or the location dominates the home's value
  • Investing in updates makes sense when buyers in your price band expect finished condition, comparable inventory is updated, and you have time and cash to do the work well
  • Interior paint, deep cleaning, curb appeal, kitchen refresh, and bathroom refresh consistently return their cost
  • Full remodels, room additions, elaborate landscaping, and trendy choices rarely pay back
  • Higher price bands and luxury properties are especially hurt by as-is presentations
  • The middle-ground approach — high-ROI cosmetic work plus honest pricing on the rest — often delivers the best returns
  • Delayed listing has real cost; sometimes selling as-is now beats selling updated later
  • Get an experienced agent's honest walk-through before making the decision and be honest about your financial and emotional capacity

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 7, 2026

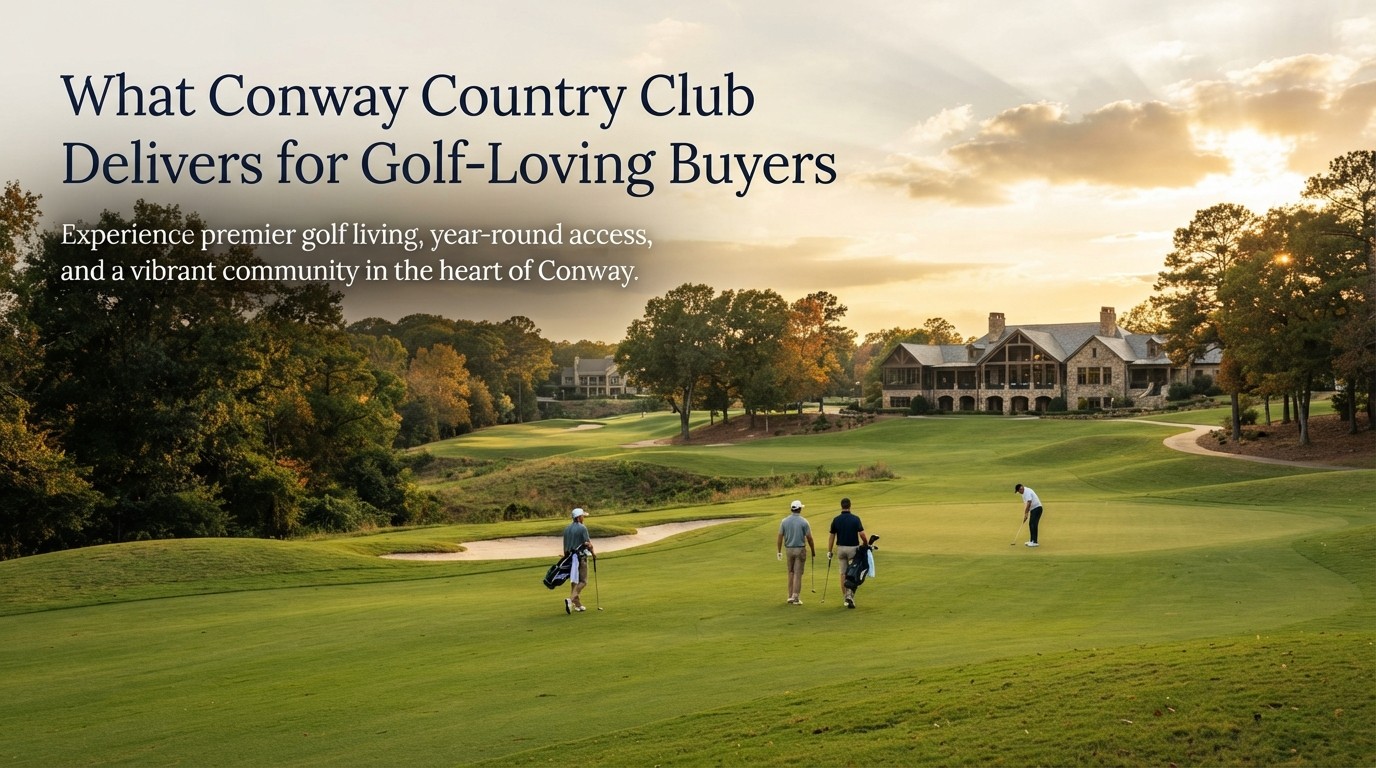
What Conway Country Club Delivers for Golf-Loving Buyers

You golf regularly and want a home that puts the course at the front of your daily life. On the Grand Strand there are only a few communities that actually deliver on that promise, and Conway Country Club is one of them. Here's the honest picture. It's not the flashiest golf community on the strand. It's not the largest. What it is, is one of the more established, quietly consistent golf-adjacent neighborhoods in the Conway market — and for the right buyer, that's exactly the point.

Why Conway Country Club Matters in This Market

The Grand Strand has dozens of golf courses. That doesn't mean every course-adjacent community is a good place to live. What separates a solid golf community from a marketing brochure is course stability, home quality, community identity, and the specific fit between the amenity and the residents.

Conway Country Club has held up in ways some other Grand Strand golf communities haven't. The course has stayed operating. The neighborhood identity has stayed intact. The homes have been maintained and updated by owners who genuinely wanted to live there rather than by flippers looking for a quick turn.

What Conway Country Club Delivers for Golf-Loving Buyers

Who Actually Buys Here

The Conway Country Club buyer pool has a few consistent patterns.

Retirees who golf regularly and want the course as their daily amenity, not a once-a-month feature. Living on or near the course means the golf lifestyle is embedded in daily life.

Snowbirds who spend fall through spring in Conway and want the golf-community setup that makes their winter months easy. Lock-and-leave friendly, active community, and a course they can actually play.

Full-time residents who value the established neighborhood feel and don't want the resort intensity of some larger golf communities further south.

Move-up buyers from other Conway pockets who want a lifestyle upgrade tied to the golf they already play.

What Makes the Community Actually Work

A few specific features that come up in almost every conversation with residents.

Established landscaping and mature trees. The community has been around long enough to feel like a real neighborhood, not a raw new subdivision.

Real course access. Homes here aren't just theoretically near the course — you can walk or drive a cart to the tee.

Manageable community scale. Small enough that neighbors know each other, big enough to have real community events and social structure.

A quieter version of coastal SC. You're 15-20 minutes from Myrtle Beach and 25 minutes from the actual ocean. Enough proximity to hit the beach when you want. Enough distance that daily life happens in a residential neighborhood rather than a tourist corridor.

What Golf-Focused Buyers Should Verify

Standard golf community due diligence applies here too.

The specific club membership structure. Some Grand Strand golf communities require mandatory club dues for all residents. Others make membership optional. Ask exactly what's required and what's optional at Conway Country Club before signing anything.

Course ownership stability. Ask about who owns the course, how the finances look, and whether there are any pending ownership changes. Course closures happen on the Grand Strand and they crush home values in the surrounding neighborhoods.

HOA reserves. Established communities can face capital projects — clubhouse updates, road resurfacing, pool renovation. A healthy reserve position means these projects don't hit you as special assessments.

Play volume. If the course is being played, it's staying profitable. If it's empty on weekends, that's a sign to ask harder questions.

For broader inventory across Conway's golf-oriented options, browse Conway golf course homes alongside Conway Country Club to see how the market looks in your price range.

The Golf Cart Question That Matters

Not every Conway neighborhood is golf cart friendly. Some are. Some aren't. If you plan to use a golf cart around your neighborhood — not just on the course — check the specific rules before you commit. Golf cart friendly neighborhoods in Conway lists the specific communities that support the golf cart lifestyle beyond just course access. Conway Country Club has the pieces that support this kind of daily use, but confirm the specifics for your particular street.

What Conway Country Club Homes Look Like

The inventory here isn't cookie-cutter. Homes range from established mid-tier options that have been owned by the same family for years to updated properties refreshed for modern buyers to occasional luxury builds. If you're looking at the higher end of the Conway market, Conway luxury homes often includes properties in this pocket, alongside other high-end Conway options.

What consistently sells fastest here: well-maintained homes with course frontage or short-walk-to-tee access, updated kitchens, first-floor primaries, and outdoor space that leverages the course view.

What Golf Community Buyers Underestimate

Two patterns worth flagging.

The maintenance load on golf-adjacent homes. Mature landscaping needs care. Windows in course-facing homes get more attention. Balls hit windows, sprinklers overspray, and cart paths need occasional adjacent maintenance. Budget for these realities.

Club dues if applicable. If the community includes required club membership, factor that into your total monthly carrying cost. It can add meaningfully to what your monthly ownership actually costs.

Two Things I Tell Every Conway Country Club Buyer

First, play the course before you buy. Sounds simple. Almost no buyers do it. Renting a cart and playing 18 tells you more about the course quality, the resident engagement, and whether the amenity you're paying for actually matches what you want than any marketing tour ever will. Play first.

Second, talk to a current resident about their annual budget. HOA dues, club fees, cart fees, and incidental charges add up in ways brochures don't fully capture. Fifteen minutes with a neighbor gives you the real number, and the real number often changes how you underwrite the purchase.

Key Takeaways

  • Conway Country Club is one of the more established, consistent golf communities on the Grand Strand — quieter than resort-scale alternatives but reliably solid
  • The buyer pool includes retirees, snowbirds, full-time residents, and move-up golfers from other Conway pockets
  • Established landscaping, real course access, manageable community scale, and quieter coastal SC positioning are the specific value drivers
  • Verify club membership structure, course ownership stability, HOA reserves, and play volume before committing
  • Conway Country Club supports golf cart use for buyers who want that lifestyle beyond just course access
  • The inventory ranges from established mid-tier homes to occasional luxury builds; well-maintained properties with course frontage sell fastest
  • Budget for golf-adjacent home maintenance and any required club dues in your total carrying cost
  • Play the course before you buy and talk to a current resident about their real annual budget

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle
Sept. 4, 2026

Move-Up Neighborhoods in Conway for Growing Families

You outgrew your first Conway home about a year ago and now you're seriously shopping the next one. Here's the truth. Conway has a specific band of move-up neighborhoods that consistently work for families in your position — more space, better lot, real character, and prices that still make sense. Communities like Bucksville Oaks come up in almost every conversation I have with growing families. Let me walk you through the neighborhoods where move-up buyers actually land and why each one fits a specific kind of family.

What Move-Up Actually Means for Conway Families

Move-up doesn't just mean bigger square footage. For most families I work with it means: more bedrooms for growing kids, a real yard the whole family can use, a school zone the family wants, a home office or two, and enough storage that the garage isn't full of boxes six months after moving in.

The move-up buyer usually has equity from a starter home to bring to closing. That equity opens options that don't work at the first-time buyer level. It also raises the bar on what buyers expect from the next home.

Bucksville Oaks for Established Family Character

Bucksville Oaks delivers what a lot of Conway move-up families want. Mature trees. Established landscaping. Homes that have been lived in and maintained. The neighborhood has settled into itself — the character is real and can't be manufactured in a newer subdivision. Buyers who want a family neighborhood with soul rather than the anonymous feel of some newer builds consistently land here.

Midtown Village for Modern Family Layouts

Not every move-up family wants an older home. Plenty want newer construction with contemporary floor plans that match how modern families actually live. Midtown Village hits that need. First-floor primary suites, real home offices, updated kitchens, and layouts that flow instead of chopping the house into disconnected rooms. Move-up families relocating from the Northeast or Midwest often gravitate here because the homes match what they had in their previous market at a friendlier price.

Beach Gardens for Established Neighborhood with Room

Beach Gardens sits in a settled Conway pocket with real neighborhood identity. Move-up families who value being able to walk to a friend's house down the street, who want their kids to play in yards visible from the porch, and who prioritize community over the newest amenities often thrive here. The homes range from solid mid-tier options to larger properties for families ready for a real step up.

Briarfield for Space and Privacy

Briarfield attracts move-up buyers who want more separation from neighbors than tight subdivisions provide. Larger lots, more privacy, and homes with the kind of setback that makes the property feel like your own space. If you're moving up specifically to get away from a fence-line neighbor situation, this is where a lot of families land.

 Move-Up Neighborhoods in Conway SC for Growing Families

The 4-Bedroom Sweet Spot Near Conway Elementary

For families whose kids are or will be in the Conway Elementary attendance zone, the four-bedroom inventory near the school is worth focused attention. I keep a running list of 4-bedroom homes near Conway Elementary School because so many move-up families want that specific combination — enough bedrooms for growing family plus the specific school zone. When the right property comes up in this niche, it typically doesn't sit long.

Historic Conway for Character-Focused Families

Some move-up families don't want a newer subdivision at all. They want the character, sidewalks, and community of the historic downtown Conway district. Homes there range from character cottages that need attention to fully renovated period homes with modern systems. Families who choose this route usually value walkable neighborhoods over larger yards and accept that historic homes come with a real maintenance load.

What Move-Up Families Should Actually Prioritize

A few things I push every move-up buyer to think through before falling in love with a specific home.

The school attendance zone by exact street address. Community names don't always match zones. Confirm through Horry County Schools before writing the offer.

The specific bedrooms your growing family will need in five and ten years, not just today. Kids get bigger. They want their own space. The extra bedroom or the flex room becomes more valuable over time.

Home office space if either parent works from home. The move-up home should support how the family actually lives, not just how they lived in the starter.

Outdoor space that fits the family's actual outdoor life. Trampolines, pools, gardens, dog runs, playhouses — the yard should support how your kids will actually use it.

The realistic commute at rush hour. Not the GPS estimate. The actual timing during the school year.

What Move-Up Families Underestimate

Two patterns I watch consistently.

The cost of scaling up. Bigger home means bigger utility bills, more furniture to buy, more square footage to maintain, and often more HOA responsibilities. Move-up families sometimes budget for the mortgage payment but not for the fuller carrying cost.

The emotional attachment to the starter home. Selling the first home is often harder than families expect. Build in some time to process that transition rather than rushing straight from closing to move-in.

For broader Conway market context alongside these specific neighborhoods, browsing Conway real estate inventory helps families see what's on the market at their target price point.

Two Things I Tell Every Move-Up Family in Conway

First, sell before you buy if you can. Move-up families who try to buy first and sell later often end up stretched thin financially and stressed by two simultaneous transactions. The families who sell first, live in temporary housing for a few weeks, and then buy calmly consistently make better decisions and end up in better homes.

Second, don't skip the pre-listing prep on your current home to save time. The proceeds from your starter home directly fund your move-up. Sellers who invest in prep and marketing on the starter typically walk away with more equity to bring to the next purchase. That equity difference can be the gap between the home you want and the home you settle for.

Key Takeaways

Conway offers a specific band of move-up neighborhoods that consistently work for growing families. Bucksville Oaks delivers established character with mature landscaping for buyers who want neighborhood soul. Midtown Village provides newer construction with modern family layouts and floor plans that match how families actually live today. Beach Gardens combines settled neighborhood identity with real yard space. Briarfield attracts families wanting privacy and separation from tight subdivision feel. The 4-bedroom inventory near Conway Elementary is a specific niche worth focused attention for families in that attendance zone. Historic downtown Conway serves families who prioritize character and walkability over larger yards. The move-up decisions that consistently work involve verifying school zones by exact address, prioritizing homes that fit five-to-ten-year family needs rather than just today's, and building in real outdoor space and home office capacity. Selling the starter home before buying the move-up, and investing in real pre-listing prep on the starter, are the two seller-side decisions that most directly determine how much equity families bring to the next purchase — and how happily they land in it.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Sept. 3, 2026

Neighborhoods Near Coastal Carolina University Worth a Look

You're shopping for a home within a reasonable drive of Coastal Carolina University and the standard advice keeps pointing you at the same handful of subdivisions. Let me expand your list. The CCU-adjacent map has more good options than most buyers realize, and a few pockets — like Aquila Estates — quietly work better than the marketing suggests. Whether you're a parent buying for a student, a faculty member looking for a short commute, or an alumnus who wants to stay close to the school after graduating, here's what to actually consider.

Why CCU Shapes the Housing Map

CCU sits off Highway 544 on the south side of Conway. That single location shapes a lot of the housing decisions buyers make around it. The corridors between the campus and Highway 501 attract buyers who want a quick drive to class or the office. The corridors north of the university appeal to full-time residents who value CCU's presence without living directly in it. Understanding the geography helps you know which neighborhood actually fits your daily rhythm.

Aquila Estates for Newer Construction Close to Campus

Aquila Estates delivers a specific value proposition — newer construction within short driving distance of CCU, at price points that keep the mortgage math reasonable for parent buyers and younger faculty. What buyers respond to here: modern layouts, real home offices, first-floor primary suites in many builds, and predictable HOA amenities. If you want a house that's already set up for how people actually live in 2026, this is one of the better options.

Pecan Grove for Established Neighborhood Feel

Not every buyer wants brand-new construction. Some want mature trees, established landscaping, and a neighborhood that's been settled long enough to feel like a real place. Pecan Grove hits that specific note. Homes here have been lived in, updated, and cared for by multiple owners. The community identity is real. For faculty and alumni buyers who value neighborhood over new, this is worth a serious look.

Pottery Landing for Waterway Access and Character

Here's a pocket most CCU-area buyers don't fully consider. Pottery Landing combines proximity to the university with real character that newer subdivisions can't match. The homes are distinctive. The lots have depth. Buyers who prioritize the specific home over the specific community often end up here after touring the more marketed options and realizing they wanted something more.

Condos for Students, Downsizers, or Investors

Not everyone wants a house. Conway condos for sale serve several CCU-related buyer types. Parents buying for students who'll live there four years and either sell or hold as a rental afterward. Downsizing retirees who want a lock-and-leave setup. Investors looking for rental income tied to the university's student and faculty population. Each has a different sweet spot within the condo inventory. Parents typically want durable, simple layouts. Retirees want amenity access and predictable HOA. Investors want the specific units with strong rental history.

Conway Country Club and Golf-Adjacent Living

For buyers who golf regularly and want to live near CCU, the Conway Country Club corridor delivers something specific. Golf access, established community feel, and location that still puts you within reasonable range of the university. Faculty golfers, retired alumni, and buyers who want a lifestyle amenity beyond just a house often land here.

The Historic Conway Downtown Option

Don't rule out the historic district. It's a 10-15 minute drive from the university, close enough that faculty and staff can live there comfortably, and the neighborhood character is something you can't manufacture in a modern subdivision. Walk to Main Street. Bike to the Riverwalk. Live in a real downtown instead of a suburban approximation of one. For CCU-adjacent buyers who value walkable neighborhood over parking-lot proximity, this is a real option that gets overlooked because it's not immediately next to campus.

 Neighborhoods Near Coastal Carolina University Worth a Look

What CCU-Area Buyers Should Verify

Standard due diligence with a few CCU-specific twists.

Rental rules in the specific community. If you're a parent buying with the intent to rent the property after graduation, or an investor buying for student rentals, verify the HOA and municipal rules before writing an offer. Some communities allow rentals freely. Others have caps or restrictions that limit your options.

Commute to campus at the specific time you'll actually make the drive. Highway 544 traffic on game weekends, academic drop-off, and daily commute hours can vary meaningfully.

Internet by exact address if you have students or remote workers who need reliable connections.

Insurance quotes. Coastal SC insurance realities apply even inland, and the layered coverage still matters.

School attendance zones if you're a family buyer with school-age children. Community names don't always match school zones.

What CCU-Area Buyers Underestimate

Two things I watch play out consistently.

Game weekend impact. Home football and baseball weekends genuinely change the neighborhood dynamics near campus. Streets close. Traffic backs up. Parking gets creative. Some buyers love the energy. Others find it more disruptive than they expected.

The rental cycle if you're using the property that way. Student leases run with the academic calendar. If you close on a rental property in November, you may sit empty until August. Build that into your underwriting.

Two Things I Tell Every CCU-Area Buyer

First, visit the neighborhood at academic hours and at game hours before committing. Tour on a Tuesday morning during a school week and a Saturday morning during a home game. The two experiences tell you different things about how the neighborhood actually functions. Buyers who see both make much better decisions than buyers who only visit once.

Second, if you're a parent-buyer using this as student housing, don't underestimate the maintenance. Student-occupied homes wear faster than owner-occupied. Floors take more abuse. Appliances break more often. Build a higher maintenance reserve into your ownership numbers.

Key Takeaways

  • CCU-adjacent housing offers more good options than the standard marketed list suggests
  • Aquila Estates delivers newer construction close to campus at family-friendly price points
  • Pecan Grove provides established neighborhood feel with mature landscaping for buyers who value community over new
  • Pottery Landing offers distinctive character and Waterway-adjacent lots for buyers who want something beyond typical subdivision inventory
  • Conway condos serve parent buyers, downsizers, and investors with different sweet spots by unit type
  • Conway Country Club delivers golf-adjacent living for buyers who want a lifestyle amenity beyond the house itself
  • The historic Conway downtown is a genuinely walkable option 10-15 minutes from campus that gets overlooked
  • Verify rental rules, actual commute time, internet, insurance, and school zones by exact address before writing an offer
  • Game weekends and student-tenant maintenance loads are the two items CCU-area buyers most often underestimate

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle