Conway SC Real Estate Blog

Century 21 McAlpine Blog

Neighborhood guides and insights from local Realtors on buying and selling homes in Conway, Aynor, Loris, Longs and across the Grand Strand. Have a question about a home or the market? We're happy to help.

Oct. 16, 2026

Why Buyers Love Market Common in Myrtle Beach

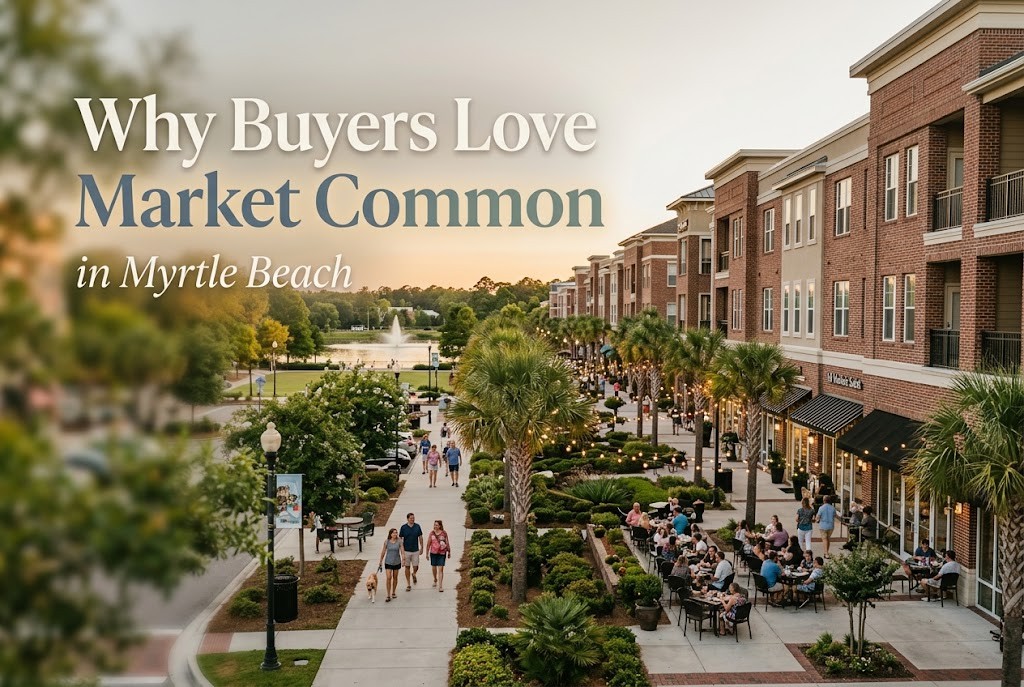
If you want to live in Myrtle Beach but you'd rather walk to dinner than drive, Market Common is where you look first. Built on the old Myrtle Beach Air Force Base, the neighborhood ignores the usual Grand Strand pattern of highway-and-strip-mall development and gives you something closer to a real town square. Buyers who end up here almost always say the same thing after a few months: they didn't realize how much they wanted this until they tried it.

What Market Common Actually Is

Market Common is a mixed-use neighborhood just inland of the beach, built around a walkable commercial core with shops, restaurants, a movie theater, a weekly farmers market, and public green space. Residential sits around and above the commercial district — condos over storefronts, townhomes on tree-lined streets, single-family homes within a short walk of the center. Grand Park and Valor Park anchor the open space side, and the Myrtle Beach State Park and the beach itself are a short drive out.

The scale matters here. Market Common isn't a strip of shops with houses nearby. It was planned as a neighborhood from day one, with sidewalks, bike paths, and streets designed to slow cars down.

Why Walkability Is the Whole Point

Here's the thing about most of Myrtle Beach — the lifestyle is beach-and-car. You drive to the sand, you drive to dinner, you drive to the grocery store. Market Common breaks that. Residents walk to coffee in the morning, to the farmer's market on Saturday, to a show at the theater, to Grand Park with the dog. That daily rhythm is why so many retirees and remote workers pick this neighborhood over oceanfront condos. The beach is still a ten-minute drive. But most of life happens on foot.

Who Thrives Here

Retirees who want a walkable base. Remote workers who need coffee shops and dinner options without a car. Families who want their kids to have a place to ride bikes safely. Buyers coming from northeastern towns with walkable downtowns who don't want to lose that lifestyle just because they moved south. What I see consistently with Market Common buyers is that they tour the neighborhood once, go home to think, and come back ready to write. The format sells itself.

The buyers who don't love it are usually ones who wanted direct oceanfront and tried to compromise on inland walkability instead. If beach access every morning is the point of your move, this isn't the right fit.
Why Buyers Love Market Common in Myrtle Beach

Housing Options Inside Market Common

The housing mix is wider than most Grand Strand neighborhoods. Condos over the commercial core run smaller and give you true walk-to-everything life. Townhomes on streets like Howard Avenue, Nevers Street, and Bellamy Avenue sit in the middle on price and give you a small yard with the walkability still intact. Single-family homes in sections like Sweetgrass Square and The Reserve at Market Common sit a few blocks out, with more land but a longer walk to the center.

Price points cover a wider band than people assume. Entry-level condos stay reasonable, and the higher end of the single-family inventory moves into premium territory. If you want to see where mid-range Myrtle Beach homes cluster for comparison, our mid-band price page is a good starting point.

What Residents Actually Do on a Normal Week

Monday morning coffee at a sidewalk cafe. Lunch meetings at a dozen restaurants within a five-minute walk. Weekly farmers market on Saturday morning. Live music nights in the warm months. Movie theater in the center for a rainy afternoon. A short drive out to the beach when you want sand under your feet. Dinner options that rotate — residents here develop favorites but rarely eat the same place twice in a week.

What people underestimate is how much the social fabric forms around the walkability. Neighbors run into each other at the coffee shop, at the park, at the grocery store. That's how friendships form here faster than in car-dependent neighborhoods.

The Trade-Offs to Know Before You Buy

Nothing is perfect. Market Common has busier weekends and peak-season weeks when tourists find their way in — especially for the farmer's market and holiday events. HOA fees in some sub-communities are higher than inland Myrtle Beach alternatives. Condo buildings in the walkable core can carry noise from the commercial activity below — nothing extreme, but something to notice if you're a light sleeper. And if you need serious boat storage or want a four-car garage, this isn't the format for you.

The buyers who do best here tour at different times of day, walk the specific blocks they'd actually live on, and talk to residents at the coffee shops before writing an offer.

How It Compares to Other Myrtle Beach Options

Oceanfront gives you direct beach but no walkable commercial life. Grande Dunes gives you resort amenities but you drive to everything outside the gates. Carolina Forest gives you suburban space and schools but no neighborhood center. Carolina Forest and Conway trade walkability for more land and lower price per square foot. Market Common is the only Myrtle Beach neighborhood built from the ground up as a walkable mixed-use center. If walkability matters to you, it's the pick.

Key Takeaways

Market Common gives Myrtle Beach buyers something no other local neighborhood does — a true walkable mixed-use center where daily life happens on foot. It fits retirees, remote workers, and families who want sidewalks and community character over car-dependent beach living. Housing ranges from condos over the commercial core to single-family homes a few blocks out, with HOA fees that reflect the amenity picture. Tour the neighborhood at different times, walk the specific streets you'd live on, and talk to residents before you write.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Buyers, Lifestyle
Oct. 15, 2026

Myrtle Beach Golf Communities Worth Exploring

Myrtle Beach has close to a hundred golf courses and the brochures treat them all like they're interchangeable. They aren't. If you're buying a home in a golf community here, the course is almost beside the point — the community around it is what you're actually buying into. Here's what separates the Grand Strand's real golf communities from the ones that just have a course nearby.

Grande Dunes — The Luxury Benchmark

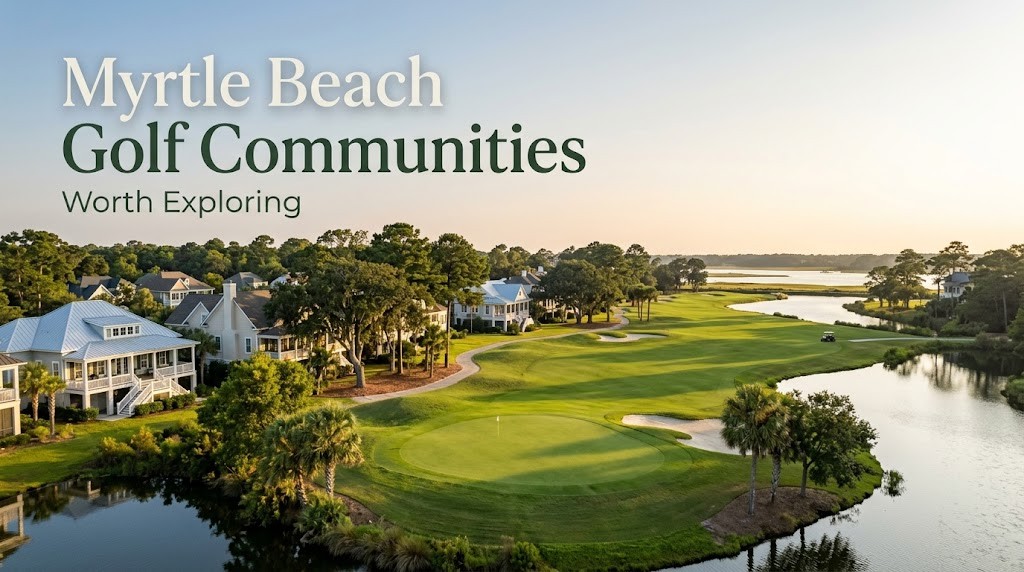
Grande Dunes sits along the Intracoastal Waterway and takes up a sizable chunk of the north Myrtle Beach area. The community has two courses — the Resort Course and the Members Club — and the Members Club is one of the few true private clubs in the market. Grande Dunes also has a Marina Village, a Mediterranean-style community center, oceanfront amenities, and some of the most consistent price appreciation in Myrtle Beach. Buyers coming here are usually looking for a full lifestyle package, not just a course to play.

What I see consistently with Grande Dunes buyers is that they're buying the community first, the course second. The resale value tracks the amenity picture more than the fairway condition.

Pine Lakes — The Grand Daddy with Established Charm

Pine Lakes is where the Grand Strand's golf story really started — the original Myrtle Beach course, opened in 1927, is here. The community around it has mature trees, lower-density housing, and homes that run the range from mid-market to legacy properties. The vibe is quieter and more residential than resort-style. Buyers who want a golf course address without the tourist flow often land here.

Myrtlewood — Central Location, Two Courses, Good Value

Myrtlewood sits inland from the strip, with two courses (Palmetto and Pinehills) and a mix of condos and single-family homes. The community gives you a central location, workable prices for a golf-adjacent lifestyle, and reasonable HOA fees. It's not oceanfront, it's not ultra-luxury — it's a solid middle lane for buyers who want to play regularly without buying into a resort premium.

TPC Myrtle Beach — Serious Course, Specific Buyer

TPC Myrtle Beach is one of the top-rated public courses in the state and the community around it draws buyers who want that caliber of golf as a daily option. Housing stock here is newer and higher-end than Myrtlewood, and the pace is quieter than resort communities closer to the beach. If golf is the point of the move, TPC is worth touring.

Myrtle Beach Golf Communities Worth Exploring

Legends Resort — Three Courses and a Village Feel

Legends sits inland, has three distinct courses (Heathland, Moorland, Parkland), and feels more like a self-contained village than a subdivision. The homes range from villas and condos to larger single-family houses. Price points work for a lot of retiree budgets, and the course variety keeps a daily player interested year-round.

Barefoot Resort — North of Myrtle Beach, Four Courses

Technically in North Myrtle Beach, Barefoot gives you four courses designed by big names (Love, Fazio, Norman, Dye), a yacht club, and a mix of condos, townhomes, and single-family homes. Buyers drawn to North Myrtle Beach for the beach-plus-golf lifestyle often start here. It's one of the few communities in the market where you can realistically play a different course every day of the week without leaving home base.

Caropines, Blackmoor, and the Secondary Tier

Beyond the headline communities, there's a secondary tier worth knowing about — Blackmoor over in Murrells Inlet, Caropines in Surfside, International Club in Murrells, Tradition Golf Club in Pawleys. These are usually quieter, less amenity-heavy, and priced below the headline communities. They're worth touring if you want golf course access without the resort infrastructure or price point.

How to Pick the Right One

Three questions sort most buyers quickly. One: do you want a resort feel with amenities and seasonal buzz, or a quiet residential neighborhood that happens to have a course? Two: how important is private vs. semi-private vs. public club access? Three: how far from the beach do you want to be? Grande Dunes and Barefoot give you water-close options. Legends, TPC, and Myrtlewood are inland. Pine Lakes and Myrtlewood sit in between.

Walk the community during peak season and off-season. HOA documents, cart path condition, course maintenance, and clubhouse condition tell you more than any marketing site. If you want golf-course homes beyond these headline communities, our Conway golf-course homes list is a good starting point for the inland tier.

Key Takeaways

Myrtle Beach golf communities aren't interchangeable — Grande Dunes, Pine Lakes, Myrtlewood, TPC, Legends, and Barefoot each attract a different buyer for different reasons. Grande Dunes leads on luxury and amenities, Pine Lakes on charm and legacy, Myrtlewood on value and location, TPC and Legends on course quality, Barefoot on course variety. Decide whether you want a resort or a residential community, how important private membership is, and how close you need to be to the beach, then walk the community in different seasons before you commit.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Buyers, Lifestyle
Oct. 14, 2026

Why Buyers Love Coastal Luxury Living in Myrtle Beach

Coastal luxury in Myrtle Beach doesn't look like coastal luxury in Palm Beach or Naples, and that's part of the appeal. Buyers moving here from higher-priced markets consistently tell me the same thing: the money goes further, the lifestyle is less performative, and the real amenity is the water itself. Here's what luxury actually means in this market, and why the buyers who move here tend to stay.

Luxury in Myrtle Beach Means Four Different Things

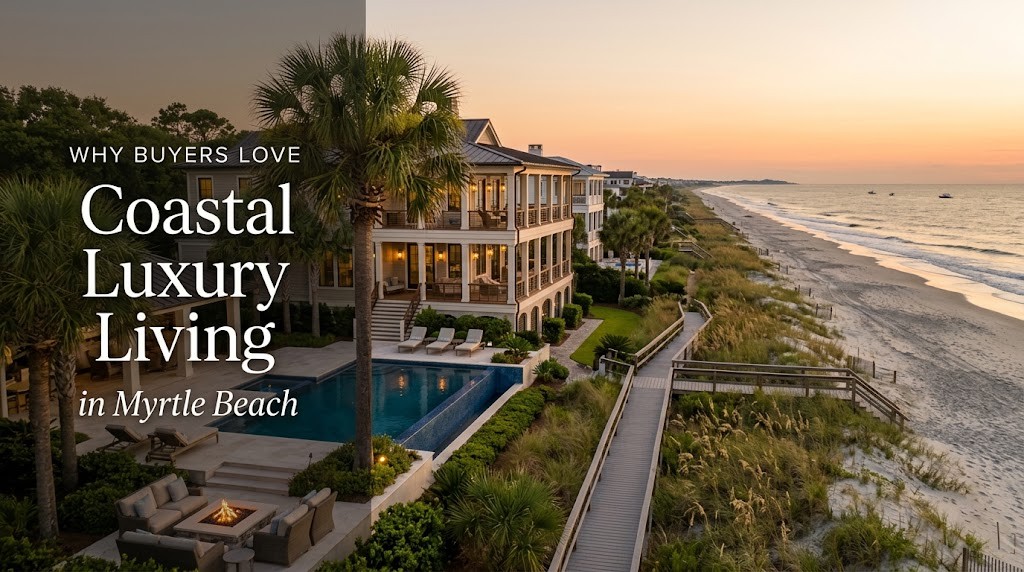
The word gets thrown around loosely, so let's split it. Oceanfront luxury — direct beachfront homes and penthouse condos. Waterway luxury — estates and boat-access homes along the Intracoastal and connecting river systems. Private club luxury — Grande Dunes Members Club and similar gated communities built around a serious golf course. Resort luxury — higher-end properties inside amenity-heavy communities like Grande Dunes and Barefoot Resort. Each tier draws a different buyer and holds value for different reasons.

Buyers who confuse these tiers tend to overpay for one feature while missing the one they actually wanted. The oceanfront buyer who really wanted private club access ends up disappointed. The private club buyer who missed the water access regrets it after year one.

Oceanfront Is the Headline, But Not Always the Right Pick

Direct oceanfront commands a real premium — and for the right buyer, it's worth every dollar. Waking up to the Atlantic, walking down to the sand in slippers, watching storms roll in from the deck — nothing substitutes for it. The trade-offs are real though. Insurance stacks hard, salt air works on finishes, HOA dues on oceanfront condos run higher than most inland buyers expect, and short-term rental activity in some buildings can make day-to-day living feel more hotel-adjacent than residential.

The oceanfront buyers who thrive here are the ones who actually use the water. The ones who buy for the view and rarely leave the house usually sell within three years.

The Waterway Tier Keeps Underwriting Itself

Homes along the Intracoastal Waterway, the Waccamaw River system, and the canals in Cherry Grove and Little River have quietly outperformed most other tiers in appreciation over the last decade. Boat access, protected water, lower insurance exposure than direct oceanfront, and privacy you can't get on the beach. Grande Dunes along the ICW is the headline neighborhood. Smaller enclaves along the Waccamaw north of Conway and the canals south of Little River are the sleepers.

What I see consistently is that waterway buyers skew long-term. They settle in, buy a boat, join a marina, and don't sell for a decade. That stability keeps supply tight and prices firm.

Why Buyers Love Coastal Luxury Living in Myrtle Beach

Private Club Luxury Trades Features Oceanfront Can't

Private club communities like Grande Dunes Members Club and higher-end sections of Pine Lakes trade features oceanfront buildings don't offer — private golf, resident-only amenities, controlled membership, and a social fabric that forms around the club. For buyers moving from established country-club markets up north, this is often the piece they were hunting for. The tier draws a different demographic than oceanfront — often older, more residential, less seasonal.

Resort Luxury Combines Amenities With Beach Access

Resort-style luxury communities — Grande Dunes as a whole, Barefoot Resort in NMB, Dunes Golf and Beach Club — give buyers the full package. Clubhouse, pools, oceanfront amenities (via community beach clubs in some cases), gated privacy, high-end dining nearby, and golf. Price points typically run between pure oceanfront and traditional private club communities. The lifestyle is more active than private club, less exposed than oceanfront.

Price Bands and What They Actually Buy

Luxury in Myrtle Beach starts earlier than most migrating buyers assume. Resort and waterway luxury runs well into seven figures but opens below many comparable coastal markets. Oceanfront moves higher, with premium direct beachfront reaching deep into the eight figures for the top tier. Private club entry points vary widely by community. Buyers moving from New York, Boston, or Northern California frequently remark that their current home's price would buy multiple homes here — and they're not exaggerating.

If you want to walk the price bands yourself, start with the mid-range Myrtle Beach price band page and work up to see what each tier delivers.

The Lifestyle That Keeps Buyers Here

Coastal luxury buyers don't stay for one thing — they stay for the combination. Year-round golf. Boating on the ICW. Oceanfront dining. Short flights from Myrtle Beach International. Lower state income tax than many of the markets they came from. Mild winters. A healthcare system that's grown substantially over the last decade. For retirees and second-home owners, that stack is hard to beat.

Here's what nobody tells you until you move: the social scene in these communities is more welcoming than most newcomers expect. Private clubs here aren't the gatekept rooms of older money markets. New residents get introduced quickly, which is why the migration out of this market is low once people settle.

Who Should Actually Buy Luxury Here

Buyers who want ocean, boat, golf, or private club access as a daily reality. Buyers who've lived in high-tax northeastern markets and want a lifestyle upgrade at a lateral or lower monthly cost. Second-home owners from the Carolinas, the Northeast, and the Midwest who want warmer winters without going as far as Florida. The buyer who thinks they want a trophy address but will never use the water usually doesn't love it here — and that's okay. The buyers who come for the lifestyle itself consistently outperform their own expectations.

Key Takeaways

Coastal luxury in Myrtle Beach splits into four distinct tiers — oceanfront, waterway, private club, and resort — and each one attracts a different buyer for different reasons. Oceanfront commands the headline premium but demands a buyer who actually uses the water. The waterway tier (Grande Dunes along the ICW, Cherry Grove canals, Waccamaw River) quietly outperforms on long-term appreciation. Private club and resort communities trade different features that oceanfront can't deliver. Pick the tier that matches how you'll actually live, not the one with the loudest marketing.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Buyers, Lifestyle
Oct. 13, 2026

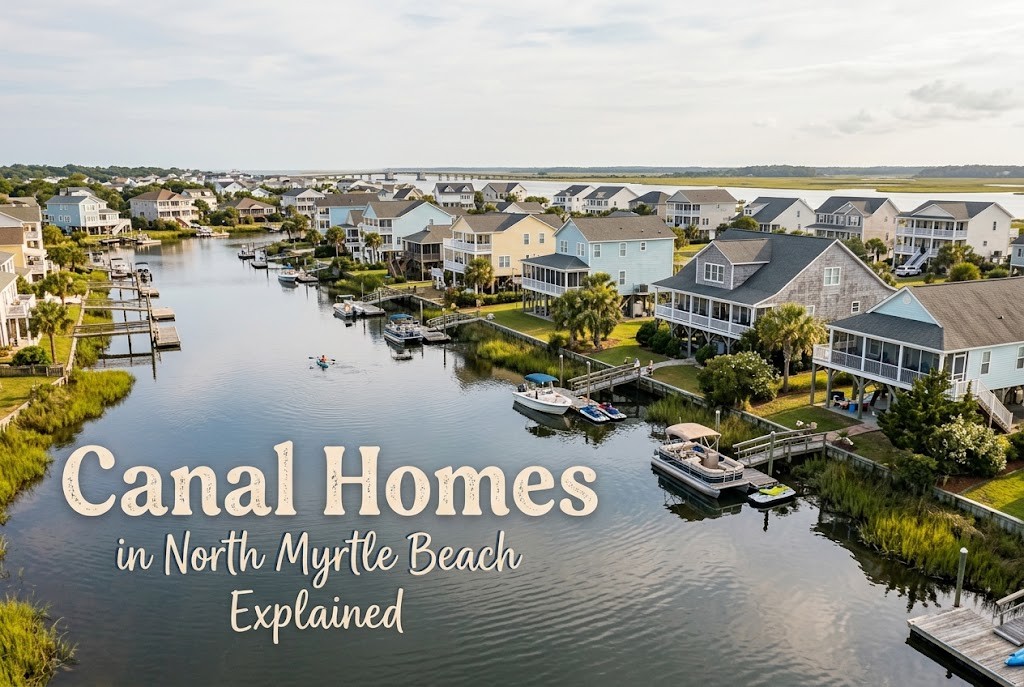
Canal Homes in North Myrtle Beach Explained

Canal homes in North Myrtle Beach — especially the channels in Cherry Grove — are one of the Grand Strand's quietest success stories. They give you backyard boat access, a protected waterway for fishing or paddling, and a lifestyle that direct oceanfront can't match. But they also come with specifics that trip up buyers coming from inland or from pure beach markets. Here's what to know before you tour one.

What a Cherry Grove Canal Actually Is

The channels through Cherry Grove run inland from the ocean through a grid of residential streets. Each canal connects back to the ocean through a system that eventually meets the Atlantic. Most homes along the canals have private docks, many have boat lifts, and the water in the canals rises and falls with the tide. Boats on lifts stay dry at high tide and sit on the lift above the mud flats at low tide. That tidal rhythm is the first thing inland buyers underestimate.

What I see consistently is that out-of-state buyers tour a canal home at high tide, fall in love with the view, and don't come back at low tide to see what the same view looks like with mud showing. Visit twice before you offer.

What the Tides Mean for Daily Use

You can't launch or dock a boat at any time you want. Low tide limits usable water depth for powered boats, especially larger ones. Owners learn the tide chart quickly — most Cherry Grove boaters plan trips around the two high tides per day. If you want unrestricted boat access at any hour, the Intracoastal Waterway homes in Little River or around Myrtle Beach give you more depth. If you accept the tide schedule, canal homes give you a quieter, more private boating experience than the busier ICW.

Kayaks and small jon boats handle lower water better than inboards or heavier center consoles. If you're buying for small-boat and fishing use, the tide picture is less restrictive.

Boat Lifts, Docks, and What to Inspect

Most Cherry Grove canal homes include a private dock, and many include a boat lift. These structures are serious investments and serious maintenance items. Pilings rot, dock boards warp, lift motors fail, and lift cables need periodic replacement. Before you offer, hire an inspector who specifically evaluates docks and lifts, not just the house. The inspection cost is minor compared to the replacement cost of a failed lift or rotted piling.

Also check the dock permits. Horry County and the SC Department of Health and Environmental Control have rules about dock dimensions, dolphin pilings, and lift installations. A dock that was built outside current rules may be grandfathered but may not be legally expandable or replaceable. Confirm what the dock is legally allowed to be before you factor it into value.

 Canal Homes in North Myrtle Beach Explained

Flood Zones and Insurance Realities

Canal homes sit in flood zones. Period. Most are coded AE under FEMA, which means flood insurance is required for any mortgage and strongly recommended even for cash buyers. Premiums depend on elevation certificate, year built, and whether the structure meets current flood construction standards. Older raised homes may qualify for better rates than slab-on-grade homes built below current base flood elevation. Pull the elevation certificate during due diligence — it changes the premium conversation.

Wind and hail insurance is separate, and canal homes near the ocean face premiums comparable to oceanfront. The SC Wind and Hail Underwriting Association is still an option for homes the private market won't touch. Price insurance before you fall for a specific property, not after.

Which Canals Hold Value Best

Not all canals are equal. The channels closer to the ocean inlets with deeper water hold value better than canals that get shallow at the end of the system. Canals with newer homes, well-maintained docks, and consistent elevation above the flood threshold outperform canals with mixed-age housing and visible flood history. Streets like 48th, 49th, and 50th Avenue North near the ocean end have been consistent long-term performers. Interior canals further from the ocean inlet can be excellent values but require more careful tide analysis.

Buyers who do best here walk the specific canal, talk to two or three neighbors, and ask about the last significant flooding event. Local history matters.

What You Get That Oceanfront Can't Give You

Privacy. Backyard water. No sand tracking into your living room. Lower HOA (most canal homes aren't in HOAs at all). Boat access from your own property. A different pace than beachfront condo life. Fishing from your dock. Dolphins and manatees in the canals seasonally. A real neighborhood where kids ride bikes and residents know each other.

Here's what nobody tells you until you move in: the sound of a canal at night — small waves against pilings, pelicans, the occasional boat engine — is one of the quiet reasons residents don't want to leave once they settle.

Who Should Actually Buy a Canal Home

Boaters, fishers, retirees, and families who want the water lifestyle without the exposure or crowds of direct oceanfront. Investors who understand the specific flood and tide picture. Second-home owners who use the home at least seasonally. The buyer who should probably not buy is the one who wanted oceanfront and settled for a canal without understanding the differences. Those sellers typically relist within three years.

Key Takeaways

Cherry Grove and other North Myrtle Beach canal homes trade oceanfront exposure for backyard boat access, privacy, and a quieter waterfront lifestyle, but they come with tide schedules, flood zones, dock inspections, and specific insurance realities buyers need to understand up front. Visit at both high and low tide, pull the elevation certificate, hire a dock-and-lift inspector, and price insurance before you offer. The canals closer to deep water with newer homes and good elevation hold value best, and the buyers who thrive here want the water lifestyle without the oceanfront premium.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Posted in For Buyers, Lifestyle
Oct. 12, 2026

Pre-Listing Photography Prep for Coastal SC Sellers

The photos your Conway or Myrtle Beach home shows online decide whether buyers click on your listing or scroll past it. That means the two hours before the photographer arrives are some of the most profitable work you'll do in the entire sale. Here's the prep playbook I run with my coastal SC sellers before shoot day, including the pieces that are specific to the Grand Strand and don't show up in generic staging advice.

Why This Matters More on the Coast Than Inland

Buyers shopping coastal homes are often doing it from several states away. Many will never set foot inside your house until the inspection — they'll decide to write an offer entirely from photos, maybe a video walk-through, and the agent description. If a Charlotte buyer is comparing your Little River listing to three others at the same price, the one with the best photos wins the showing. The one with weak photos never gets considered.

What I see consistently with Grand Strand listings is that the first-week showings and offers correlate directly with photo quality, not price. Clean up the photos and the showing calendar fills.

Pre-Listing Photography Prep for Coastal SC Sellers

The Day-Before Checklist

Twenty-four hours before the shoot is the right window. Not the morning of. You want time to catch problems and fix them. Walk every room with a clipboard and look at it the way a buyer would through a camera. The things that live in your blind spot — the magnets on the fridge, the piles of mail on the counter, the kids' art on the walls — those are the first things buyers see.

Clear every counter in the kitchen except two items. Clear the master nightstand except for a lamp. Hide the trash cans. Pack up personal photos. Remove refrigerator magnets. Shampoo the carpets if they haven't been cleaned in a year. Steam the main-level flooring. These are the invisible wins.

Light Is the Second Most Important Variable

After clutter, light decides whether rooms look spacious or cramped. Open every blind and curtain in the house. Turn on every lamp and overhead light, even in daylight. If you have burned-out bulbs, replace them, and match the color temperature across each room — mismatched warm and cool bulbs look terrible on camera. Coastal homes often have decorative sconces that need special bulbs. Order the replacements a week before shoot day, not the morning of.

Here's what nobody tells you: real estate photographers shoot differently than Instagram photographers. They're often blending exposures to balance window brightness with interior detail. Your job is to get the room lit evenly so their blend has something to work with.

Exterior Prep — Where Coastal Sellers Lose the Most Ground

Grand Strand exteriors take abuse. Salt air stains, humidity-driven mildew streaks on siding and roofs, sand tracking from the beach walk, hurricane debris that lingers in corners of the yard. Buyers from inland markets zoom in on exterior photos looking for maintenance red flags. If your siding has visible mildew streaks or your roof has algae stains, address those before the camera comes out.

Pressure-wash the house, driveway, and walkways a few days before the shoot. Give the pressure-washed surfaces time to dry so they don't look dark in photos. Edge the lawn. Mulch the beds. Hide trash and recycle bins. Move cars out of the driveway. Trim shrubs away from windows and the house line. If you have outdoor furniture, stage it like you'd use it — place settings on the patio table, folded towels on the lounge chairs. These coastal lifestyle shots sell the dream.

Coastal-Specific Features Worth Highlighting

If your home has coastal features, your photo plan should intentionally feature them. Water views from windows — clear the sill and open the blind fully. Dock or boat lift — wash it off and photograph at high tide if possible. Screened porch — stage with chairs and a drink setup. Hurricane shutters — retract and photograph the clean exterior, then mention shutters in the agent description. Flood zone X elevation — include the survey detail in the listing narrative but keep the photo on the lifestyle, not the risk.

These are the details that distinguish a Grand Strand listing from a generic southern home. Buyers paying coastal premiums want to see the coastal lifestyle, not an inland living room with a palm tree outside.

What Not to Over-Stage

Dial back the staging if it gets artificial. A single bowl of lemons on a kitchen island looks curated. Three decorative platters, two cookbooks propped open, a stack of fake magazines, and a wine bottle on a cutting board looks like a showroom. Buyers want to picture themselves living in your home, not evaluating your interior design taste. Minimalism beats maximalism in listing photos almost every time.

Timing the Shoot

Schedule exterior photos for the "golden hour" either late afternoon or early morning. Direct midday sun creates harsh shadows and blown-out windows. If your home has an eastern-facing front, book morning. Western-facing, book late afternoon. Oceanfront homes benefit from sunrise shoots in winter and sunset shoots in summer. Your photographer will have opinions — follow them.

What to Do During the Shoot

Leave the house. Take the dog, take the kids, take yourself to a coffee shop or dinner. Photographers work faster and better without the owner present. If you must stay, stay in one room and don't follow them around. Trust them to do their job. Review the proofs within 24 hours of delivery and request reshoots only for genuine issues — a crooked picture frame, a visible trash can — not for subjective preferences.

Key Takeaways

Pre-listing photo prep is one of the highest-ROI blocks of work a coastal SC seller can do, because out-of-state buyers decide which homes to tour from photos alone. Spend the day before the shoot clearing clutter, maximizing light, pressure-washing exteriors, and addressing mildew streaks and salt-air stains. Stage coastal features intentionally — water views, docks, screened porches, outdoor living — and dial back over-staged kitchen scenes. Book the shoot for golden-hour exterior light, leave the house during the shoot, and request reshoots only for real issues.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Oct. 9, 2026

North Myrtle Beach Market Trends Buyers Should Watch

If you're buying in North Myrtle Beach this year, the headline numbers don't tell the full story. The North Myrtle Beach market splits into pockets that behave very differently, and the gap between them keeps widening. Ocean Drive moves on its own clock. Cherry Grove channel homes answer to boat demand. Barefoot Resort trades off golf and amenity perception. If you treat NMB as one market, you'll miss where the real opportunity is.

Supply is Tight in the Specific Pockets Buyers Want Most

Inventory numbers across the broader Grand Strand have climbed, which gives buyers headlines about a cooling market. The pockets most buyers actually want to live in don't match those headlines. Ocean Drive bungalows near Main Street, raised beach homes in Cherry Grove on the channels, and well-kept condo buildings between 48th and 62nd avenues continue to see competitive activity when the price and condition line up. The soft spots are elsewhere — older oceanfront condos with large pending assessments, interior raised beach homes needing full remodels, and canal-less homes priced like they have water access.

Here's what I mean. A clean, updated raised beach home two blocks off Ocean Drive still draws multiple showings in the first weekend. A nearly identical home three blocks farther back, with original kitchens and a looming special assessment next door, sits for ninety days. The market is picky, not slow.

Price Pressure Shows Up Differently by Product Type

Single-family homes in NMB are holding better than people expect, especially anything with a short walk to the sand or a boat lift on the channel. Condo pricing is where the real softening is showing — particularly in buildings over thirty years old where HOA dues have climbed hard and reserve studies are catching up with deferred work. Buyers reading national headlines about falling prices usually mean condos, and even then only certain tiers.

Oceanfront luxury has its own curve. The highest tier — direct beachfront, modern construction, custom finishes — has traded tightly all year. The middle oceanfront tier (dated interiors, large footprint, strong location) is where sellers are negotiating hardest.

Rates Are Still Shaping Offer Behavior

Buyers paying attention to rates are coming in with different strategies than they did two years ago. More cash offers in the top third of the market. More rate-buydown requests in the middle. Buyers using a mortgage are often asking sellers for closing-cost contributions that would have been unthinkable in 2021. Sellers who understand this are getting their homes sold. Sellers who don't are seeing their listings age.

Insurance Pressure Is Now a Buying Signal

If you're buying anywhere east of Highway 17 in NMB, your insurance quote should come back before your inspection, not after. Wind and hail premiums have moved substantially on older roofs, failed wind mitigation retrofits, and homes where the policy history has been messy. The SC Wind and Hail Underwriting Association remains the backstop for hard-to-insure properties, but the smart play is to figure out which bucket your target home falls into before you fall in love with it.

I've seen buyers lose weeks on a home only to discover the wind premium doubles their expected carrying cost. Get the quote early.

North Myrtle Beach Market Trends Buyers Should Watch

Short-Term Rental Scrutiny Is Changing the Investor Pool

HOAs and municipalities have tightened short-term rental rules in several NMB pockets, and that changes the buyer pool for condos and vacation homes. Some buildings still allow nightly rentals. Others moved to minimum weekly stays. A few shifted to monthly minimums only. If your purchase thesis depends on short-term rental income, you need to verify the current rules at the building and the municipal level, not the rules from two years ago. The North Myrtle Beach permitting office is the final word on what you can and can't do.

Golf-Cart Lifestyle Pockets Are Still Driving a Premium

Buyers moving to NMB for the first time keep asking about the same thing: can I run errands and get to dinner on a golf cart? Golf-cart-friendly neighborhoods closest to the beach access points, main dining, and the ICW continue to carry a premium that doesn't show up in generic price-per-square-foot numbers. If that lifestyle matters to you, pay attention to the specific streets and amenities within walking or cart distance of your prospect home. It changes the resale picture more than most buyers realize.

What Buyers Should Actually Do Right Now

Three things. One: get your insurance quote before you offer. Two: pull HOA documents, including the most recent reserve study and any pending assessments, before you remove inspection contingencies on a condo. Three: understand which micro-market you're actually in — Ocean Drive, Cherry Grove, Windy Hill, Barefoot, Little River edge — because each one is on a different schedule. If you want to see where luxury inventory is clustering, start with the mid-range price band pages and work up from there.

The buyers who are winning in NMB right now aren't paying over asking on everything. They're identifying the right pocket, moving quickly when a well-priced home lands, and walking away cleanly on the overpriced ones. That's it.

Key Takeaways

North Myrtle Beach is not one market, it's several, and the gap between the strong pockets and the soft ones keeps widening. Supply looks soft on paper, but the pockets buyers actually want — Ocean Drive, Cherry Grove channels, well-kept Barefoot homes — still move quickly when priced right. Condos are where the real softening is showing, especially older buildings carrying large pending assessments. Get your insurance quote before you offer, pull reserve studies before you commit, and verify short-term rental rules at the HOA and municipal level before you underwrite income. The winners here are picking the right pocket and moving fast when the right home lands.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Oct. 8, 2026

What Coastal SC Sellers Should Do When the Appraisal Comes In Low

Your coastal SC home is under contract, the buyer's lender orders the appraisal, and the number comes in below the contract price. If you're the seller, this is where a lot of deals quietly fall apart — or where they get saved by the owner who knows what to do next. Here's the playbook I run with my Myrtle Beach and Conway sellers when the appraisal lands short.

Why Low Appraisals Happen More on the Coast

Appraisers work from comps, and coastal SC comp pools are messy. Oceanfront, waterway, canal, flood zone, elevation, year-round vs. second-home condition — these variables can swing value hundreds of thousands of dollars within the same zip code. An appraiser who doesn't work the coast regularly may pull comps that aren't truly comparable. New construction competing against resale, short-term rental properties competing against primary residences, and condo buildings with wildly different HOA pictures all cloud the picture.

What I see consistently along the Grand Strand is that out-of-market appraisers underestimate the premium on specific micro-features: direct ocean access, boat lifts, flood zone X vs. flood zone AE, newer wind mitigation. Local appraisers who work Little River and North Myrtle Beach every week see these differences. Appraisers routed in from Charleston or Columbia sometimes don't.

Step One: Read the Report Before You React

Request the full appraisal report through your agent and read it carefully. Look at four things. One: the comps the appraiser used — are they genuinely comparable in location, elevation, flood zone, and condition? Two: the adjustments — did the appraiser credit your home for upgrades, water access, or coastal-specific features? Three: factual errors — wrong square footage, wrong bedroom count, wrong flood zone, missing features. Four: the methodology — did the appraiser use a sales comparison approach appropriate to the property type?

Errors happen more than people think. A missing bathroom, a wrong lot size, a flood zone miscoded, a dock not credited — any of these can move the number meaningfully.

Step Two: Submit a Reconsideration of Value if the Report Is Flawed

If you find real errors or genuinely better comps the appraiser missed, your agent can submit a reconsideration of value (ROV) through the buyer's lender. This is a formal challenge with documented evidence — corrected facts, additional comps, photos of overlooked features. ROVs don't always succeed, but when the original report has clear errors or weak comp selection, they can move the number. Local lender relationships matter here. A buyer's lender who regularly works coastal SC properties is more likely to engage with a reasonable ROV than a national shop handling the file remotely.

What Coastal SC Sellers Should Do When the Appraisal Comes In Low

Step Three: Negotiate With the Buyer

If the ROV doesn't change the number, you have four main paths with the buyer. Lower the price to match the appraisal and keep the deal together. Hold firm and ask the buyer to bring the cash difference. Split the gap — you drop some, they bring some. Walk away and relist. Which path makes sense depends on how motivated both sides are, how real the comp picture actually is, and how exposed your position is if you have to go back on market.

Here's the thing. Walking back onto the market after a failed appraisal is harder than most sellers expect. The next buyer's lender orders another appraisal, often sees the same comps, and sometimes comes in at the same number. Dropping price now may be the same outcome you'll face in sixty days with more risk and carrying cost in between.

Step Four: Protect the Deal During the Negotiation

Keep communication clean during the negotiation. Don't let the frustration leak into buyer-side conversations. Your agent should document everything in writing, including any revised price or buyer concession. Appraisal gap addendums should be clearly worded. If the buyer agrees to bring cash to close the gap, make sure their lender confirms the final loan-to-value works for them.

Short-Term Rental and Second-Home Appraisals Have Their Own Quirks

Properties being sold as rentals or second homes often appraise with income approach limitations that don't apply to primary residence sales. If your buyer's lender is treating the property as an investment, the appraisal rules shift. Confirm with your agent whether the property is being financed as primary, second home, or investment, because each one changes what the appraisal has to accomplish.

Frequently Asked Questions

Can I challenge an appraisal directly?

Not usually. The lender ordered the appraisal and owns the file. Your challenge, formally called a reconsideration of value, has to go through the lender. Your agent runs this on your behalf.

How long does an ROV take?

Usually a week or two. Some lenders turn them around faster. Factor this delay into your closing timeline and ask for a contract extension if needed.

What if the buyer wants to walk?

If the contract has a standard financing contingency, the buyer typically has the right to terminate when the appraisal comes in short, unless both sides agree on a path forward. Negotiating in good faith usually preserves the deal.

Does paying for a second appraisal help?

Sellers can't order an appraisal that the buyer's lender will accept. A second appraisal is only useful as supporting evidence in an ROV or in deciding whether to walk away and relist.

Should I accept the price drop or walk away?

It depends on the strength of the comp picture, how motivated the buyer is, and your carrying cost if you have to go back on market. A good listing agent will model both paths in actual dollars before you decide.

Key Takeaways

A low appraisal on a coastal SC home isn't automatically a lost deal, but it does demand a real plan. Read the full report, look for comp errors and missed features, and submit a reconsideration of value through the buyer's lender if the report is flawed. If the number holds, you can lower price, ask the buyer to bring cash, split the gap, or walk away — and relisting is harder than most sellers expect. The sellers who come out ahead treat the appraisal process as negotiable rather than final.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Oct. 7, 2026

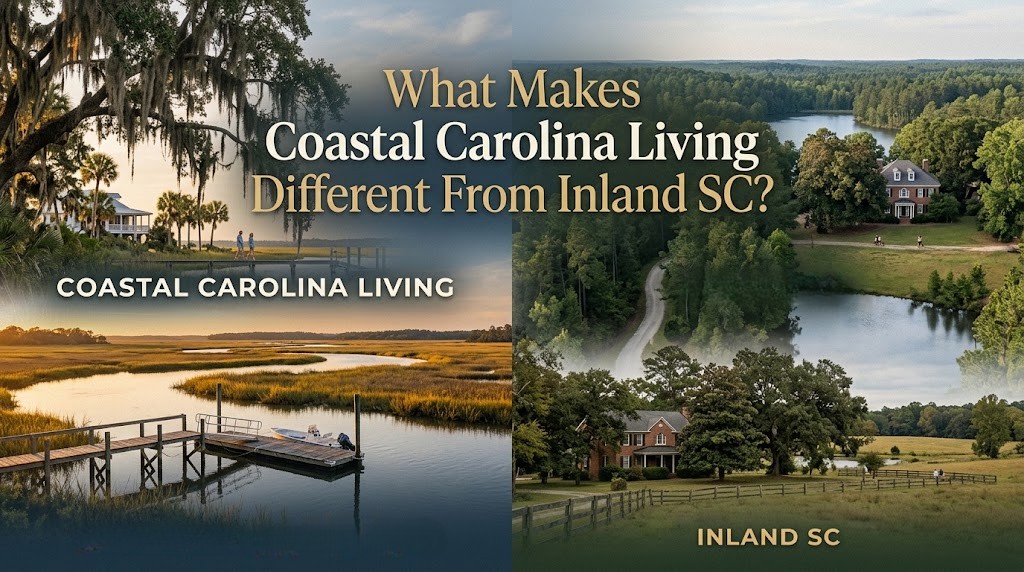
What Makes Coastal Carolina Living Different From Inland SC

People moving to South Carolina often lump the whole state together. On a map, Myrtle Beach and Columbia look like neighbors. In real life, they're two different places with two different climates, two different insurance realities, and two different lifestyles. If you're deciding between coastal Carolina and inland SC, the differences will shape your mortgage, your maintenance budget, and how you spend your Saturdays. Here's what nobody tells you until after you've closed.

The Climate Is a Different Animal on the Coast

Inland SC gets hot, humid summers and milder winters. The Grand Strand gets the same humidity, plus salt air, plus hurricane exposure, plus a different kind of winter wind coming off the Atlantic. The temperatures aren't dramatically different between Myrtle Beach and Columbia on an average July afternoon, but what the air does to your house is. Metal corrodes faster. Wood swells. HVAC coils foul. If you've only lived inland, you underestimate how much the ocean works on a home, year in and year out.

Inland buyers moving to Conway, which is twelve miles inland and sits on the Waccamaw River, get a milder version of the same thing. Still humid, still subject to tropical weather, but less direct salt exposure than homes east of Highway 17.

What Makes Coastal Carolina Living Different From Inland SC

The Insurance Stack Is Where Most Inland Buyers Get Surprised

Inland SC homeowners usually carry one policy: homeowner's insurance. Coastal Carolina homeowners typically carry three layers — homeowner's, wind and hail, and often flood. Each one has its own carrier, its own deductibles, and its own rules. The wind and hail layer is where most inland buyers go pale at closing when they see the number. Direct oceanfront runs several multiples of what a comparable Columbia home would pay for all its coverage combined.

The SC Wind and Hail Underwriting Association is the state-supported backstop when the private market won't write a property. It's a real option, not a last resort, and plenty of coastal homeowners use it. Just know it exists before you fall for a specific home.

Home Construction Reflects the Environment

Coastal homes are built differently. Raised beach homes sit on piers because they're in flood zones. Hardie plank and other cementitious sidings are standard because wood siding deteriorates faster near salt air. Metal roofs show up more often on new construction near the coast. HVAC systems are sized larger for humidity load. Inland SC homes trade a lot of these features for traditional on-grade foundations, lower insurance costs, and simpler maintenance.

When you tour a coastal home, pay attention to things like coil coatings on the condenser, hurricane shutters, impact-rated windows, and whether the roof has documented wind mitigation. Inland buyers often skip these details and then discover their renewal insurance premium hinges on them.

Lifestyle Isn't Just Beach vs. No Beach

The lifestyle gap is more layered than most buyers assume. Coastal Carolina gives you ocean, intracoastal, river systems like the Waccamaw, downtown Conway's walkable district, boating, fishing, oceanfront dining, and about a hundred golf courses within thirty minutes. Inland SC gives you lake culture (Lake Marion, Lake Murray), BBQ country, state parks, college-town rhythms around Columbia and Clemson, and a slower suburban pace.

Here's the thing about the Grand Strand lifestyle: in-season (April through October) it's busy. Traffic on Highway 17 changes, restaurants have waits, the beaches fill up. Residents learn to work around the tourist calendar. Inland SC doesn't have that same seasonal rhythm. If you want pure quiet year-round, that gap matters.

Cost of Living Trades Different Line Items

Coastal Carolina generally has higher insurance costs, higher HOA fees in beach communities, and often higher property taxes for second homes or non-primary residences. Inland SC has lower insurance, cheaper gas, usually cheaper housing per square foot, and smaller utility bills in the winter. Food costs are similar. Healthcare access is similar in metro Columbia and Myrtle Beach, though specific specialty care may route to Charleston or Charlotte depending on where you land.

If you're planning around a fixed retirement budget, run the actual numbers for the specific town you're considering, not state averages.

Who Thrives on the Coast and Who Doesn't

People who love water, outdoor time, and a seasonal rhythm thrive on the coast. People who dislike tourists, hate humidity, or need deep quiet year-round often do better inland. Boaters, golfers, retirees who want ocean access, and families drawn to small coastal towns like Little River or Aynor settle in and stay. Buyers who move for the beach but never actually walk on it tend to regret the premium they paid.

What to Look at Before You Pick a Side

Spend time in both regions in different seasons. Price out insurance on specific homes before you commit. Drive the commute you'd actually drive on a weekday morning. Walk through a few neighborhoods at night. The difference between coastal and inland isn't a feeling — it's a stack of real monthly numbers plus how you want to spend your time.

Key Takeaways

Coastal Carolina and inland SC share a state but behave like two different places. Climate, salt exposure, and hurricane risk make coastal homes more expensive to insure and build, with layered policies most inland buyers don't expect. The lifestyle trade is beach, boats, and golf-plus-tourists on the coast versus lakes, quiet, and lower monthly carrying costs inland. Figure out which costs matter to you, visit in different seasons, and price insurance on specific homes before you commit to a side.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Oct. 5, 2026

Simple Curb Appeal Upgrades Under $500 for Coastal SC Homes

You're getting ready to list and your budget for pre-listing work is tight. Here's the good news. Curb appeal is where a small budget delivers the biggest impact, and specific upgrades under $500 consistently outperform much more expensive investments in other areas of the home. Whether your property sits in a newer subdivision like Carsens Ferry or an established Conway neighborhood, the first impression buyers get from the sidewalk determines whether they walk through the door already interested or already skeptical. Here's what actually works on a real budget.

Simple Curb Appeal Upgrades Under $500 for Coastal SC Homes

Why Curb Appeal Matters More Than Most Sellers Think

Buyers form their first impression from the moment they arrive. Bad curb appeal makes them enter the home already looking for reasons not to buy. Good curb appeal makes them enter already leaning toward yes. That psychological shift affects everything that happens inside.

The buyers scrolling your listing photos see the front of the home first. That single image often decides whether they scroll further or move on. On a phone screen, the front-of-house shot has to work at thumbnail size and full size.

Investing $500 in front-of-house improvements often returns $5,000 to $15,000 in buyer response. Almost no other pre-listing investment produces that ratio.

The Highest-Impact Under-$100 Items

Start with the changes that cost almost nothing but shift the whole impression.

  • Front door paint. A gallon of quality exterior paint and a few hours of your time transforms the door. Pick a color that contrasts with the house — dark blue, deep red, black, or forest green work well against most Grand Strand exteriors. Under $50.
  • New house numbers. Replace dated brass or worn plastic with modern metal numbers. Under $40 at any home improvement store.
  • New front door hardware. Handleset, deadbolt, and kickplate matched to modern style. Under $80.
  • New doorbell. Basic modern doorbell or a video doorbell. Under $80.
  • Fresh doormat. Clean, current, appropriately sized for the door. Under $30.
  • Sconce or porch light bulbs. Replace with warm-toned LED bulbs. Under $20.

Total for this cluster: under $300. Impact on curb appeal: significant.

The Pressure Washing Investment

Pressure washing is the single highest-ROI curb appeal investment. Renting a pressure washer runs $40-$80 per day. Doing the work yourself, you can address the entire exterior in a weekend.

What to hit:

  • Siding — especially north-facing walls where algae accumulates
  • Driveway and walkways — years of stains disappear
  • Deck or patio surfaces
  • Fence sections visible from the street
  • Front porch ceiling and columns
  • Garage door if it's siding-material rather than metal

The difference between a pressure-washed exterior and an unwashed one shows up immediately in photos. Buyers who don't consciously notice will still respond emotionally to the cleaner look.

The Landscape Refresh Under $200

You don't need a landscape overhaul. You need a landscape refresh.

  • Fresh mulch in all beds. A few yards for most Conway-area homes. $50-$100 delivered.
  • Trim overgrown shrubs. Costs nothing but time.
  • Remove dead plants. Costs nothing.
  • Add seasonal flowering annuals for color at the front entry — a few flats of well-chosen flowers. $30-$60.
  • Edge all beds cleanly. Rent an edger for a day if needed, or do it by hand. Under $30.

Fresh mulch alone transforms most yards. Combined with edging and flowering annuals near the entry, the effect suggests a well-cared-for home.

The Yard Cleanup That Costs Nothing

Free actions that dramatically change how the yard reads.

  • Cut the grass short and edge cleanly before listing photos
  • Remove all lawn ornaments, garden gnomes, and personal decorative items
  • Store trash cans and recycling bins out of sight
  • Coil garden hoses neatly or store them
  • Remove children's outdoor toys and pool floats from the front yard
  • Sweep porches, walkways, and driveways
  • Wash exterior windows visible from the street

These take a Saturday morning. Collectively they shift the impression from lived-in to move-in ready.

The Front Porch Refresh

A specific pocket where small investment delivers real impact.

  • Two matching planters with flowering annuals flanking the door. $60 for planters plus $30 for plants.
  • A pair of rocking chairs or a small bench if space allows. Sometimes free from moving neighbors, otherwise $100-$200 for basic options.
  • A neutral throw pillow on any porch seating.
  • A simple wreath on the front door — season-appropriate, not overwhelming.

The porch that reads as an actual usable space rather than empty concrete signals a home someone would want to live in.

What to Fix vs. What to Leave

Some visible items are worth addressing. Others aren't worth the budget.

Fix: peeling paint on trim, worn caulk around windows, missing shutter slats, leaning mailbox, broken exterior light fixtures, damaged front door screens, torn window screens.

Leave (or price to acknowledge): major exterior paint jobs, roof replacements, driveway resurfacing, complete landscape redesigns. These often don't return their cost in the sale price.

The specific items worth fixing tend to be small, visible from the street, and inexpensive. The items to skip tend to be large, capital-intensive, and hard to see meaningful returns on within a normal listing window.

The Photography Angle

Curb appeal only matters if the photos capture it well.

Schedule photography in the morning or late afternoon when light is softer and warmer than midday overhead sun.

Make sure everything you invested in shows up in the lead front-of-house photo — landscaping, refreshed door, house numbers, flowering annuals near the entry.

If your home is in a distinctive community like Astoria Park or another newer subdivision, the photo should capture what makes the streetscape appealing beyond just your specific home.

How Price Band Changes the Approach

Different price bands justify different curb appeal investments.

For homes in the Conway homes under $300,000 band, the $500 budget approach is often exactly right. Buyers at this price point expect basic curb appeal but don't expect professional landscaping.

For homes in the $250,000 to $500,000 band, buyers expect a higher baseline. The $500 budget still helps but may need to be complemented by professional lawn service before listing.

Above $500,000, buyers expect professional landscaping maintenance and higher-end curb appeal. $500 alone doesn't cover the expected baseline.

Two Things I Tell Every Coastal SC Seller About Curb Appeal

First, do the work two to three weeks before listing photography. Fresh paint needs time to dry cleanly. New plants need to root. Mulch needs to settle. Photos taken immediately after prep can look artificial. A short buffer lets everything integrate into the yard naturally.

Second, look at your home from across the street after you've done the work. Cross the street with fresh eyes. Notice what still needs attention. Buyers see the home from this vantage point during drive-bys and in listing photos. If it doesn't hold up from across the street, keep refining before photography.

Key Takeaways

Curb appeal delivers the highest ROI of any pre-listing investment — $500 up front often returns $5,000 to $15,000 in buyer response. Focus on the highest-impact moves: pressure wash the house, refresh the front door with paint, hardware, house numbers, and a clean mat, and put roughly $200 into mulch, edging, and flowering annuals at the entry. Fix the small visible stuff like peeling paint and broken fixtures, and skip major capital work that won't return. Then schedule photos in soft morning or late afternoon light and make sure everything shows in the lead photo.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Oct. 2, 2026

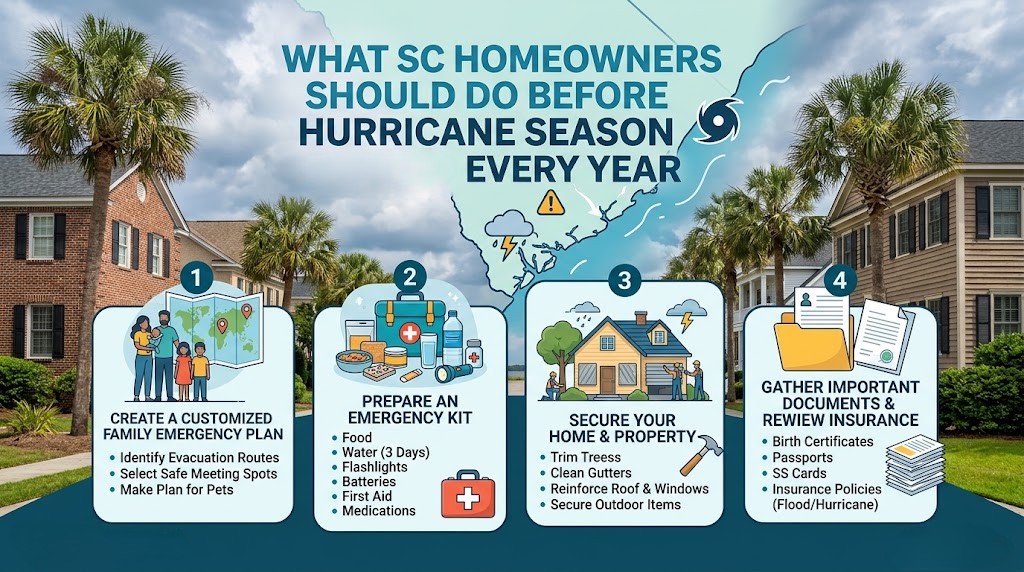
What SC Homeowners Should Do Before Hurricane Season Every Year

Atlantic hurricane season runs June 1 through November 30 every single year. Peak activity typically hits mid-August through October. If you own a home along the Grand Strand — whether you're in Coquina Harbour or an inland pocket well away from the coast — the annual preparation ritual matters. Homeowners who prep systematically before June 1 handle storm season without drama. Homeowners who wing it usually spend at least one season learning why systematic prep matters. Here's what to actually do every year.

Why Annual Prep Matters Even in Quiet Seasons

Not every hurricane season produces a major landfall. But every hurricane season produces tropical activity, high wind events, heavy rain, and the possibility of storm surge along the coast. Homeowners who prep for the possibility of a major event handle even the minor ones better.

The prep isn't dramatic. Done in the right sequence starting in April or May, it takes a weekend or two and eliminates most of the last-minute scramble when a storm actually threatens.

What SC Homeowners Should Do Before Hurricane Season Every Year

April: The Insurance and Documentation Check

Start the year by verifying your insurance situation is current and understood.

Confirm your homeowner's policy is active with no lapse. Confirm your wind and hail policy is active. Confirm your flood policy is active if you have one. All three layers need to be verified before storm season, not during.

Review coverage limits and deductibles. Percentage-based hurricane deductibles on wind and hail policies can be much higher than you remember. Understanding what you'd pay out of pocket if a storm hit matters for both financial planning and repair decisions.

Document your home's current condition. Walk through every room with your phone, video the contents, photograph exterior condition. Store the documentation in cloud storage. If a claim ever happens, this baseline documentation makes the process much smoother.

Update your emergency contact list — insurance agent, insurance company claims number, HVAC contractor, plumber, roofer, closest neighbor or property manager, family members who need to reach you.

May: The Exterior and Landscape Prep

The exterior work matters most and can be done gradually through the month.

Trim trees and shrubs. Any limbs within 10 feet of the roof, windows, or power lines should be cut back. Dead limbs anywhere near the house should be removed. This single task prevents more roof damage than any other prep item.

Clean gutters and downspouts. Standing water in blocked gutters during a heavy rain leads to roof and foundation issues. Spring cleaning matters more than fall cleaning in this context.

Inspect and clean roof surface. Look for missing shingles, damaged flashings, worn caulking around penetrations. Address issues before storm season rather than during.

Test hurricane shutters if you have them. Verify all fasteners are in place. Practice deploying them. Store them where they can be accessed quickly.

Confirm the location of your water shutoff valve, gas shutoff, and main electrical panel. Test that they work. Know how to access them in emergency conditions.

Early June: The Supply and Systems Check

By the start of hurricane season, you should have your supply situation in order.

Stock hurricane supplies now, not the day before a storm arrives. Water (one gallon per person per day, three-day minimum), non-perishable food, first-aid supplies, medications, flashlights, batteries, portable radio.

Confirm generator operation if you have one. Change the oil, test the electrical connections, store fresh fuel with stabilizer.

Charge portable battery packs for phones. Verify car chargers work.

Service HVAC before peak season. A tuned system handles the heat and humidity that follows storms better than one carrying accumulated issues.

Refill any prescription medications with extra supply. Pharmacies get overwhelmed when storms approach.

Ongoing Through Season: The Weather Monitoring Routine

Once June 1 passes, monitoring becomes part of the routine.

Sign up for local emergency alerts through Horry County and your specific municipality if applicable. These provide better local information than national weather services.

When a named storm develops in the Atlantic, start monitoring daily. Cone of uncertainty projections change over time.

When a storm enters the 5-day cone, start preparing specific items — move outdoor furniture inside, secure loose exterior items, top off vehicle fuel, review evacuation routes if you're in an evacuation zone.

When landfall projections narrow, deploy hurricane shutters, complete any remaining preparation, and either shelter in place or evacuate based on the specific situation and your evacuation zone.

What Full-Time vs. Second-Home Owners Should Prep Differently

Ownership type changes the preparation calculus.

Full-time residents can complete last-minute prep in the days before landfall. The prep runway can be shorter because you're at the property.

Second-home and snowbird owners need to complete more prep ahead of time because you can't easily return to handle last-minute items. Consider engaging a local property manager who can deploy shutters and secure the property if you're not available.

Coastal properties in Ocean Drive, Cherry Grove, or barrier-island equivalents need more aggressive prep than inland properties in Longs real estate. Storm surge, wind exposure, and evacuation requirements differ meaningfully.

The Communication Plan Nobody Sets Up Until It's Too Late

Family communication during storms is often overlooked in prep.

Establish a family communication plan — who calls whom, what alternative contacts exist if phones fail, where to meet if evacuation becomes necessary, who has the master emergency contact list.

Share property access information with an out-of-state family member. If you're evacuated and someone else needs to check on the property afterward, they should have the necessary information.

Establish a "safe" check-in system. When a storm affects your area, family members waiting to hear from you need clarity about when and how you'll communicate.

What Storm Season Teaches Every Year

Two patterns worth noting.

Small storms create real damage more often than headline hurricanes. Broken tree limbs, minor roof issues, power outages, and minor flooding happen most seasons. The prep for major storms also handles minor events better.

The homeowners who suffer worst are usually the ones who assumed the season would be quiet. Assuming quiet doesn't hurt anyone in years when the season actually is quiet. Assuming quiet costs real money in years when it isn't.

For homeowners in barrier-adjacent inventory or specific NMB pockets, browse North Myrtle Beach real estate to understand which properties face higher exposure than others.

Two Things I Tell Every SC Homeowner About Hurricane Season Prep

First, prep once, prep thoroughly, and prep before June 1. Homeowners who systematically prepare in April and May don't scramble when storms threaten. Homeowners who plan to prep "when we hear something" often find the local supply stores empty of what they need. The calm-weather prep window is short. Use it.

Second, don't ignore mid-season maintenance. A storm-free July doesn't mean the season is quiet. Peak activity historically hits August through October. Complete any deferred prep by early August so you're ready when the historical peak arrives.

Key Takeaways

Grand Strand homeowners should run a systematic hurricane routine every year, starting in April. April is for insurance verification and photographing current condition. May is exterior work — tree trimming, gutter cleaning, roof inspection, shutter testing, and confirming shutoff valves. Early June wraps up supplies, generator testing, and HVAC service; once the season starts you monitor weather and adjust as storms enter the cone. Second-home owners need a faster response plan than full-timers, and family communication planning gets overlooked until it's too late.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.