Conway, SC Real Estate News 

Century 21 McAlpine Blog

The Agents and Staff at Century 21 McAlpine love our area and one another! We hope to share some of our daily activities with you and see how we might better serve our community!


Aug. 20, 2026

The Real Cost of Selling a Home in South Carolina

You're thinking about selling your home and wondering what you'll actually walk away with. The number you get at closing is not the sale price. It's the sale price minus a longer list of costs than most sellers expect. Here's a straight breakdown of what selling a home in South Carolina actually costs, so you can plan on real net proceeds instead of guessing at them.

Real Estate Commission

Commission is the biggest single line item for most sellers. In the Grand Strand market, total commission on a residential sale typically runs a percentage of the sale price, split between the listing agent's brokerage and the buyer's agent's brokerage. The exact rate is negotiable, and the recent shifts in how commissions are handled have changed some of the mechanics. Ask your agent to explain their specific commission structure and what's included in it.

For a home in the $300,000-$500,000 range, commission commonly runs several thousand to well over $20,000 total. It's worth understanding exactly what you're paying for and what services come with it.

Attorney Fees

South Carolina requires an attorney to conduct real estate closings. The seller's side of the transaction typically pays for the seller's attorney to handle the deed preparation and title work. In this market, attorney fees typically run several hundred dollars for a straightforward transaction, more for complex situations.

Title Insurance and Owner's Policy Considerations

The buyer typically purchases title insurance to protect their ownership. In some transactions, the seller is asked to provide a warranty or contribute to specific title costs, particularly if title issues emerge during the search.

Property Taxes and HOA Prorations

You'll pay a prorated share of property taxes and HOA dues up to the closing date. If you're closing partway through the year, you cover the portion of the year you owned the home. This gets calculated at the closing table.

South Carolina primary residence property tax at the 4 percent assessment ratio makes this less painful than in many states, but it's still a real number. For homes in higher price bands or where the owner never filed for the legal residence exemption, the tax proration can be more meaningful.
 The Real Cost of Selling a Home in South Carolina

Pre-Listing Preparation Costs

Sellers who invest in preparation typically net more from the sale, but the preparation itself costs money upfront. Realistic pre-listing spend for most Grand Strand homes:

  • Professional photography: a couple hundred dollars for a standard package, more for drone or video
  • Interior paint refresh: typically several thousand dollars for a comprehensive job
  • Deep cleaning: a few hundred dollars for a professional service
  • Landscape refresh and curb appeal work: several hundred to a few thousand depending on scope
  • Minor repairs from a pre-listing walkthrough: highly variable, plan for at least a modest budget
  • Staging or furniture rental if the home is vacant: several thousand for professional staging

Sellers who skip preparation often end up giving back more in negotiation than they would have spent on upfront prep.

Inspection Repair Concessions

After the buyer's inspection, they'll typically ask for repairs or credits. What you'll actually give up depends on the condition of the home, the inspection findings, and the strength of the market. In a shifting market like right now, sellers usually give up more than they did during the peak.

Realistic budgeting: assume you'll concede somewhere between a few hundred and several thousand dollars in either completed repairs or credits at closing. Well-maintained homes give up less. Homes with known deferred maintenance give up more.

Wind and Hail Insurance and Coverage Gaps

Sellers occasionally get asked to address insurance-related issues. If the wind mitigation inspection reveals items that could affect the buyer's insurance premium — missing hurricane straps, older roof, ungusseted gable ends — some buyers negotiate for those improvements before closing.

This shows up more often in coastal transactions than inland ones, but Grand Strand sellers should factor in the possibility.

Home Warranty (Optional)

Some sellers offer a home warranty as part of the transaction to reduce post-closing surprises for the buyer. A one-year home warranty typically runs a few hundred dollars and can be part of a negotiation package.

Mortgage Payoff and Any Loan-Related Costs

The mortgage payoff is the number that gets sent to your lender at closing. It includes principal balance, accrued interest through the payoff date, and any prepayment penalty if applicable. Most modern mortgages don't have prepayment penalties, but confirm with your lender.

If you have a HELOC, second mortgage, or any other lien on the property, those all need to be paid off at closing before you receive proceeds.

Capital Gains Tax Considerations

Not everyone owes capital gains tax on a home sale, but many do. Primary residence sellers can typically exclude a substantial portion of their gain if they've lived in the home two of the last five years — up to $250,000 for a single filer and $500,000 for a couple filing jointly.

Investment property, second homes, and short-term ownership don't qualify for the primary residence exclusion, so those situations produce a capital gains tax bill. Talk to your CPA before you sell if capital gains could be a factor for you.

What Sellers Usually Underestimate

Two costs I watch sellers routinely underestimate.

Moving expenses. Professional movers, packing supplies, temporary storage, and the incidentals of physically leaving a home add up faster than most sellers plan for.

The carrying cost while you're between homes. If you're selling before you've bought your next place, you'll be paying rent, storage, and possibly overlapping utilities during the transition.

For broader market context on what's actually happening at your price point, browse Conway real estate or Myrtle Beach real estate inventory to see how competing listings are pricing right now.

Realistic Total Cost of Selling

For a typical Grand Strand primary residence sale, plan for total selling costs (commission, fees, prep, concessions, taxes, moving) to run somewhere between 8 percent and 12 percent of the sale price depending on the specifics.

Higher-end homes tend to run closer to the lower end of that range because commissions negotiate down as a percentage on larger transactions. Lower-priced homes tend to run higher as a percentage because fixed costs like attorney fees don't scale.

Do the math on your specific situation before you list. Knowing your realistic net proceeds keeps the decision-making process cleaner all the way through.

Two Things I Tell Every Seller About Costs

First, get a written net sheet from your agent before you list. A good net sheet shows the sale price minus every expected cost and gives you a realistic bottom-line number. Sellers who know their net upfront make better decisions during negotiation. Sellers who don't often panic when the numbers show up at closing.

Second, don't let cost fear stop you from investing in preparation. The pre-listing spend consistently pays back more than the cost. The seller who skips paint to save a few thousand dollars often gives up more than that in negotiation. Sellers who prepare well typically walk away with more, not less.

Key Takeaways

  • Total selling costs on a Grand Strand primary residence typically run 8-12 percent of the sale price
  • Commission is usually the biggest single line item; know your exact structure before signing the listing agreement
  • South Carolina requires attorney closings; expect several hundred dollars for a straightforward transaction
  • Property tax and HOA prorations get calculated at closing based on your ownership period
  • Pre-listing preparation usually pays back more than it costs, but requires upfront investment
  • Inspection repair concessions typically run higher in a shifting market than at the peak
  • Capital gains tax may apply on non-primary residences and short-term ownership situations
  • Moving expenses and between-homes carrying costs get underestimated by most sellers
  • Get a written net sheet from your agent before listing so you know your realistic bottom line

Frequently Asked Questions

Who pays commission when I sell my home in South Carolina?

Traditionally the seller pays total commission at closing, split between listing and buyer-side brokerages. Recent changes in how commissions are handled have introduced new variations — some transactions involve the buyer paying their own agent directly. Talk to your listing agent about the specific structure that applies to your transaction.

How much does an attorney charge for a closing in SC?

Straightforward residential closings typically run several hundred dollars in attorney fees. Complex transactions with title issues, boundary disputes, or unusual property situations can cost more. Ask your closing attorney for a fee estimate upfront.

Will I owe capital gains tax when I sell my home?

Primary residence sellers can typically exclude up to $250,000 in gain (or $500,000 for married couples filing jointly) if they've lived in the home at least two of the last five years. Non-primary residences and investment properties don't qualify for that exclusion. Talk to your CPA about your specific situation.

What's a realistic net sheet, and when should I get one?

A net sheet shows the sale price minus every expected cost, giving you a realistic estimate of what you'll walk away with. Ask your agent for one before you list. Update it if the market shifts or if you accept an offer below the original list price.

Are pre-listing repairs worth it, or should I sell as-is?

It depends on the specific repairs and the market. Cosmetic items like paint, flooring, and staging typically return more than they cost. Major system repairs (roof, HVAC) usually don't return their full cost but often reduce inspection-period negotiations that would have cost you more anyway. Talk to your agent about which specific items make sense for your home.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.
Aug. 19, 2026

Why Marion, SC Is Becoming More Attractive to Buyers

Buyers who've spent months shopping the Grand Strand and hit their price limit have started asking me about Marion. Here's the answer they usually want to hear. Yes, Marion works. And here's the answer they don't always want to hear. It's not the Grand Strand. It's about 45 minutes west of Conway, and the trade-offs are real. But if you understand what you're getting, Marion is one of the most under-appreciated value plays in the entire region right now.

Where Marion Actually Sits

Marion is the county seat of Marion County, west of Horry County. About 45 minutes from Conway on Highway 501. About 90 minutes from Charleston. Population around 6,500 in the town proper, with more in the surrounding county area. The Great Pee Dee River runs nearby, and the town has a real historic downtown with buildings dating back well over a century.

What makes Marion different from most Grand Strand-adjacent options: it's fully its own place. Not a bedroom community. Not a satellite of the coast. Marion has its own identity, its own history, and its own rhythm.

Why More Buyers Are Discovering Marion

Several things have shifted over the last few years.

Remote work made the drive to the coast a non-daily concern for a lot of buyers. If you're not commuting, the 45-minute distance to Conway doesn't affect daily life much.

Housing costs on the Grand Strand climbed faster than incomes. Buyers priced out of Conway or Longs started looking further inland. Marion showed up as an obvious answer.

Property tax and cost-of-living math is genuinely favorable. South Carolina's 4 percent primary residence assessment ratio applies here. Combined with lower home prices and generally lower local costs, Marion delivers real financial breathing room.

The historic downtown has picked up. New restaurants, small businesses, and community events have made downtown Marion a real destination in ways it wasn't a decade ago.

Healthcare access improved. McLeod Medical Center Dillon and Marion services provide real care locally, though specialists still often require driving to Florence, Myrtle Beach, or further.

Who's Actually Buying in Marion Right Now

The Marion buyer pool has broadened. Here's what I'm seeing.

Retirees who did the math on Grand Strand pricing and decided the money stretches further inland. Some visit the coast on weekends and are happy to trade daily beach proximity for a house they own outright.

Remote workers who need a home office and reliable internet but don't need to commute. Fiber has expanded in Marion, though verify by exact address.

Families priced out of Conway or the Carolina Forest area who want a real home with a real yard at prices that work. Marion delivers this in a way that shrinking pockets of coastal Horry County can't.

Buyers looking for historic homes. Marion has a real inventory of pre-1930s houses with character that costs a fraction of comparable Charleston or Wilmington historic inventory.

Small business owners and entrepreneurs who can operate from anywhere and appreciate the small-town business support.

For broader comparison, browse Conway real estate and Loris real estate alongside Marion to see how the value differences actually play out at your price point.

Why Marion, SC Is Becoming More Attractive to BuyersWhat Marion Costs

Here's what I see consistently in this market. Older single-family homes in town run in a much lower price band than comparable inventory anywhere in Horry County. Historic homes with character are especially attractively priced for what you get. Newer construction is limited but exists at friendlier prices than the Grand Strand equivalent. Rural acreage nearby is available at prices that don't exist closer to the coast.

For buyers whose primary constraint is price per square foot, Marion delivers value the coast simply can't match.

The Trade-Offs You Should Understand

Marion isn't perfect. Here's what you're giving up.

The drive to the beach. It's 45 minutes to Conway and another 15-20 to the ocean. If you'd hit the sand three times a week, Marion will wear on you.

Retail depth. Marion has functional retail for daily life, but specialty shopping, certain dining, and cultural amenities require real drives to Florence, Myrtle Beach, or further.

Healthcare specialists. Primary care works fine. Complex or specialized care often means longer drives.

School program depth. Marion County schools have solid foundations but narrower program options than the larger Horry County high schools. High-achieving students with specific advanced course needs may want to verify what's available.

The pace of life. Marion is genuinely slower than what most Grand Strand buyers are used to. Some love that. Others take six months to adjust.

What I Tell Every Marion Buyer to Verify

Well and septic for rural addresses. Water quality testing during due diligence, not after.

Internet by exact street address. Fiber has expanded but isn't universal in every pocket.

Flood zone status if you're near the Great Pee Dee River. Older homes closer to the river sit in flood zones, and insurance handles that differently.

Historic district rules if you're buying in downtown Marion. Preservation guidelines can affect renovation plans.

Property tax status. Filing for the 4 percent primary residence rate requires paperwork after closing.

Two Things I Tell Every Buyer Considering Marion

First, visit twice before you commit. Weekend visits show you the best version of Marion. A weekday visit shows daily life. Buyers who see both make much better decisions.

Second, plan for realistic drives. If your daily life involves regular trips to the coast, specialty medical, or major shopping, Marion doesn't work as well as it looks on paper. If your daily life is mostly at home and you occasionally head to the coast for a day, Marion delivers real value. Match honestly.

Key Takeaways

  • Marion sits about 45 minutes west of Conway with real historic character and prices below anything comparable in Horry County
  • Remote work, Grand Strand price increases, favorable SC property tax structure, and a revitalized downtown are driving the shift
  • Retirees, remote workers, priced-out families, historic-home buyers, and small business owners are the main buyer types finding value here
  • The trade-offs are drive time to the beach, limited retail depth, healthcare specialist access, school program depth, and adjusting to a genuinely slower pace
  • Verify well and septic, internet quality, flood zone status, historic district rules, and property tax filing before and after closing
  • Visit twice before committing and honestly assess your daily drive patterns
  • Marion is a real value play for buyers whose lifestyle actually fits it; it wears on buyers who need coastal proximity

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 18, 2026

Why Longs Appeals to First-Time Buyers

You've been shopping the Grand Strand for your first home and Longs keeps showing up in your search. Here's why. It's one of the few pockets on the strand where the mortgage math actually works for a first-time buyer. The prices are real. The insurance is friendlier than the beach. And Highway 31 puts you in North Myrtle Beach in about 15 minutes when you want the ocean. If you're new to the market, let me walk you through how Longs actually works and what to check before you write your first offer.

Why Longs Works for Your First Home

The Grand Strand pricing curve is steep. A block off the ocean, and a comparable house is a couple hundred thousand cheaper. Two blocks off, cheaper still. By the time you're in Longs, you're getting a real starter home in a real neighborhood at a price a first-time buyer can carry.

Here's what I mean. A 3-bedroom, 2-bath home in Longs runs in a price band a first-time buyer can qualify for with a moderate income. In a lot of the Cherry Grove or Ocean Drive equivalent inventory, that same home is out of reach for anyone still building their savings.

You get the coast lifestyle without paying beach-block prices. That's the deal.

Why Longs Appeals to First-Time Buyers

Which Longs Communities to Look At First

A few pockets consistently work for first-time buyers.

Heritage Park at Longs — predictable D.R. Horton-style construction with a community pool that people actually use. Lots of first-time buyers land here because the HOA covers what it's supposed to and doesn't surprise you later.

Buck Creek — newer builds with modern layouts. First-floor primaries, real home offices, updated kitchens. If you work from home and want a house that's already set up for that, look here.

Cypress Ridge — the more affordable side of new construction. If your budget is tighter and you want to stay under $300,000, this is where I'd start.

Carrington Woods — a value-tier community that's been filling in steadily. Good fit for buyers who want new construction without stretching the budget.

For a broader look at what's currently for sale, browse Longs real estate.

The Loan Programs That Change Your Math

Most first-time buyers don't realize how many financing options actually exist. Some of these can be the difference between buying now and waiting two more years.

USDA rural development loans work on a lot of Longs addresses. Zero down payment for qualified buyers. This one program has helped more first-time Longs buyers than any other. Check the USDA property eligibility tool with the specific address you're considering.

FHA loans work anywhere in Longs. 3.5% down. Credit scores as low as 580 can qualify.

VA loans work for eligible veterans. Zero down. No PMI.

SC Housing offers down payment assistance programs for qualified first-time buyers. Income limits apply, and funding windows open and close, so ask your lender early.

Conventional loans with 3-5% down work if your credit is strong. This can be better than FHA long-term because you can drop PMI faster.

What You'll Want to Verify Before You Close

A few things I make every first-time buyer confirm during the inspection period:

The insurance quote for that specific address. Wind and hail policies price differently by location. Get the real quote before you remove your inspection contingency, not after.

Internet quality by exact street. Fiber has expanded but isn't universal. If you work from home, this is a make-or-break.

School attendance zone by address if you have kids. Community names don't always match zones.

HOA rules and reserves. Read the last two years of meeting minutes and the reserve study. First-time buyers who skip this step sometimes get hit with special assessments in year two.

The specific commute you'll actually make. Drive it at real morning traffic time. GPS estimates lie about school-year mornings.

What Nobody Tells First-Time Longs Buyers

Two things you should know that most agents don't mention.

First, don't buy at your maximum approval. Lenders will pre-approve you for more than you should actually spend. First-time buyers who stretch to 100% of approval often struggle when the HVAC goes out, the roof needs work, or a special assessment hits. Buyers who stay at 75-80% of their approval enjoy the home. Buyers who max out usually don't.

Second, prioritize location and structure over cosmetic finish. A dated kitchen you can update over time. A great location in a great school zone with a solid roof and HVAC — that's what you can't easily change. Pick the home that's fundamentally right and let the finishes come later.

The Trade-Offs You Should Know

Longs isn't perfect. Here's what you're giving up compared to living closer to the beach.

The drive to daily-life stuff. Grocery, healthcare, specialty shopping — most of that is 15-25 minutes. Not far, but real. First-time buyers who move from suburbs where everything is 5 minutes sometimes struggle with this.

The retail depth is still catching up. New restaurants and shops arrive every year, but the selection isn't what you'll find in Myrtle Beach proper.

Some rural addresses have internet limitations. If you're a remote worker, verify this specifically.

The beach is 15-20 minutes, not walking distance. If you'd hit the sand five times a week, you'd want to be closer. If you'd go twice a month, Longs works fine.

For broader context on what's out there, browse Conway real estate alongside Longs to compare the value differences between similar-tier towns.

Key Takeaways

  • Longs is one of the few Grand Strand pockets where first-time buyer mortgage math still works
  • Heritage Park, Buck Creek, Cypress Ridge, and Carrington Woods are the top first-time buyer communities
  • USDA rural development, FHA, VA, SC Housing, and conventional loans all have programs that fit first-time buyers
  • Verify insurance quote, internet quality, school zone, HOA reserves, and real commute time by exact street address
  • Don't buy at your maximum approval — leave a buffer for the unexpected
  • Prioritize location and structure over cosmetic finish; you can update finishes over time
  • The trade-off is 15-25 minute drives to daily amenities and the beach; if that works for you, Longs delivers real value

Frequently Asked Questions

What credit score do I need to buy a home in Longs?

FHA loans can work with scores as low as 580. USDA loans typically want 640 or above. Conventional loans usually require 620 minimum. A higher score gets you a better rate, which matters more than most first-time buyers realize over a 30-year loan.

How much do I need for a down payment?

USDA loans allow 0% down for qualified buyers on qualifying addresses. VA loans allow 0% for eligible veterans. FHA needs 3.5%. Conventional loans typically start at 3-5%. Talk to a local lender early — the right program can save you years of saving.

Are there closing cost assistance programs for first-time buyers in South Carolina?

Yes. SC Housing offers programs that can cover some down payment and closing costs for qualified buyers. Income limits apply and funding is limited, so ask your lender to check eligibility early in the process.

What HOA dues can I expect in Longs first-time buyer communities?

Most Longs subdivision HOAs run modest — typically $50-$150 monthly. Some amenity-heavier communities charge more. Always ask for the current dues and any pending assessments before you go under contract.

How long does it take to close on a home in Longs?

Standard financed closings run 30-45 days from accepted offer to closing table. USDA loans can take slightly longer because of the additional review. Cash purchases can close in 14-21 days.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 17, 2026

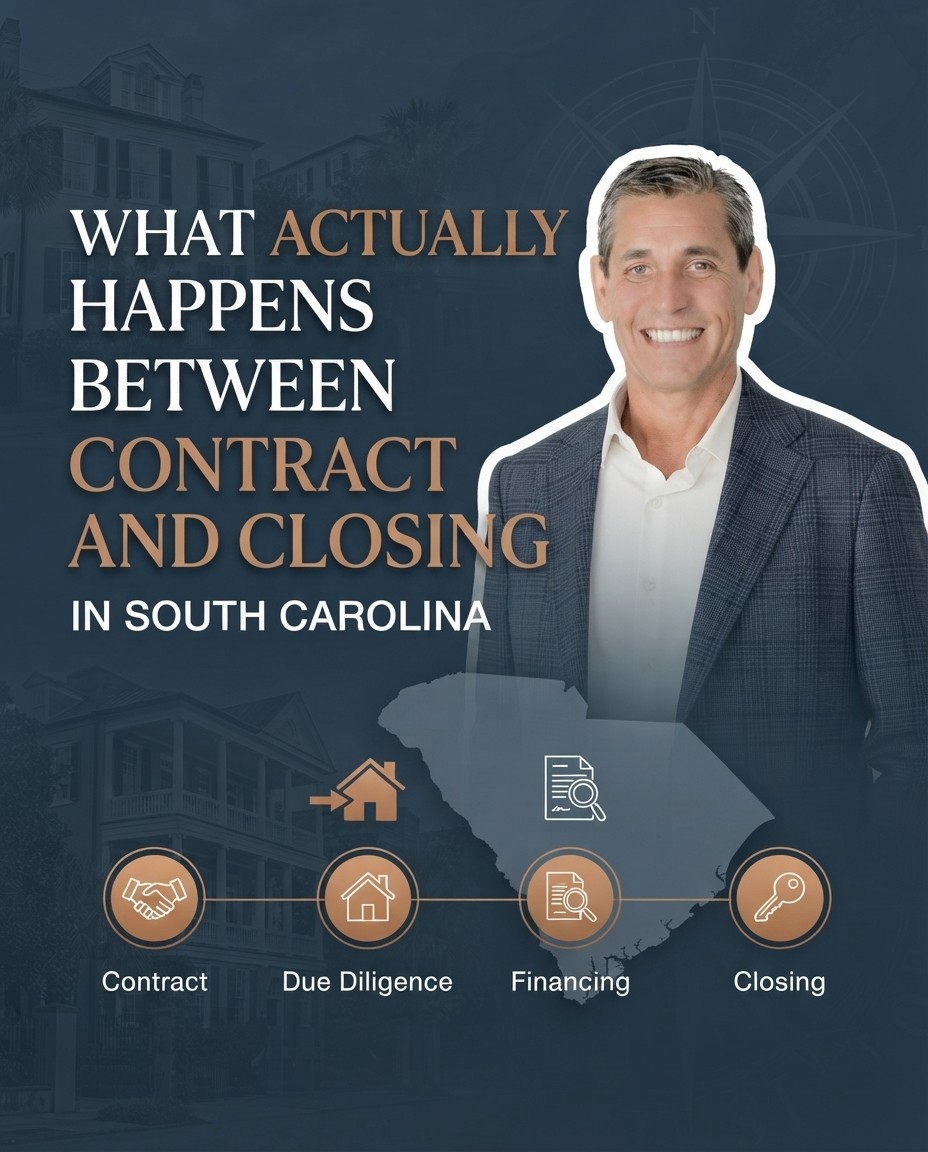
What Actually Happens Between Contract and Closing in South Carolina

The 30 to 45 days between an accepted offer and the closing table can feel like a black box to first-time buyers and sellers. Papers get signed. Inspectors show up. Money moves. Somewhere in the middle, deals sometimes fall apart for reasons nobody explained clearly at the offer stage. After walking hundreds of Grand Strand buyers and sellers through this exact window, I want to demystify what actually happens between contract and closing in South Carolina — and what usually goes wrong when a deal doesn't reach the closing table.

Day One to Day Three: The Contract Kickoff

Within 48 hours of a signed contract, several things need to happen quickly:

  • The buyer wires or delivers the earnest money deposit to the closing attorney's escrow account
  • The contract is delivered to the buyer's lender to start the loan process
  • The closing attorney's office opens the file and orders the title search
  • Both parties schedule their inspections
  • The buyer contacts insurance agents to get preliminary quotes

Sellers who don't hear from their agent within 48 hours of a signed contract should reach out. Delays at this stage cascade later.

Day Three to Day Ten: The Inspection Period

The inspection period is typically 10 to 14 days after the contract is signed. Buyers use this window to:

Complete the standard home inspection ($400-$600).

Order a separate CL-100 wood-destroying organism inspection ($75-$150).

Get a wind mitigation inspection if the home is coastal ($150-$250).

Order specialty inspections (roof, HVAC, structural) if the general inspection flags concerns.

Get real insurance quotes based on the specific property's flood zone, wind zone, and coastal exposure.

Confirm the school attendance zone if children are involved.

Review the HOA documents if applicable — bylaws, meeting minutes, reserve study, current dues, pending assessments.

This is the most critical window in the entire transaction. Buyers who don't do thorough due diligence here often discover expensive issues after closing when they have no recourse.

Day Ten to Day Fourteen: Repair Negotiation

Based on inspection findings, buyers typically request either repairs or credits at closing. This negotiation can determine whether the deal survives.

What works: focusing on major issues (structural, safety, systems), asking for completed repairs by licensed contractors with receipts, and letting cosmetic concerns go.

What kills deals: piling up cosmetic complaints alongside real issues, demanding excessive credits, or negotiating too aggressively in a market where the seller has alternatives.

Sellers should approach the request calmly. Most repair negotiations settle at a reasonable middle ground.

Day Fourteen to Day Twenty-Five: The Financing Push

Once the inspection period ends and the deal is firm, the lender takes over. Buyers should expect:

Formal loan application and underwriting.

The lender orders the appraisal ($400-$700, buyer typically pays).

The appraisal is completed and returned in 5-10 business days.

The lender requests any additional documentation (updated bank statements, employment verification, etc.).

Underwriting reviews everything and either approves, conditionally approves, or requests more information.

Common issues that emerge during this window: appraisal comes in below contract price, buyer credit changes unexpectedly, employment changes, or debt-to-income ratios shift because of a new purchase (like a car). Buyers should avoid any major financial changes between contract and closing.

Day Twenty-Five to Day Thirty: Insurance and Title Work

The closing attorney's office is completing the title search, resolving any title issues, and preparing closing documents. The buyer is finalizing insurance:

Standard homeowner's policy.

Wind and hail policy if in a coastal area.

Flood policy if in an AE, A, or VE zone.

The lender needs proof of insurance before closing. For coastal SC homes, this can take longer than buyers expect because policies have to be underwritten by carriers that write in the specific area.

Day Thirty to Day Forty-Five: Final Steps

The final push to closing:

Buyer does the final walkthrough, typically 24 hours before closing. Confirms property is in the agreed condition and any requested repairs are complete.

Closing disclosure is delivered to the buyer at least 3 business days before closing (federally required).

Buyer arranges wire transfer for closing funds. Never trust email instructions for wire transfers — wire fraud is a real risk. Call the closing attorney's office directly to confirm wiring instructions.

Closing appointment. In South Carolina, both parties typically attend, though not always at the same time. Attorney reviews and executes documents. Funds are disbursed. Keys transfer. The buyer becomes the owner.

What Actually Happens Between Contract and Closing in South Carolina

What Actually Goes Wrong Most Often

From watching hundreds of transactions, the deals that die between contract and closing usually die from:

Financing issues. Appraisal comes in low, buyer credit changes, or underwriting reveals problems not caught in pre-approval.

Insurance surprises. Coastal wind and hail policies come in materially higher than the buyer expected, changing the affordability math.

Inspection findings. Major issues that weren't disclosed by the seller or that both sides can't agree on how to address.

HOA issues. Special assessments, rental restrictions, or reserve problems that the buyer didn't accept.

Title issues. Liens, boundary disputes, or ownership questions that take longer to resolve than the contract timeline allows.

External life events. Job changes, family emergencies, or buyer's cold feet that show up at inopportune times.

For broader inventory context if you're currently in this window, browsing Conway real estate or Myrtle Beach real estate shows what's actively available at various price points in case your current deal doesn't survive.

Two Things I Tell Every Buyer and Seller During This Window

First, communicate proactively. Silence is the enemy of a smooth transaction. Buyers, sellers, agents, lenders, attorneys, and inspectors all need timely information. When someone doesn't respond for days, problems fester. When everyone stays connected, small issues get resolved before they become deal-killers.

Second, buyers should avoid major financial changes between contract and closing. No new cars. No new credit cards. No large purchases that affect debt-to-income. No job changes if avoidable. Underwriting can pull credit again just before closing, and changes at that stage kill deals that would otherwise close cleanly.

Key Takeaways

  • Contract to closing typically takes 30-45 days for financed South Carolina purchases; cash purchases can close in 14-21 days
  • The first 48 hours require quick action on earnest money, lender delivery, title order, and inspection scheduling
  • The 10-14 day inspection period is the most critical window in the entire transaction for buyer due diligence
  • Repair negotiation follows the inspection period; sellers who approach it calmly usually keep deals alive
  • The financing push (days 14-25) is where lender surprises can emerge; buyers should avoid financial changes during this time
  • Coastal SC insurance underwriting can take longer than buyers expect; get real quotes during the inspection period
  • Never trust emailed wire transfer instructions — call to confirm; wire fraud is a real risk in real estate transactions
  • Communication is the single most important behavior during the contract-to-closing window

Frequently Asked Questions

Can I back out of a contract during the inspection period?

Yes, in most South Carolina contracts. The standard inspection contingency allows buyers to terminate the contract based on inspection findings and typically receive their earnest money back. After the inspection period ends and the deal is firm, backing out becomes much harder and can put the earnest money at risk.

What is a "closing attorney" in South Carolina?

South Carolina requires real estate closings to be conducted by a licensed attorney. The closing attorney handles title search, prepares closing documents, coordinates funds, and executes the transfer. They represent the transaction rather than the buyer or seller specifically, though buyers can hire their own attorney to review documents if they prefer.

How long does the appraisal process take?

The lender orders the appraisal after the inspection period. The appraisal itself typically happens 3-7 business days after ordering, and the written report is delivered 3-5 days after that. In busy markets or for complex properties, appraisals can take longer. Total time from ordering to report is usually 7-14 days.

What happens if the appraisal comes in below the contract price?

The lender will only finance based on the appraised value. Buyers have three options: renegotiate the price with the seller down to the appraised value, bring additional cash to closing to cover the gap, or terminate the contract if they have a financing contingency. This is one of the more common deal-threatening events in the current market.

Can I do the walkthrough more than 24 hours before closing?

Yes, but the closer to closing, the better. The walkthrough's purpose is to confirm the property is in the agreed condition and any negotiated repairs are complete. A walkthrough done a week before closing can miss issues that emerge in the final days.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 14, 2026

How Buyers Eliminate Your Home on a Phone Screen

Your buyer is scrolling through listings on their phone right now. They're going to look at yours for about three seconds. If those three seconds don't grab them, they swipe. Your home is out of the running before an agent ever gets a call. That's how the modern buying process actually starts, and most sellers I talk to don't fully understand what it means for their listing. Let me walk you through what's really happening on the other end of that screen.

The Elimination Round Is on the Phone

Here's what a real buyer does today. They open our site or the local MLS on their phone. They set their filters. They start scrolling. In one sitting they might look at 40 or 50 listings. They give each one a couple of seconds. Maybe a swipe or two through the photos. If it doesn't hit, they move on.

Out of those 40 or 50, maybe 5 or 6 get saved for a second look. Out of those 5 or 6, maybe 2 or 3 get a real tour scheduled. That's the funnel.

Your listing has to survive the swipe test to even be in the running. And the swipe test happens on a screen the size of your palm, not on a desktop monitor at an agent's office.

What Actually Gets a Listing Eliminated in Three Seconds

I've watched buyers do this in real time sitting next to me. Here's what makes them swipe past:

A lead photo shot on a phone. You can tell instantly. The angles are wrong. The colors are off. The lighting looks flat. Buyers pick this up subconsciously and they move on.

A dark or cluttered lead photo. If the first image is a dim living room stuffed with furniture, buyers assume the house is small. It might not be. Doesn't matter. The photo made them assume.

A lead photo that isn't the exterior. Buyers want to see the house first. When the first photo is a random room, they get confused and swipe.

Photos in a weird order. Bathroom before kitchen. Garage before living room. Random exterior shots mixed with interiors. Buyers don't work to piece it together. They swipe.

Only 8 or 10 photos on a listing. Signals the seller or agent didn't invest. Buyers assume there's a reason.

Yard photos taken in winter with dead grass. Bathroom photos with the toilet seat up. Kitchen photos with dishes on the counter. Small things that show nobody was thinking about the buyer.

The Photo Order Nobody Thinks About

Photo order might be the single most under-discussed piece of listing strategy. Most agents upload photos in whatever order they were shot. That's a missed opportunity.

Here's what should go first. Lead photo: exterior, front-facing, sky and light in the frame. Second photo: whatever room in your house is genuinely the best — kitchen if it's updated, great room if it has a killer view, primary bedroom if it's dramatic. Third photo: something that reinforces the second — a wider angle of the same space, or an adjacent room that flows.

The first three photos determine whether the buyer keeps swiping through your listing. Get those three right and the rest of the photo set has a chance to close the deal.

What I See Consistently on the Grand Strand

A few patterns I've watched play out over hundreds of listings in the Conway, Myrtle Beach, and North Myrtle Beach markets:

Listings with professional photography sell noticeably faster than comparable listings with phone photos. It's not close.

Listings with drone photos of homes that benefit from an aerial angle — waterfront, wooded lots, pool properties — outperform ground-only listings in their price band.

Listings with 3D software or video walkthrough get more out-of-state buyer engagement, which matters here because so many of our buyers are relocating from the Northeast or Midwest.

Listings that are refreshed with new lead photos, updated descriptions, or a price change get a second wave of buyer attention that stale listings never see.

For broader market context on how competing listings are currently presenting, browse Conway real estate, Myrtle Beach real estate, and North Myrtle Beach real estate inventory. Look at how the strongest listings present versus the weakest. The difference is obvious once you're looking for it.

How Buyers Eliminate Your Home on a Phone Screen

What You Should Actually Do About This

If you're getting ready to list, or already listed and not seeing showing activity, here's the honest fix list.

Hire a professional photographer or ask your agent if they use one. This is the single highest-ROI decision you'll make in your listing prep. In this market it typically runs a couple hundred dollars for a solid photo package. On a home worth several hundred thousand, that's a rounding error against the sale price and it pays for itself many times over in faster time on market.

Have your agent think about photo order strategically. Ask them which three photos will lead the listing and why. If they don't have a real answer, that's a conversation worth having.

Look at your own listing on your phone. Pull up the listing on our site, Zillow, Realtor.com, and the local MLS on your phone. Scroll it the way a buyer would. If the third photo bores you, it'll bore buyers.

Add a video walkthrough or 3D tour if you can. Especially important if you're targeting out-of-state buyers. The extra investment pays back on both the initial buyer response and the reduction in low-quality showings.

Refresh the listing at 21 days if it hasn't sold. New photos, new lead image, updated description, price adjustment if warranted. Buyers who scrolled past on day one will see the refreshed version and give it a second look.

Two Things I Tell Every Seller About Phone Elimination

First, your listing is a product and your buyer is a shopper. Shoppers scroll fast, judge quickly, and move on. Every professional retailer has figured this out. Real estate hasn't fully caught up. Sellers who treat the listing like a product and invest in its presentation consistently outperform sellers who treat it like a formality.

Second, the first two weeks on market matter more than the next six months combined. The buyers actively shopping right now will see your listing during that window. If those buyers scroll past because your first three photos didn't grab them, they don't come back later. Fresh eyes on a stale listing rarely happen. Get the initial launch right or accept that you'll be discounting the price to overcome the presentation gap.

Key Takeaways

Buyers today start every home search on a phone screen, and the elimination round happens in seconds. Your lead photo, second photo, and third photo carry almost the whole weight of whether a buyer clicks into your listing or swipes past it. Everything else you spend on the listing matters, but only after the buyer decides to stop scrolling. Professional photography, thoughtful photo order, and phone-screen-first presentation are what separate the listings that sell fast from the ones that sit. Your listing description, floor plan details, and marketing narrative do the closing work, but they only get a chance to work if the visuals survive the phone scroll first. Sellers who treat the listing like a product and invest in real presentation consistently outperform sellers who treat it as a formality. The first two weeks on market are the window that decides whether your listing has momentum. Get the launch right or plan on discounting to overcome a weak start. With more than twenty years selling along the Grand Strand, I can tell you the sellers who take this seriously sell faster and for more. The ones who don't often blame the market when the real problem was the phone screen.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in DIY and Staging
Aug. 13, 2026

Why Downtown Conway Has Become So Popular

Downtown Conway ten years ago was a quieter place. There were still restaurants, still shops, and still the historic character that has always defined this section of town — but the buyer inquiries and out-of-town visitors were a fraction of what they are now. Something has shifted. Downtown Conway has become one of the more sought-after residential and small-business destinations in the region, and after thirty-plus years of watching this town evolve, I want to explain what actually happened and why it matters for anyone thinking about buying, living, or investing here.

The Historic District Has Always Been the Foundation

The core of downtown Conway is the historic district — the streets around Main Street, Kingston Street, Third Avenue, and the Waccamaw River waterfront. Homes here range from grand 1890s Victorians to modest craftsman-era cottages, with a smattering of newer infill construction. The oak canopy is real. The sidewalks are actual sidewalks. And the neighborhood identity has never been diluted by tourist infrastructure the way parts of Myrtle Beach have been.

What's changed is that buyers finally noticed. Walkable downtown neighborhoods with real character and reasonable prices are rare in the Southeast. Downtown Conway has quietly been one, and word has gotten out.

The Riverwalk Changed the Daily Rhythm

The Waccamaw River Riverwalk connects downtown Conway to the water in a way that changed how residents actually use their neighborhood. On any Saturday morning, you'll see people walking dogs, riding bikes, pushing strollers, and stopping at Trestle for coffee. Kayakers put in near the marina. Paddleboarders launch at Pitch Landing.

The Riverwalk isn't just an amenity — it's the connective tissue that makes downtown Conway feel like a real neighborhood. Residents can walk from their homes to the river, along the river to a coffee shop, and back home in a loop that most Southern towns can only dream about.

The Restaurant Scene Has Actually Grown

Ten years ago, Conway's downtown dining was solid but limited. Today it's genuinely deep. Restaurants like Rivertown Bistro, Crady's, Trestle Bakery, and a rotating cast of new arrivals give downtown Conway a food scene that competes with communities much larger. The Third Avenue block has become its own restaurant row on some nights.

The restaurants matter because they make downtown a place people go, not just a place people live near. Residents from Wild Wing Plantation, Carsens Ferry, and Carolina Forest come downtown for dinner and drift back to their subdivisions. Visitors from Myrtle Beach make the 20-minute drive for something different. That flow keeps the downtown alive.

Coastal Carolina University's Steady Influence

CCU sits just south of downtown Conway and has grown substantially over the last two decades. The university's presence brings faculty who want walkable downtown living, students who spend money at downtown businesses, and alumni who eventually return to buy homes in the area. It's a stable driver of population and economic activity that most small towns don't have.

The CCU football program has become another downtown draw — home game weekends fill restaurants and hotels. The Chanticleer identity has quietly become part of Conway's civic identity too.

Why Downtown Conway Has Become So Popular

The Historic Preservation Has Held

Conway has been unusually disciplined about protecting the historic district. Preservation guidelines, design review processes, and community pushback against inappropriate development have kept downtown feeling like downtown. Even the newer construction in and around the historic district generally respects the scale and character of the older buildings.

That discipline pays off decades later. Neighborhoods that surrender to modernization lose their distinctive appeal. Neighborhoods that hold the line become progressively more valuable because the character can't be manufactured elsewhere.

The Population Growth Has Been Steady but Manageable

Conway's population has grown steadily over the last decade without exploding. That measured growth means the infrastructure has generally kept pace. Traffic in downtown is real but not overwhelming. Parking is manageable if you know where to look. The pace of change hasn't outstripped the community's ability to absorb it.

Compare this to communities that grew too fast — you see the strain in overcrowded schools, congested roads, and neighborhood character that gets diluted by rushed development. Conway has avoided the worst of that.

Who's Actually Moving Downtown

The buyer mix in downtown Conway has evolved:

Retirees who traded suburban houses for walkable urban living. Coming from the Northeast primarily, wanting real downtown character without the cost of Charleston or Wilmington.

Remote workers who want a real neighborhood. A downtown Conway home office beats a suburban home office in ways that show up in daily quality of life.

Younger families who want walkable neighborhoods for their kids. Downtown Conway lets kids ride bikes to Conway Elementary and walk to the Riverwalk in ways most modern neighborhoods don't allow.

Alumni and faculty from CCU who want short commutes and real community. Conway is small enough to feel personal, big enough to have real amenities.

Investors buying historic homes for renovation and rental — carefully, given historic district rules, but the returns have been real.

For buyers exploring downtown-adjacent inventory, browsing Conway real estate alongside homes near Conway Elementary shows what's actually on the market in the historic district and immediate surrounding streets.

What Downtown Conway Costs

Realistic price bands right now:

Smaller historic cottages needing updates: $220,000 to $325,000.

Well-maintained mid-tier historic homes: $325,000 to $500,000.

Larger renovated historic homes on premium streets: $500,000 to $850,000+.

New infill construction in the historic district: variable, typically $400,000 to $800,000 depending on lot and design.

Condos and townhomes in and near downtown: $180,000 to $400,000 depending on building and unit.

What Downtown Conway Buyers Underestimate

Two patterns worth flagging:

Historic homes need real attention. Older HVAC, older electrical, older windows, occasional foundation quirks. Budget for updates over the first few years of ownership. The character is real, but so is the maintenance load.

Parking on some blocks can be tight, particularly during CCU home games or special events. Off-street parking on your specific property is a real value driver in downtown Conway.

Two Things I Tell Every Downtown Conway Buyer

First, walk the neighborhood at multiple times of day before you buy. A Tuesday morning feel is different from a Saturday afternoon feel, which is different from a game-day Saturday. Buyers who visit only once see one version of the neighborhood. Buyers who visit multiple times see the reality.

Second, talk to your future neighbors before you commit. Downtown Conway is small enough that neighbor conversations are easy and consistently informative. Ask about the block, the noise, the parking, the drainage after storms, and the community events. Fifteen minutes of neighbor conversation tells you more than any inspection report can.

Key Takeaways

Downtown Conway's popularity has grown structurally rather than as a trend — the historic district's character, the Riverwalk connection to the Waccamaw, an evolving restaurant scene, CCU's steady influence, disciplined historic preservation, and measured population growth have all reinforced each other over the last decade. The buyer mix has broadened from primarily local move-up buyers to include retirees, remote workers, younger families, CCU alumni and faculty, and investors. Realistic price points range from $180,000 condos to $850,000+ premium historic homes. Historic homes require budgeting for updates over time, and parking on some blocks is worth verifying. The neighborhood works particularly well for buyers who value walkable urban living, real character, and community connection over suburban conveniences. Downtown Conway has quietly become one of the more interesting residential neighborhoods on the Grand Strand, and buyers who understand the trajectory tend to make good long-term decisions when they land here.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle
Aug. 12, 2026

Golf Course Communities Near Little River Worth Exploring

If you're shopping for a golf home on the north end of the Grand Strand, Little River should be on your short list. You get real courses, real community, and prices that don't match what you'll pay closer to the ocean. Here's what I mean. A single-family home on a fairway in Little River often runs meaningfully less than the same home on a Myrtle Beach course. And you're still 15 minutes from North Myrtle Beach when you want the sand. Let me walk you through the golf communities buyers should actually look at up here.

Why Little River Golf Works Differently

Little River is a working harbor town first, a golf town second. That's part of the appeal. The golf communities up here don't have the resort intensity you'll find at some of the bigger destinations further south. They feel residential. Full-time neighbors. Real communities.

You also get the boating culture on top of the golf. A lot of my Little River golf buyers keep a boat at one of the marinas. Round in the morning, out on the Intracoastal in the afternoon. That's a lifestyle you can't put together in most Grand Strand pockets.

Eastport Golf Community

Eastport is one of the more established golf communities in Little River and has held up well. The single-family homes at Eastport Golf Homes attract buyers who want the golf lifestyle in a real neighborhood setting. Mature landscaping. Established neighbor relationships. The course itself has stayed stable, which matters more than most buyers realize when they're shopping.

For buyers who want the golf community experience at a lower entry price, Eastport Golf Condos deliver the same amenity access without the single-family maintenance load. That works well for second-home buyers and retirees who want the lock-and-leave lifestyle.

Here's what nobody tells first-time golf-community buyers. Ask about the club's ownership structure before you commit. Eastport has held together, but some Grand Strand golf communities have seen course ownership changes that hurt home values. Ownership stability is one of the biggest factors in whether a golf community holds its value.

River Hills Golf Community

River Hills is another Little River golf option with a more residential feel. The community has its own course and attracts buyers who want a quieter setting than some of the bigger amenity communities. Full-time residents mix with second-home buyers. The neighborhood identity is real.

What I like about River Hills: the daily-life amenities are within a short drive without feeling like you're inside a resort. If you want a real neighborhood with a golf course rather than a resort with houses attached, River Hills tends to fit.

The Barefoot Resort Overflow

Technically Barefoot Resort sits inside North Myrtle Beach city limits, but the practical reality is that buyers shopping Little River golf often end up considering Barefoot. It's minutes away from Little River proper and offers a resort-scale amenity package that the other Little River options don't match. If you want that Grande Dunes-style resort experience but at the north end of the strand, Barefoot is worth touring.

The trade-off: HOA dues and amenity fees run higher than the pure Little River communities. Make sure the amenity package matches what you'll actually use.

Golf Condos as an Entry Point

Not every golf buyer needs a single-family home on a fairway. Some of the better value in this market sits in golf-community condo product. You get the course access, the amenity package, and often a small yard or patio at a fraction of the single-family price. For snowbirds who use the property 4-8 months a year, this often makes more financial sense than a full house.

Little River has a real inventory of these units. Not every one is directly on a course, but many have fairway views or short walks to the tee. For broader inventory, browse Little River real estate and filter for what you actually want to spend.

Golf Course Communities Near Little River Worth ExploringWhat to Ask About Any Little River Golf Community
A few questions I make every golf-community buyer ask before writing an offer.

Who owns the golf course? HOA-owned courses have different dynamics than privately-owned ones. Neither is automatically better. What matters is stability and financial health.

Are club fees required for all residents, or optional? Some golf communities require every household to pay for a club membership whether you golf or not. That can be a real cost if you don't play. Others make membership optional. Big difference in ownership economics.

What's the reserve study look like? Golf communities have big-ticket capital items — greens, cart paths, irrigation, clubhouse maintenance. Under-funded reserves mean special assessments are coming.

How's the play volume? A course that's under-played is a course at risk of closing or being sold to a developer. Ask the pro shop what rounds look like on a typical weekend.

What are the specific covenants and restrictions? Golf-community CC&Rs can restrict landscaping, exterior colors, and short-term rentals. Make sure the rules match how you plan to live in the home.

Two Things I Tell Every Little River Golf Buyer

First, play the course before you buy. Sounds simple. Almost nobody does it. Renting a cart and playing 18 gives you a feel for the course quality, the resident engagement, and whether the amenity you're paying for actually delivers what you want. I've watched buyers commit to homes based on marketing brochures only to discover the course wasn't their style. Play first.

Second, talk to a current resident about their annual budget. Golf community carrying costs include HOA dues, club fees, cart fees or trail fees, and often various incidental charges. A conversation with a neighbor tells you more about the real annual cost than any HOA disclosure ever will.

Key Takeaways

Little River golf communities give you real courses and real community at prices below what you'll pay closer to the ocean. Eastport works for buyers who want an established course with residential neighborhood feel. River Hills fits buyers who want quieter surroundings with course access. Barefoot Resort is the north-end resort option if you want the full amenity package. Golf condos across the area offer real value at the entry level. Course ownership stability, HOA financial health, membership rules, and reserve status matter more than the surface marketing. Play the course before you commit and talk to a current resident about real annual carrying costs. Little River rewards buyers who ask the right questions upfront and delivers a golf lifestyle that has held up through multiple market cycles.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Posted in For Buyers, Lifestyle
Aug. 11, 2026

Cost-Effective Renovations That Boost Resale on Coastal SC Homes

Sellers ask me constantly which renovations actually pay back at resale, and the honest answer for coastal South Carolina is different than the answer in most national real estate advice. Salt air, humidity, hurricane season, and the specific buyer pool along the Grand Strand shape which upgrades add real value versus which ones just cost money. After thirty-plus years of walking sellers through pre-listing improvements — and watching how each renovation actually shows up in the eventual sale price — I have a specific list of what pencils in this market. Here's what actually delivers ROI along the coast.

The Rule I Use Before Recommending Any Renovation

Every renovation dollar should either return more than one dollar at sale or make the difference between selling and not selling. If a project fails both of those tests, skip it. That sounds obvious, but the emotional pull to over-improve is real, and sellers who ignore this rule routinely lose money on their pre-listing spend.

The second filter I use: does the renovation match the neighborhood ceiling? A $50,000 kitchen makes sense in Grande Dunes. It's an over-investment in a mid-tier Longs subdivision. Match the improvement level to what buyers in that price band actually expect.

Cost-Effective Renovations That Boost Resale on Coastal SC Homes

Kitchen Refresh (Not a Full Remodel)

Full kitchen remodels rarely return their full cost. But a targeted kitchen refresh consistently outperforms most other pre-listing investments.

What a refresh looks like: paint or refinish existing cabinets rather than replace, swap out dated hardware for modern pulls, replace laminate or dated granite counters with quartz, update the sink and faucet, and refresh the backsplash. Total cost commonly runs $6,000 to $15,000 depending on kitchen size. Return at sale typically runs $12,000 to $25,000 higher offers.

What doesn't return well: gutting the kitchen for new cabinets, high-end appliance packages beyond what the neighborhood expects, or elaborate custom work that ages fast.

Bathroom Updates

Primary bathroom updates return well when they're strategic. What works:

New vanity, new mirror, updated lighting, fresh paint, and a modern faucet. This cluster commonly runs $2,500-$5,000 per bathroom and returns $5,000-$10,000 in perceived value.

Retile the shower if the existing tile is dated or damaged. Runs $3,000-$7,000. Returns $6,000-$12,000 depending on how bad the original condition was.

What doesn't return well: expensive whirlpool tubs, custom walk-in showers that don't fit the home's price band, or over-designed features that turn off future buyers.

Interior Paint

This is the single highest-ROI improvement on almost every listing. A comprehensive interior paint job runs $3,000-$7,000 for most homes and consistently returns 3-5x that in improved sale price.

The key: neutral, current colors. Whites, warm greiges, soft off-whites. Avoid trendy accent walls, dated color schemes, or personal color preferences that limit the buyer pool.

Consider paint that includes primer to cover well in one or two coats, especially over darker or bolder existing colors.

Flooring

Coastal humidity is hard on flooring, and buyers respond strongly to floor condition. Where to invest:

Refinish existing hardwood if it exists. $2,500-$5,000 depending on square footage. Returns most of the cost and often more.

Replace worn or dated carpet with luxury vinyl plank (LVP) in main living areas. $8-$15 per square foot installed. LVP handles humidity better than hardwood and looks current. Buyers respond well.

Keep good carpet in bedrooms — buyers still generally prefer soft flooring in bedrooms, and replacing bedroom carpet returns less than replacing worn living-area carpet.

Curb Appeal

Coastal SC buyers form their first impression from the driveway. What returns:

Pressure washing everything — siding, driveway, walkways, decks. Costs $400-$1,500 depending on home size. Returns 5-10x the cost in improved buyer response.

Landscape refresh — trim overgrown shrubs, add fresh mulch, plant a few flowering annuals, replace any dead plants. $1,000-$3,000. Returns well beyond that.

Front door refresh — paint the front door a strong, welcoming color, update the hardware, replace the doorbell if it's dated. Under $500. Consistent buyer impact.

Address numbers and mailbox — small details that signal care. $100-$300.

Outdoor Living Investments

Given the Grand Strand's 9-month outdoor season, outdoor improvements return better here than in most markets:

Screened porch improvements — new screens, ceiling fans, updated flooring, refreshed paint. $1,500-$4,000. Returns significantly higher.

Deck refinishing or replacement of worn boards. $2,000-$6,000 depending on size and materials.

Simple patio upgrades — pressure-treated pergola, string lights, a stamped concrete section. Under $5,000 for meaningful impact.

For more detail on outdoor features generally, browsing Myrtle Beach real estate inventory in your target band shows what outdoor spaces are competing at your price point.

The Systems That Actually Matter

Buyers walk through inspections carefully, and system age affects offer strength materially:

Replace HVAC if it's over 12 years old. New units run $6,000-$12,000 depending on size and efficiency. Returns some of the cost, but more importantly removes a major objection during inspection.

Replace the roof if it's at end of life. Coastal SC asphalt shingle roofs typically last 12-18 years. A new roof rarely returns its full cost, but a failing roof costs the seller more in negotiation concessions than a proactive replacement would have.

Address any known plumbing or electrical issues before listing. Buyers use inspection findings as leverage. Sellers who fix these items ahead avoid the negotiation.

What to Skip

Renovations that don't pencil in most coastal SC scenarios:

Full kitchen remodels beyond what a refresh would achieve. Return rarely exceeds 60-70% of cost.

Adding a bedroom, especially if it requires reducing common space. Rarely returns cost.

Elaborate landscape overhauls with expensive plantings. Buyers underappreciate the cost.

Pool installation. Pools work in certain neighborhoods but the ROI on installing one purely for sale rarely pencils.

Trendy color schemes or fixture choices. Everything you install becomes dated eventually.

High-end smart home systems beyond simple thermostats, video doorbells, and smart locks. Complexity turns off many buyers.

The Timing Question

Sellers routinely ask when to do renovations. My advice: complete all major work before listing. Buyers touring a home in the middle of renovations get anxious. Buyers who tour a finished, refreshed home make emotional decisions.

Ideally, complete the renovations 2-6 weeks before listing. Fresh but not so recent that dust and finishing marks are still visible.

If you're comparing your pre-listing prep against similar homes on the market, browse Conway real estate or your specific city's inventory to see what condition sellers are actually presenting.

Two Things I Tell Every Coastal SC Seller About Renovations

First, get an honest agent assessment before spending. A pre-listing consultation with an experienced agent identifies which of your specific home's issues will actually affect the sale price and which won't. That conversation typically saves sellers thousands in avoided over-improvement.

Second, remember that clean beats renovated in many cases. A deeply cleaned, decluttered, freshly painted home often outperforms a partially renovated home in the same neighborhood. If your budget is limited, prioritize cleanliness, paint, and curb appeal before considering more expensive projects. The renovation dollars are best spent on the specific items that actually block buyer decisions in your price band.

Key Takeaways

Cost-effective coastal South Carolina renovations follow a specific pattern — interior paint and curb appeal deliver the highest ROI, kitchen and bathroom refreshes outperform full remodels, LVP flooring solves the humidity durability issue while modernizing the look, and outdoor living improvements return better here than in most markets given the 9-month outdoor season. System replacements (HVAC, roof) rarely return their full cost but remove major inspection objections that can otherwise force painful negotiations. Sellers should match improvement level to neighborhood ceiling, complete work 2-6 weeks before listing, and get an experienced agent's honest assessment before spending. Cleanliness, paint, and curb appeal beat partial renovations in most cases. The right pre-listing spend adds real dollars to the sale price. The wrong pre-listing spend is money that never comes back. Discipline in choosing which projects to do — and which to skip — is what separates sellers who profit from their preparation from sellers who lose money on it.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 10, 2026

What to Know About Well Water Testing and Treatment for Rural SC Homes

If you're shopping rural homes in Horry County — Aynor, Loris, Galivants Ferry, the deeper pockets of Longs, or the back roads off Highway 905 — most of what you tour will run on well water rather than city water. That's normal and works fine for the vast majority of properties, but the well water conversation is one where I've watched too many out-of-state buyers underestimate what they're getting into. After decades of walking rural buyers through this piece of the transaction, I want to lay out what actually matters about well water in this market and how to protect yourself before closing.

How Well Water Works in Rural Horry County

Most rural Horry County wells draw from shallow aquifers, typically 60 to 200 feet deep, tapping into layers of sand and clay that filter the water naturally over time. A pump moves water from the well into a pressure tank, and the pressure tank feeds the home's plumbing.

The system works reliably when it's properly maintained. Wells routinely last 30-50 years. Pumps last 8-15. Pressure tanks last 10-20. Most rural owners never think about their well until something goes wrong.

The catch: what comes out of the well depends heavily on the specific aquifer at that specific location. Iron content, sulfur, hardness, tannins, and bacterial risks all vary from lot to lot. A well 500 feet away from your target property can have completely different water than the one under your driveway.

The Common Water Quality Issues in This Market

The most frequent water quality issues I see in Horry County wells:

  • Iron content that stains sinks, tubs, and laundry orange or brown
  • Sulfur that creates a rotten-egg smell, particularly when the hot water runs
  • Hardness that leaves mineral scale on fixtures and shortens appliance life
  • Tannins from decaying vegetation that give water a yellowish-brown color
  • Low pH (acidic water) that corrodes copper plumbing over time
  • Occasional bacterial contamination, particularly in shallower wells
  • Radon or other trace elements in some specific areas

None of these are automatic deal-killers, but each has an addressable solution if you know what you're dealing with before you buy.

What to Know About Well Water Testing and Treatment for Rural SC HomesThe Water Testing Process

A pre-purchase water test is separate from the standard home inspection and worth every dollar. Basic testing includes:

Bacteriological analysis for coliform and E. coli. This is critical for safety.

Mineral panel — iron, manganese, hardness, TDS (total dissolved solids), pH, and typical trace elements.

Aesthetic factors — odor, taste, and color.

Specific concerns based on the property — if the neighborhood has known well issues, test for those specifically.

Cost typically runs $75-$250 for a basic panel, up to $500 for more comprehensive testing that includes radon, arsenic, and less common contaminants.

The test should be done during the inspection period so results influence the purchase decision. Never accept a seller's water test — get your own from a certified lab.

Treatment Systems and What They Cost

Once you know what's in the water, treatment systems address specific issues:

Sediment filters — basic, $50-$200, remove particles and rust.

Iron removal systems — $1,500-$4,000 installed, handle iron-heavy water.

Water softeners — $1,000-$3,500 installed, address hardness.

Sulfur removal (typically iron and sulfur combined systems) — $2,500-$6,000 installed.

Reverse osmosis for drinking water — $300-$1,500 for a point-of-use system at the kitchen sink.

UV disinfection for bacterial issues — $800-$2,000 installed.

Whole-home multi-stage treatment for complex water — $5,000-$12,000+.

Most rural Horry County homes benefit from at least a basic iron and hardness treatment system. Fully untreated well water in this area is more the exception than the rule.

Ongoing Maintenance Costs

Beyond the initial testing and treatment installation, ongoing well and treatment system maintenance runs:

  • Annual water test for bacterial contamination — $75-$150
  • Filter replacements every 6-12 months — $100-$300 annually
  • Water softener salt refills every 4-8 weeks — $10-$25 per bag
  • UV bulb replacement annually if you have UV disinfection — $75-$200
  • Pump replacement every 8-15 years — $800-$2,500
  • Pressure tank replacement every 10-20 years — $400-$1,000
  • Occasional pump inspection or well cleaning — $300-$800

Total ongoing well and water treatment costs commonly run $500-$1,500 per year for most rural homes.

What Well Buyers Should Verify at Any Target Property

The specific items that matter during due diligence:

Well depth and age. Older shallow wells (less than 100 feet) are more prone to contamination and less durable than newer deeper wells.

Well construction records if available. Grouting, casing type, and static water level all matter.

Pump age and specifications. A pump that's 15 years old is approaching end of life.

Pressure tank age and condition.

Existing treatment systems — what's installed, how old, and what they treat.

Water flow rate under real use — the well should sustain reasonable water pressure when multiple fixtures are running.

Location of the septic system relative to the well. State code typically requires minimum separation distances, and violations create ongoing contamination risk.

Historic water quality issues if the seller or neighbors have any information.

For broader rural market context, browsing Aynor real estate and Loris real estate inventory shows the variety of rural properties where well water applies. Coastal-adjacent properties in Longs real estate and rural Conway addresses also often depend on well systems.

Water Treatment Investment Timing

New buyers often ask when to invest in treatment. My guidance:

If the water test shows bacterial contamination, treat before you move in. This is a safety issue.

If the water is aesthetically unpleasant (staining, odor, taste), install treatment within the first month or two. Living with unpleasant water erodes quality of life fast.

If the water is functional but not ideal, consider whether treatment is worth the investment during the first year of ownership. Sometimes you adjust to the water. Sometimes you don't.

Don't buy the seller's assurance that the water is fine. Test it yourself and make treatment decisions from the results.

Two Things I Tell Every Rural SC Buyer About Wells

First, budget for at least $1,500-$5,000 in first-year well and water investments beyond the purchase price. Testing, filter installation, minor treatment upgrades, and setup for ongoing maintenance are almost always necessary. Buyers who don't budget for this get surprised in the first six months.

Second, establish a relationship with a good local well and water treatment contractor early. When something goes wrong — and it eventually will — having a trusted local expert who knows your specific system and its history is invaluable. Emergencies in year one are much easier to handle when you already have someone you can call.

Key Takeaways

  • Most rural Horry County homes run on well water, and water quality varies significantly from lot to lot
  • Common issues include iron, sulfur, hardness, tannins, low pH, and occasional bacterial contamination
  • Pre-purchase water testing ($75-$500) is separate from the home inspection and worth every dollar
  • Treatment systems range from basic sediment filters ($50-$200) to whole-home multi-stage systems ($5,000-$12,000+)
  • Annual ongoing well maintenance costs typically run $500-$1,500
  • Verify well depth, pump age, pressure tank condition, treatment systems, and septic separation during due diligence
  • Budget $1,500-$5,000 for first-year well investments beyond the purchase price
  • Establish a relationship with a local well contractor within the first few months of ownership

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.

Aug. 7, 2026

Moving to the Grand Strand with School-Age Kids: A Full Checklist

Relocating with school-age children is a different kind of move than relocating solo or as a couple. The stakes are higher, the timing is tighter, and the specific decisions you make in the months before the move affect the kids' first year in ways that are hard to reverse later. After thirty-plus years of helping families relocate to the Grand Strand and watching what works versus what doesn't, I want to walk through what family relocators should actually be doing at each stage. This isn't a generic moving checklist — it's the specific things that matter for a Grand Strand family move.

Six Months Before the Move: The Big Decisions

The earliest stage is about narrowing where you'll actually land:

Identify which school zones you'd accept. Horry County has multiple attendance areas, and school quality and program depth vary meaningfully. Research the specific elementary, middle, and high schools your kids would attend, not just general community ratings.

Take a scouting trip to tour target neighborhoods. Ideally visit at least two — a coastal or beach-adjacent option and an inland option. Notice how each feels for daily family life, not just weekend visits.

Verify remote work permanence if that's the plan. The reliability of your remote work arrangement drives everything else about where you can live.

Get preliminary lending pre-approval. Knowing your budget prevents heartbreak on homes you can't actually afford and clarifies which neighborhoods realistically fit.

Talk to your kids honestly about the move. Their questions and concerns often reveal considerations you missed as adults — friends, activities, specific school programs.

Four Months Before: Community Selection

By this stage, you're narrowing to a specific target area:

Take a second scouting trip focused on daily-life logistics. Drive the school routes, visit grocery stores, tour the parks and recreation facilities, see what's actually within 15 minutes of the neighborhoods you're considering.

Meet with a local real estate agent who knows the family relocation market. Ask specifically about school zones, family neighborhood characteristics, and pockets that work for kids' ages.

Verify exact school attendance zones for your target addresses. Community names don't always match school assignments. Call Horry County Schools directly with specific addresses.

Research extracurriculars — sports leagues, dance studios, music teachers, tutoring services, faith communities, whatever your kids currently participate in.

Check healthcare options for any specific medical needs. Verify specialists, pediatricians, and any ongoing care resources are actually available.

 Moving to the Grand Strand with School-Age Kids A Full Checklist

Three Months Before: The Home Search Intensifies

Now you're actively shopping:

Start watching listings in your target neighborhoods. Understand pricing trends by watching what sells and at what prices.

Take your kids on a virtual tour if physical visits aren't practical. Even young children benefit from seeing their potential new home before it becomes reality.

Consider timing carefully. Ideally you want to be under contract by 60-75 days before the school year starts, allowing enough time for closing plus moving.

Research summer camps or activities that might help kids meet peers before school starts. A week at a summer camp near your new home helps kids arrive on Day One of school with some existing connections.

Two Months Before: Contract and Preparation

You should be under contract by now:

Complete the standard due diligence — inspections, insurance quotes, HOA review, financing progress.

Start telling your kids' current schools about the move. Request records transfer preparation, letters of recommendation for special programs if needed, and any other academic transitions.

Enroll kids in Horry County Schools for the new academic year. This can happen 60 days out for enrollment paperwork, with actual attendance starting at the school year.

Verify school transportation, before-and-after-school care, and any specific program enrollments.

Introduce yourself and kids to your future school principal via email. Ask if there's a way to connect with other new families or a school-provided welcome program.

Book your movers. Summer is peak moving season and reliable movers book up. Reserve 4-6 weeks out at minimum.

One Month Before: Logistics

Physical moving preparation:

Change of address filings with USPS, banks, subscriptions, and important accounts.

Transfer school records officially — request current school send them to the new school.

Establish medical care in the new area. Even before the move, have pediatrician appointments scheduled for the first month after arrival for well-checks and continuity of care.

Register kids for summer activities in the new area. Camps, sports leagues, or community classes give them peer connections before school starts.

Set up utility transfers, internet installation, and other service arrangements for the new home.

Involve kids in packing their own rooms. It gives them agency in the move and helps process the emotional transition.

Two Weeks Before: Final Push

The final logistical push:

Confirm closing timing with your attorney and lender.

Confirm movers, timing, and logistics.

Handle utility transfers final steps.

Deep clean and pack the old home.

Have a family conversation about what you're each looking forward to and what you're each nervous about. Older kids especially benefit from this.

Moving Day and the First Week

The actual move:

Focus on making the new home feel like home quickly. Set up kids' bedrooms first — familiar furniture, bedding, and possessions in a new room create emotional continuity.

Explore the neighborhood together in the first few days. Walk to the park, visit the local pool if HOA has one, drive by the school.

Establish new routines — where you'll go for breakfast, the grocery store you'll use, the coffee shop that becomes your new spot. Routines reduce the "everything is new" overwhelm.

Meet neighbors intentionally. Introduce yourself and your kids. Small social contacts in week one become the foundation of neighborhood friendship over months.

The First Semester

The school year begins:

Expect an adjustment period. Even kids who seem to transition smoothly typically go through 4-8 weeks of adjustment to new school and social environments.

Attend school events, PTA meetings, and community gatherings. This is how you and your kids become part of the community rather than temporary residents.

Stay closely connected with your kids about their new experience. Frequent low-key conversations about school, friends, and how they're feeling catch issues early.

Give it time. Full family integration into a new area typically takes 12-18 months. Six-month check-ins reveal whether the family is on track.

For broader inventory context if you're still narrowing your target area, browsing Conway real estate alongside Carolina Forest real estate and Myrtle Beach real estate shows the different family-oriented markets available.

Two Things I Tell Every Family Considering a Grand Strand Move

First, prioritize school zone above almost every other consideration. You can update a kitchen. You can add a fence. You can change paint colors. You cannot easily change your kids' school assignment mid-year. Get the school zone right first, then evaluate homes within that zone.

Second, rent for a season if possible before buying. Six months in a short-term rental gives you and your kids time to actually experience the community before locking into a specific home. Families who make this investment consistently make better long-term neighborhood choices than families who buy on a weekend visit.

Key Takeaways

Moving to the Grand Strand with school-age kids works best when families work backwards from the target school year rather than forward from a move date. The six-month runway allows for proper community selection, financial planning, kid preparation, extracurricular research, and healthcare setup. Home shopping intensifies at three months out, with contract targeting by 60-75 days before school starts. Physical moving logistics dominate the final two months. The first semester in a new home requires realistic expectations about adjustment periods, intentional community engagement, and continued family communication about how everyone is really doing. Renting for a season before buying is often the smartest move for families who can afford it. Getting the school zone right is more important than most other considerations combined. Families who follow a structured runway and prioritize kid transition consistently succeed. Families who improvise the timeline often end up regretting neighborhood or school choices they made in a hurry. The Grand Strand is a great fit for most relocating families — but only when the family arrives with a plan.

About Greg Harrelson

Greg Harrelson is a seasoned Realtor® with more than 30 years of experience serving the Myrtle Beach and Grand Strand markets. As the founder of Century 21 The Harrelson Group, Greg has built his career helping buyers, sellers, and investors achieve success in every corner of the coastal Carolina real estate market. His expertise spans residential homes, investment properties, land development, and coastal condos. Known for his deep local knowledge, innovative marketing strategies, and commitment to personal service, Greg consistently helps clients reach their real estate goals while navigating the ever-changing market with confidence and precision.